
Seaport sees different trends across the restaurant stocks, with CAVA offering strong growth potential, while Wendy’s, Chipotle, Starbucks and McDonald’s face concerns around traffic, valuation and business performance.
- Restaurant traffic fell 2.4% year over year in August, reversing recent gains.
- Rising oil prices, Treasury yields and inflation, including a 27% jump in gasoline prices, are putting additional pressure on consumers.
- While Seaport Research rated Wendy’s, Chipotle, Starbucks and McDonald’s ‘Neutral’, the firm rated CAVA ‘Buy’.
Restaurant stocks are facing a tougher consumer backdrop, but Seaport Research sees meaningful differences beneath the surface. The firm initiated coverage on five major chains, rating Wendy’s Co. (WEN), Chipotle Mexican Grill (CMG), Starbucks (SBUX) and McDonald’s (MCD) ‘Neutral’ while naming CAVA Group (CAVA) as ‘Buy’. The calls come as weaker restaurant traffic, rising oil prices, elevated Treasury yields and persistent inflation pressure consumers and operators.
The research comes at a challenging time for the restaurant industry. Placer.ai’s August 2026 data showed visits to dining chains fell 2.4% from last year, reversing the small gains seen in June and July. At the same time, Bureau of Labor Statistics data showed August inflation remained high, with restaurant prices up 3.4% and grocery prices up 2.2%. Gasoline prices jumped more than 27% year-on-year, potentially pushing consumers to cut discretionary spending and eat at home.
Combined with a spike in crude oil and Treasury yields, the backdrop is forcing analysts to separate companies with durable competitive moats from those facing structural traffic erosion, a distinction Seaport's five initiations attempt to draw clearly. The stocks edged higher between 0.03% and 0.7% overnight, after dropping between nearly 2% and over 8% in regular session.
Wendy's: Traffic Decline Overshadows Turnaround Hopes
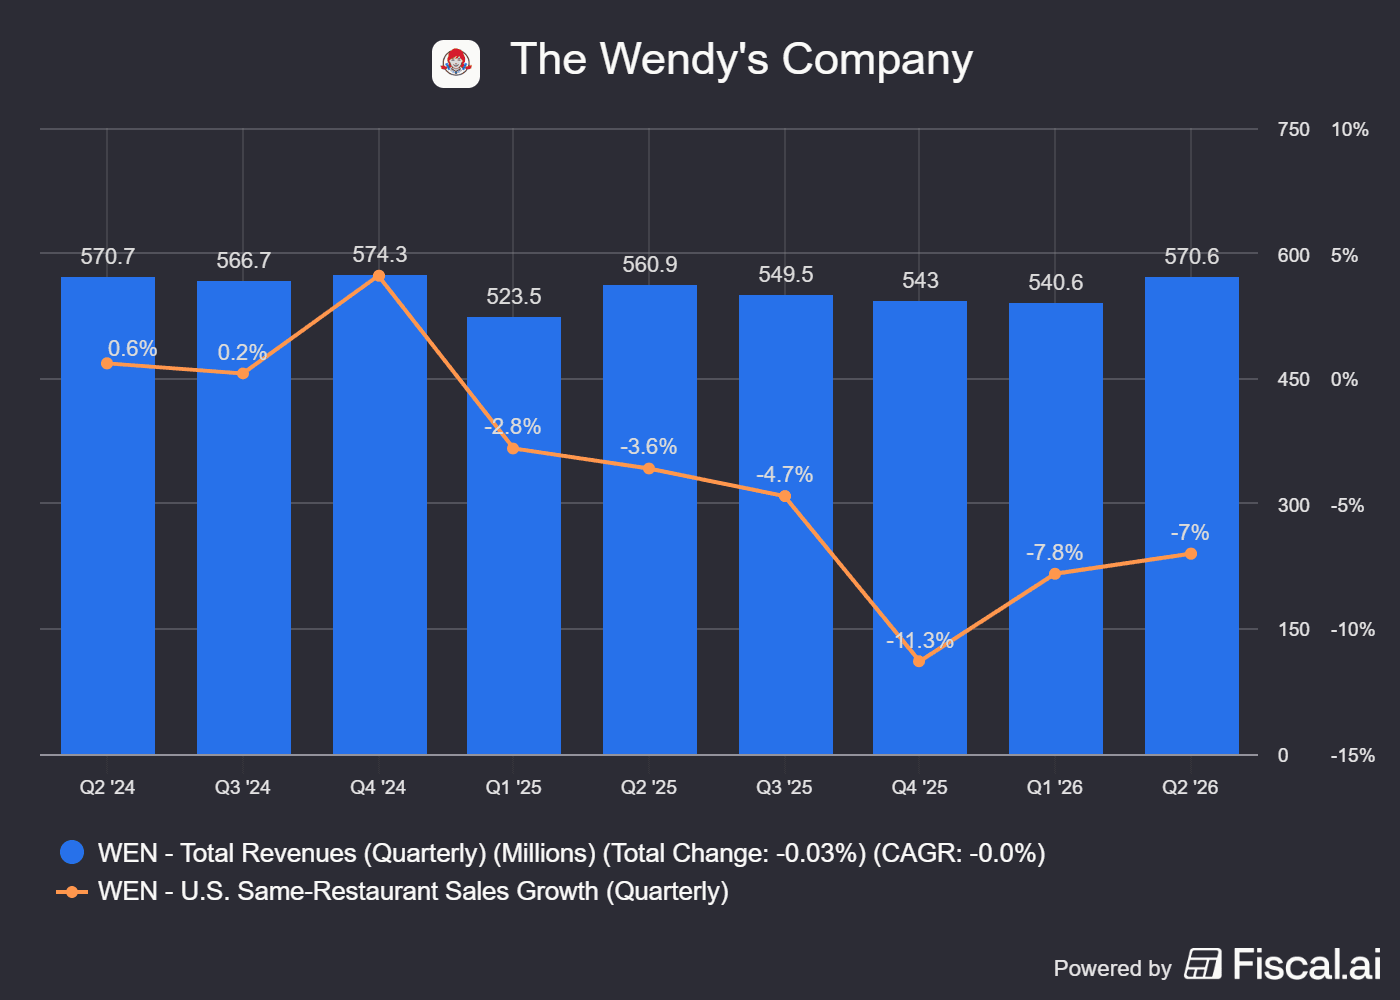
Seaport initiated Wendy's with a ‘Neutral’ rating, and the tone of the note was notably grim. The analyst wrote that the company's fundamentals are deteriorating faster than at any point in the brand's modern history, pointing to a second-quarter U.S. same-restaurant sales decline of 7.0% alongside a 12.5% drop in traffic, a gap between sales and traffic that suggests the chain is leaning on pricing to offset a shrinking customer base rather than genuine demand strength.
The note also addressed one of the more persistent storylines around Wendy's stock: speculation that activist investor Trian Fund Management, led by Nelson Peltz, could push for a take-private transaction. Trian's combined economic exposure to Wendy's exceeds 24%, a stake large enough to fuel go-private chatter for years. Seaport told investors that, based on its checks, Trian has no plans to pursue a take-private bid at this time, effectively removing what some investors had treated as a valuation floor or catalyst.
Chipotle: Best-In-Class Brand, Fully Priced Stock
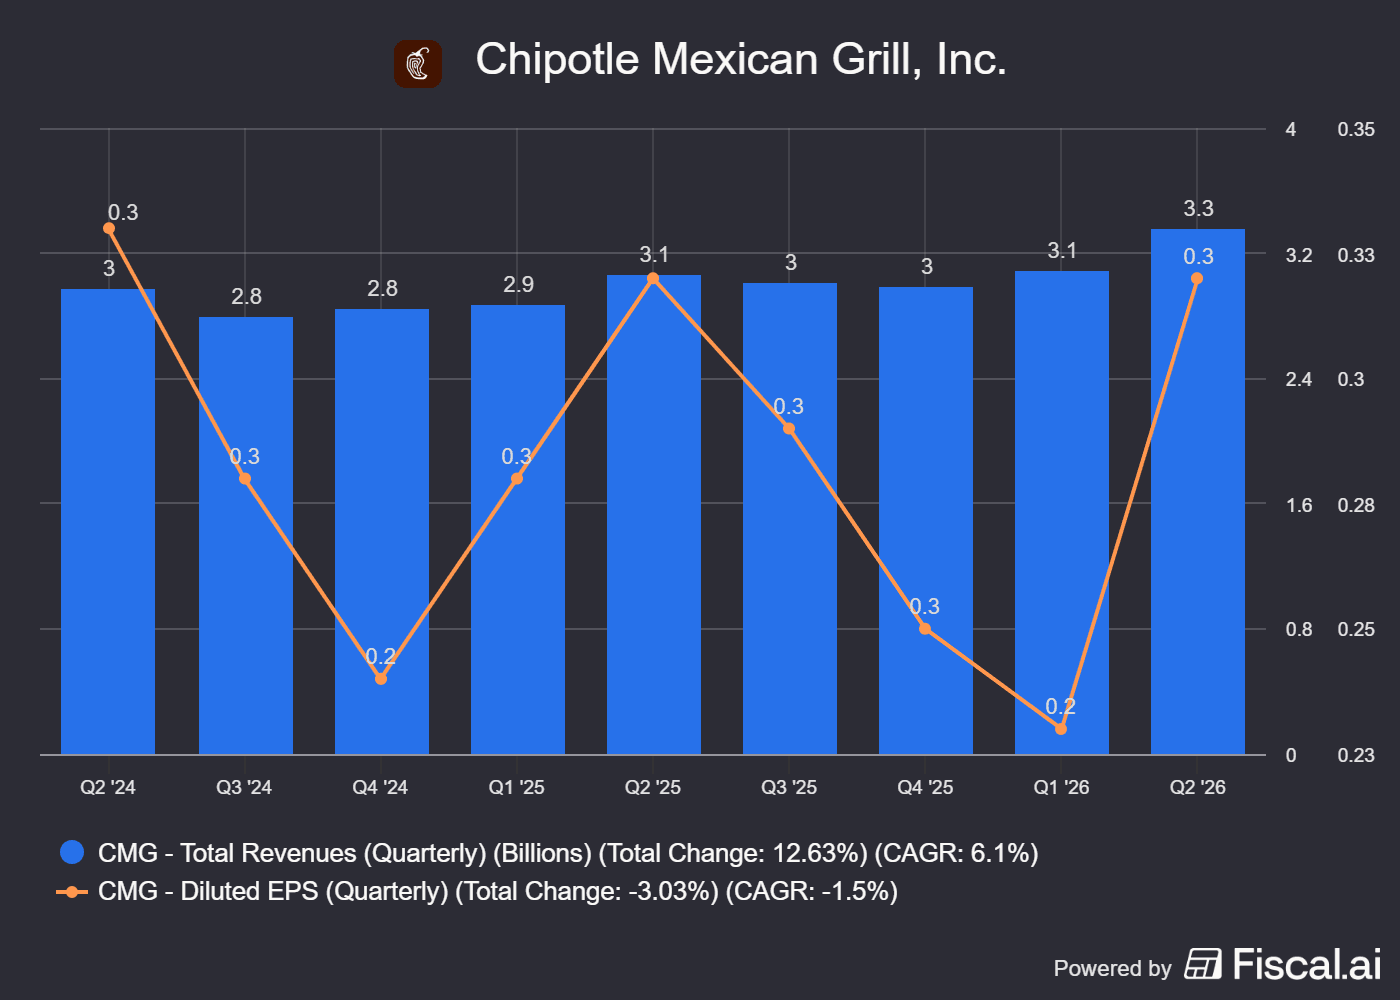
Chipotle Mexican Grill stock also drew a ‘Neutral’ rating despite what Seaport calls an unmatched position in the industry. The analyst noted Chipotle remains the largest and most profitable fast-casual brand in the U.S., with systemwide sales on pace to cross $13 billion this year. That scale and digital infrastructure have made Chipotle a perennial darling among growth investors.
The issue, per Seaport, is price. At roughly 28 times next-12-months earnings, the stock trades at a price-to-earnings-to-growth ratio between 1.5x and negative 2x — a range the firm characterized as "close to fair value" rather than a bargain. So the market has already priced in much of Chipotle's continued execution, leaving limited room for multiple expansion even if operating results stay strong.
Starbucks: Brand Strength Meets A Premium Multiple
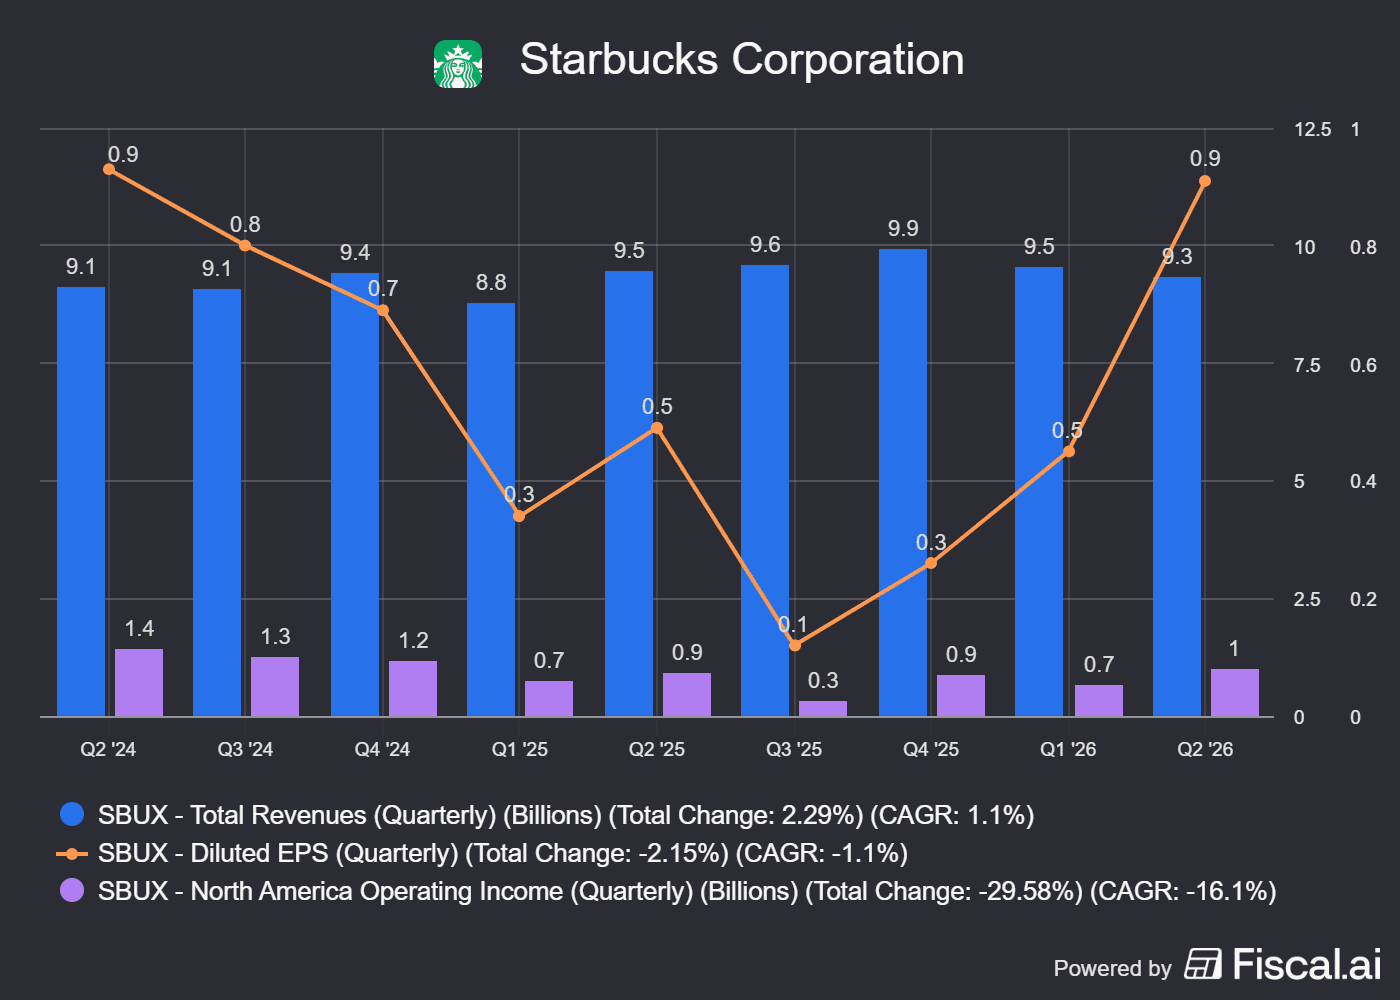
Starbucks stock received the same ‘Neutral’ treatment from Seaport analyst Eric Gonzalez, who struck a notably upbeat tone on brand health even while holding back on the rating. Gonzalez pointed to brand affinity, consideration and purchase intent all sitting at five-year highs, alongside third-quarter sales growth that was broad-based, strong across income cohorts and among both loyalty members and non-members alike.
That breadth suggests Starbucks' turnaround efforts, including menu simplification and store-experience investments, are gaining traction with a wide swath of its customer base. Valuation is again the sticking point here. Starbucks trades at roughly 29 times expected forward earnings, well above the roughly 20-times average of its peer group. Seaport described the stock as "close to fair value," implying that even genuine operational momentum may not be enough to drive outperformance from current levels.
McDonald's: Scale Advantages, Squandered In 2026
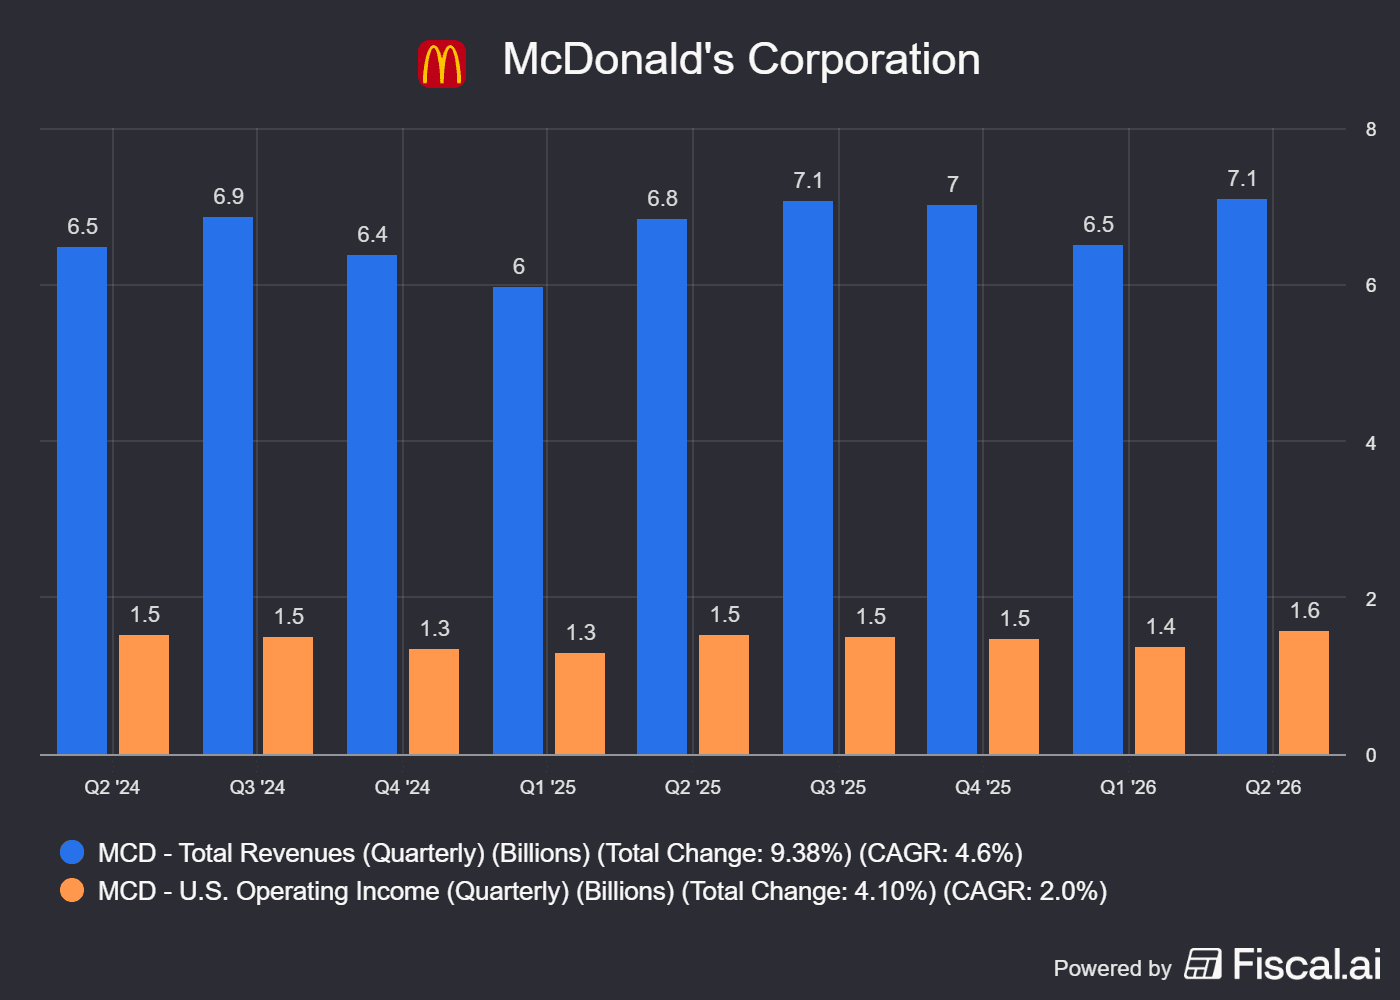
The analyst was blunt in describing McDonald's scale advantages and market presence as unmatched within quick-service restaurants but argued McDonald's has missed the opportunity to fully use that scale this year, with execution falling short of expectations throughout.
Compounding the execution concerns is a genuinely difficult operating backdrop. Seaport cited rising interest rates, economic pressure weighing on lower-income consumers, elevated beef costs and an unrelenting competitive environment as headwinds facing both McDonald's corporate operations and its network of franchised owner-operators.
CAVA: Brand Awareness And New Stores Drive Bull Case
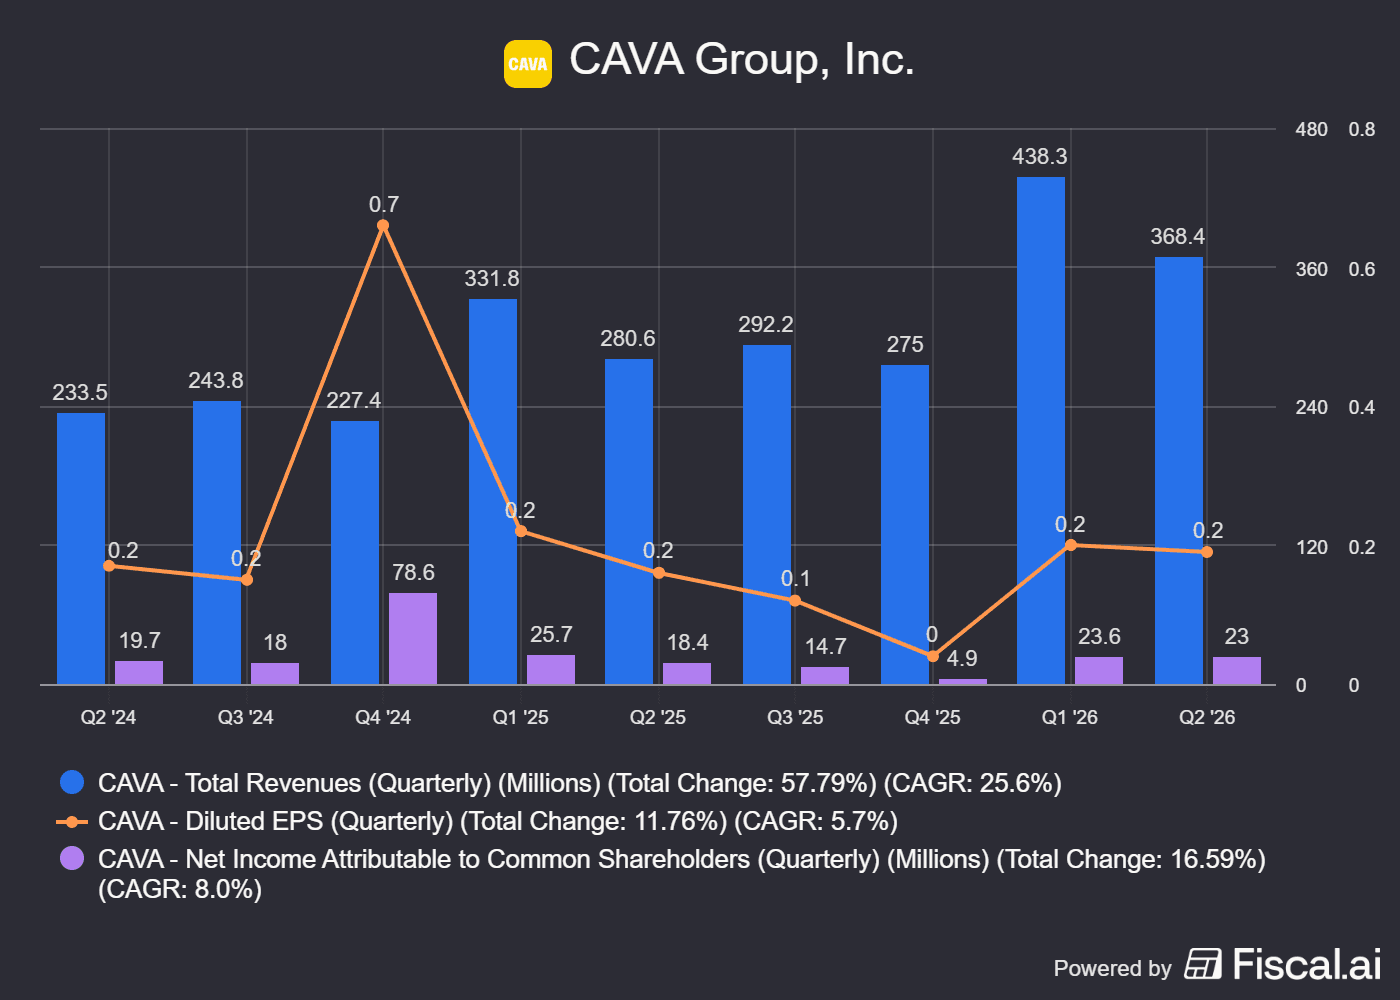
Cava Group stood apart as Seaport's Buy-rated name in the group, with a $58 price target, implying a 16% upside to the stock’s last closing price. The thesis centers on category scarcity: Seaport's analyst described Cava as the only scaled Mediterranean fast-casual brand with meaningful runway and an opportunity to define the category the way Chipotle did for Mexican food years earlier.
Seaport’s bullish view is based on two factors. CAVA still has lower brand awareness than larger fast-casual chains, leaving room to grow as it expands. Also, newer restaurants are seeing stronger same-store sales growth than the overall chain, suggesting improving performance as the brand grows.
WEN, CMG, SBUX, MCD, CAVA Stocks: Retail Stance
On Stocktwits, retail sentiment around Wendy’s remained ‘bearish’, while sentiment around Starbucks and McDonald's remained ‘bullish’ and ‘neutral’, respectively. Sentiment around Chipotle jumped to ‘bullish’ from ‘bearish’ the previous day and that of CAVA improved to ‘extremely bullish’ from ‘bullish’.
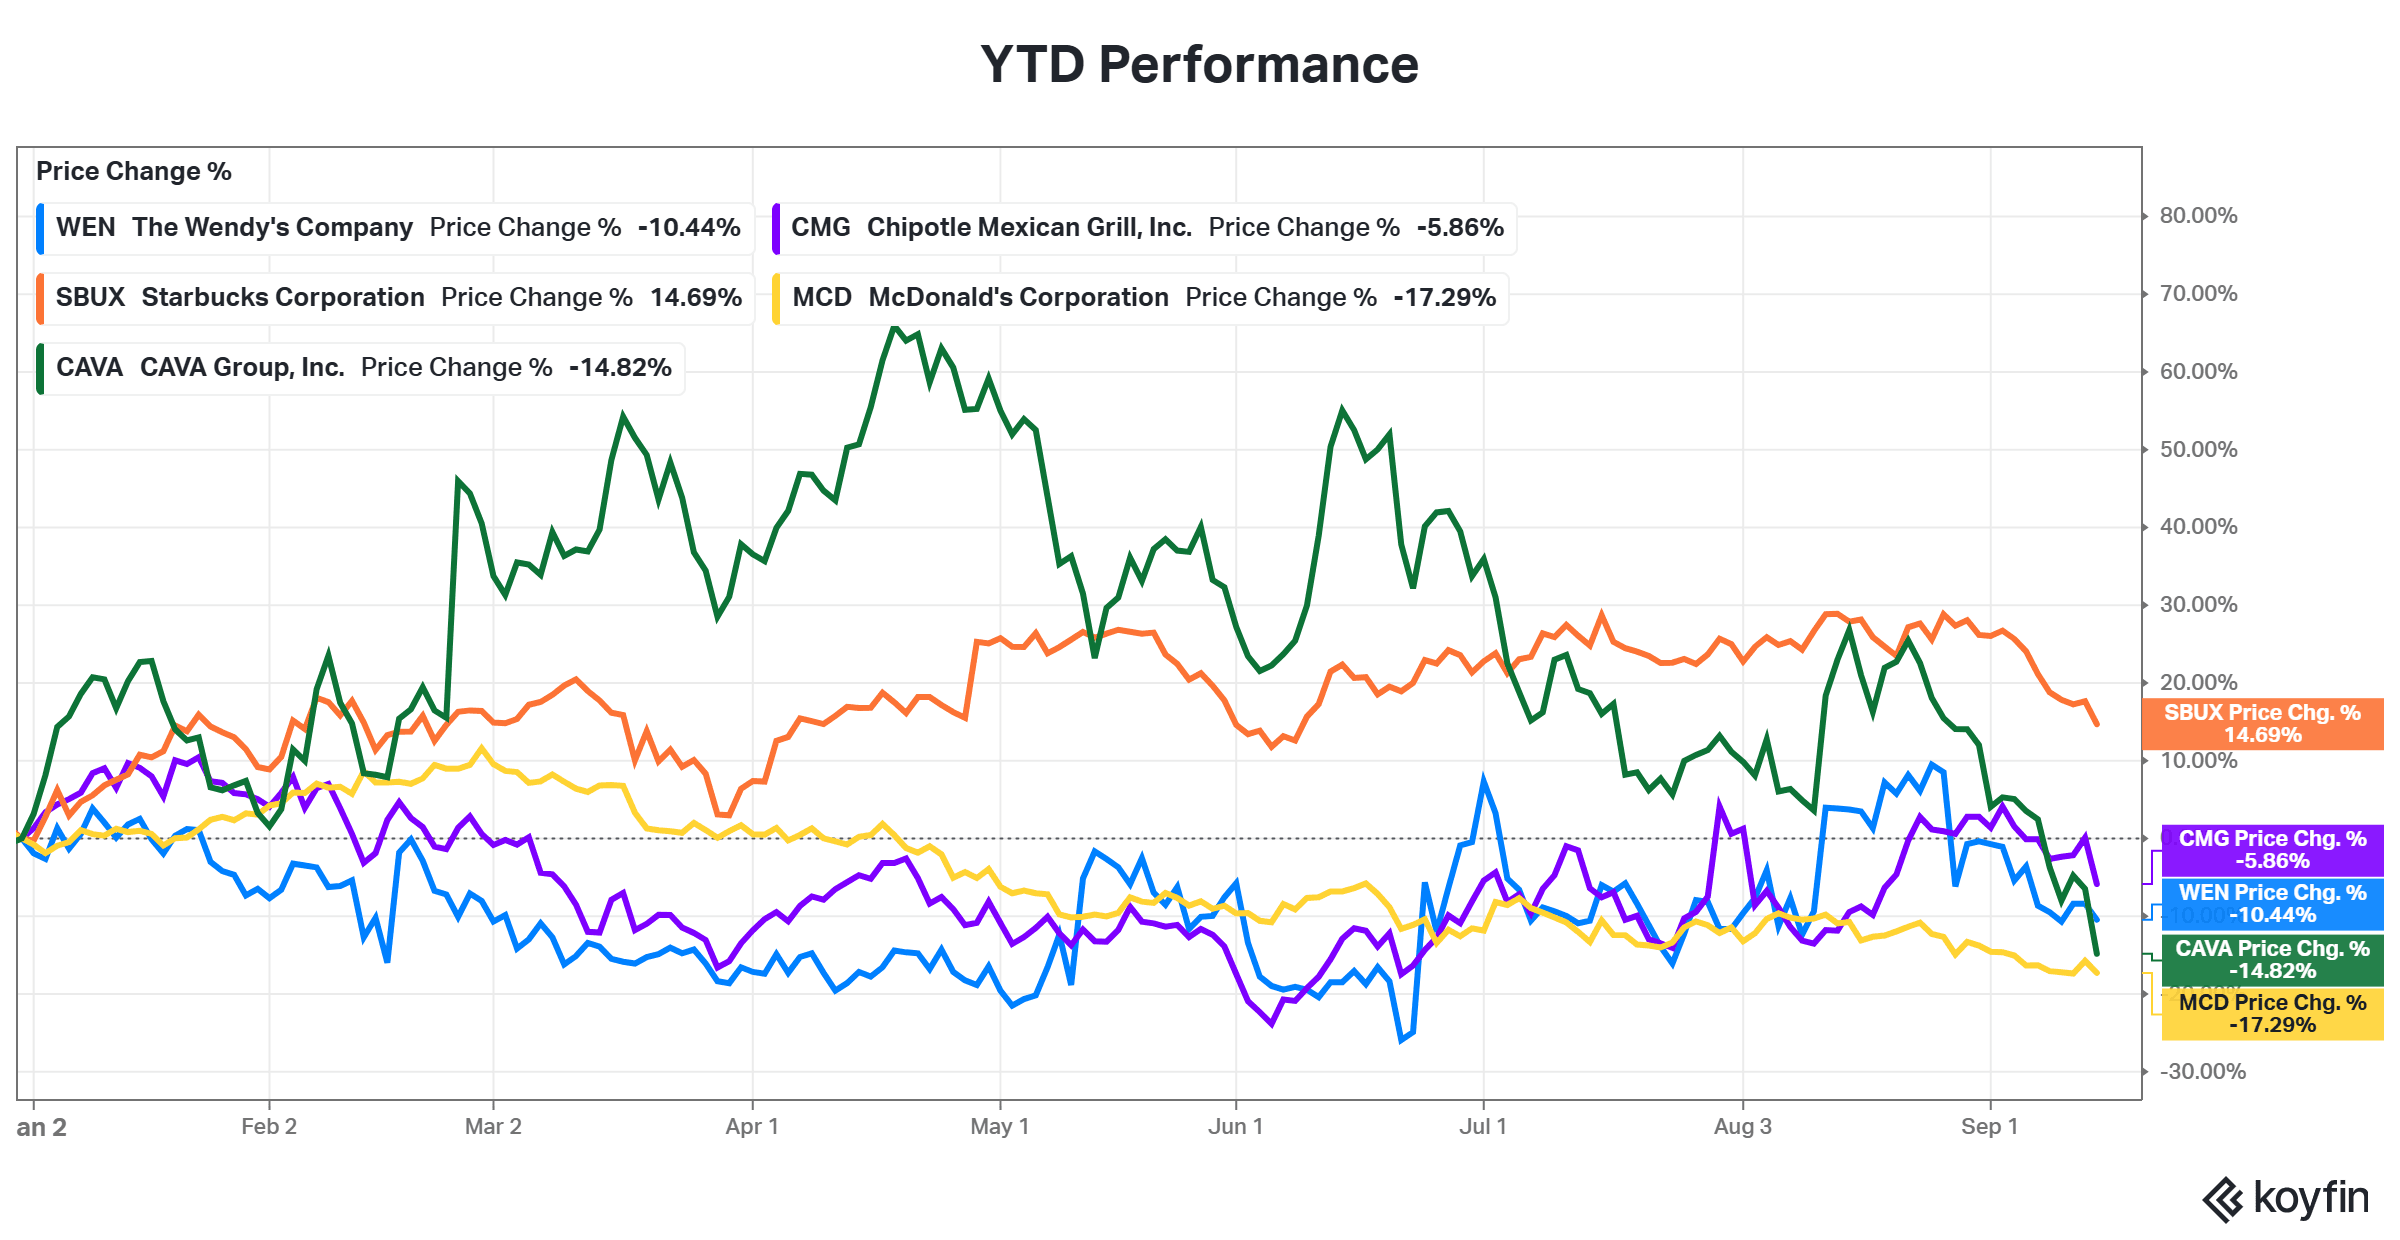
In the past twelve months, CAVA, WEN, CMG, and MCD stocks have declined between 11% and 22%, while SBUX stock has gained 14%.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
