
Intuit expects total fiscal 2027 revenue of $23.08 billion to $23.37 billion, representing 8% to 9% growth, compared with its previous 9% to 10% forecast.
- Intuit cut its FY27 Credit Karma revenue growth forecast to 3% to 7%, from 11% to 13% previously.
- Barclays said Credit Karma is “now also a major segment that needs fixing,” but called the shares “cheap.”
- Intuit projected second-quarter revenue growth of 6% to 7% and reiterated its full-year operating income and EPS guidance.
Intuit (INTU) stock drew a wave of price target cuts Friday after the company lowered its fiscal 2027 revenue outlook, with analysts pointing to slowing growth at Credit Karma, AI-related challenges, and execution concerns.
Barclays said Credit Karma is "now also a major segment that needs fixing," according to the note cited by TheFly. The firm expects continued near-term headwinds for Intuit shares. Barclays is "not sure there is a short-term comeback here" but says the shares are "cheap."
At the time of this writing, INTU stock was down over 9% in Friday’s premarket and was among top-trending tickers on Stocktwits.
Analysts Flag Credit Karma, AI Concerns
Jefferies described Intuit's fiscal first-quarter report as "more eventful than expected," pointing to the planned Mailchimp divestiture at a loss and macroeconomic and AI-related headwinds affecting Credit Karma.
The firm said Intuit needs to improve execution to regain investor credibility, although it sees an attractive risk/reward at current share levels, per TheFly.
Morgan Stanley said strong earnings-per-share (EPS) execution was overshadowed by the Credit Karma-driven reduction in annual revenue guidance and weaker second-quarter outlook. After a selloff, the firm views valuation as "supportive," but AI-discovery risk and Tax execution keep it at ‘Equal Weight’ despite what it sees as a "strategically positive" Mailchimp exit.
UBS also flagged the Credit Karma slowdown, softer second-quarter revenue guidance, AI disruption concerns and moderating new-customer growth in Global Business Solutions.
BofA pointed to both cyclical and secular pressures on Intuit, while Wells Fargo said resilient Global Business Solutions growth and continued mid-market momentum were overshadowed by weaker-than-expected Credit Karma performance.
| Firm | Rating | Previous Target | New Target |
| Barclays | Overweight | $408 | $385 |
| Jefferies | Buy | $500 | $445 |
| UBS | Neutral | $360 | $315 |
| Morgan Stanley | Equal Weight | $315 | $310 |
| BofA | Neutral | $360 | $310 |
| Wells Fargo | Equal Weight | $330 | $320 |
What Intuit's Latest Earnings Show
Intuit reported fiscal first-quarter revenue of $4.35 billion, up 12% year over year, narrowly beating the Fiscal.ai consensus estimate of $4.31 billion. Global Business Solutions revenue rose 15% year-over-year, and Online Ecosystem revenue increased 20%.
Credit Karma revenue rose 9% to $708 million, but Intuit lowered its fiscal 2027 revenue growth forecast for the segment to 3% to 7%, down from its previous projection of 11% to 13%.
The company now expects total fiscal 2027 revenue of $23.08 billion to $23.37 billion, representing 8% to 9% growth, compared with its previous 9% to 10% forecast.
Intuit also projected second-quarter revenue growth of 6% to 7%, while reiterating its full-year GAAP and non-GAAP operating income and earnings-per-share guidance.
What Retail Thinks About INTU Stock
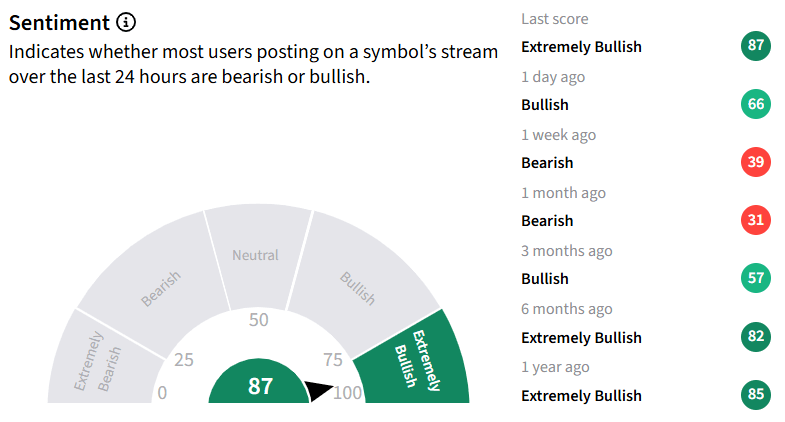
On Stocktwits, retail investors’ sentiment around INTU stock improved to ‘extremely bullish’ from ‘bullish’ a day ago amid ‘extremely high’ user message volume.
So far in 2026. INTU stock has plunged nearly 51%. Meanwhile, the Invesco NASDAQ 100 ETF (QQQM) and the Vanguard Information Technology ETF (VGT), which hold Intuit shares, have risen over 5% and 11%, respectively, over the same period.
See Also: White House Reportedly Replaces Cyber Director Sean Cairncross Amid Widespread US Tech Outages
For updates and corrections, email newsroom[at]stocktwits[dot]com.<








