
Markets are pricing roughly even odds of another Fed rate hike in October, leaving this week’s economic data and Fed commentary in focus.
- WTI crude oil futures fell back below $100 a barrel Monday after Saudi Arabia said its East-West pipeline could restore about half of its capacity within days.
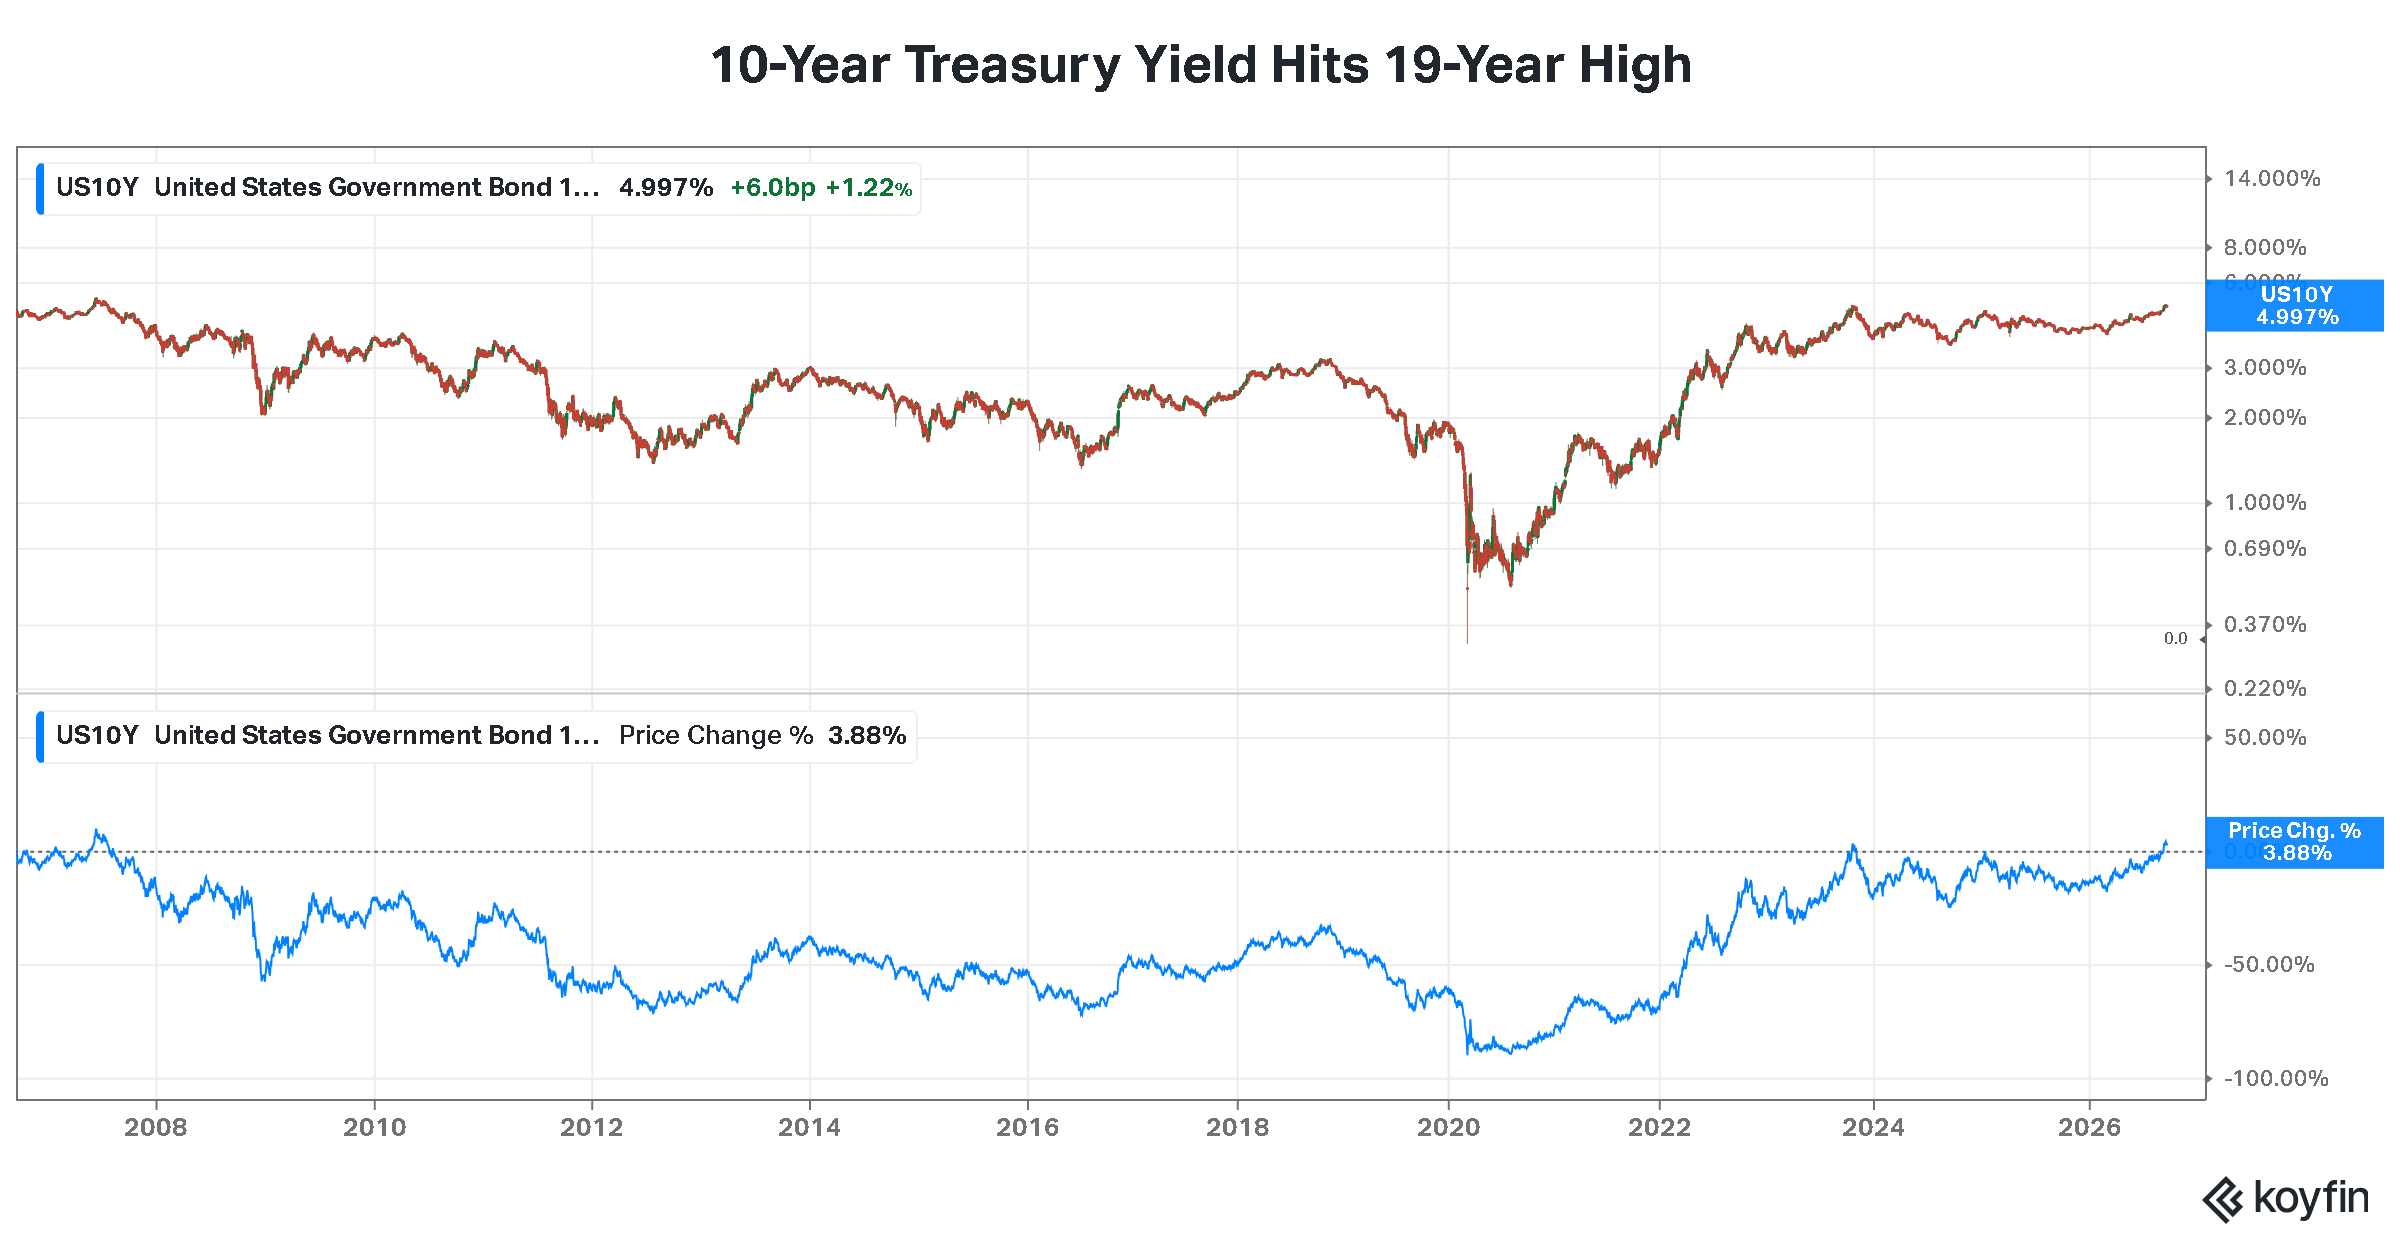
- The 10-year Treasury yield remains just below 5% after briefly crossing that level last week, while the seven-year yield is also near 5%.
- Bitcoin has recovered from its summer slide into the $60,000s but remains roughly 7% lower for the year.
Oil’s retreat from $100 a barrel, Treasury yields near multi-year highs, and Bitcoin’s uneven recovery could shape the market narrative this week, with investors watching whether pressure from energy and rates spills into risk assets.
Oil Near $100: Is The Supply Shock Easing?
WTI crude oil futures for October were trading around $98 a barrel Monday morning, down more than 2%, after ending the previous week at about $100.05. WTI had climbed over $105 during the week before pulling back on easing concerns about prolonged Saudi supply disruptions.
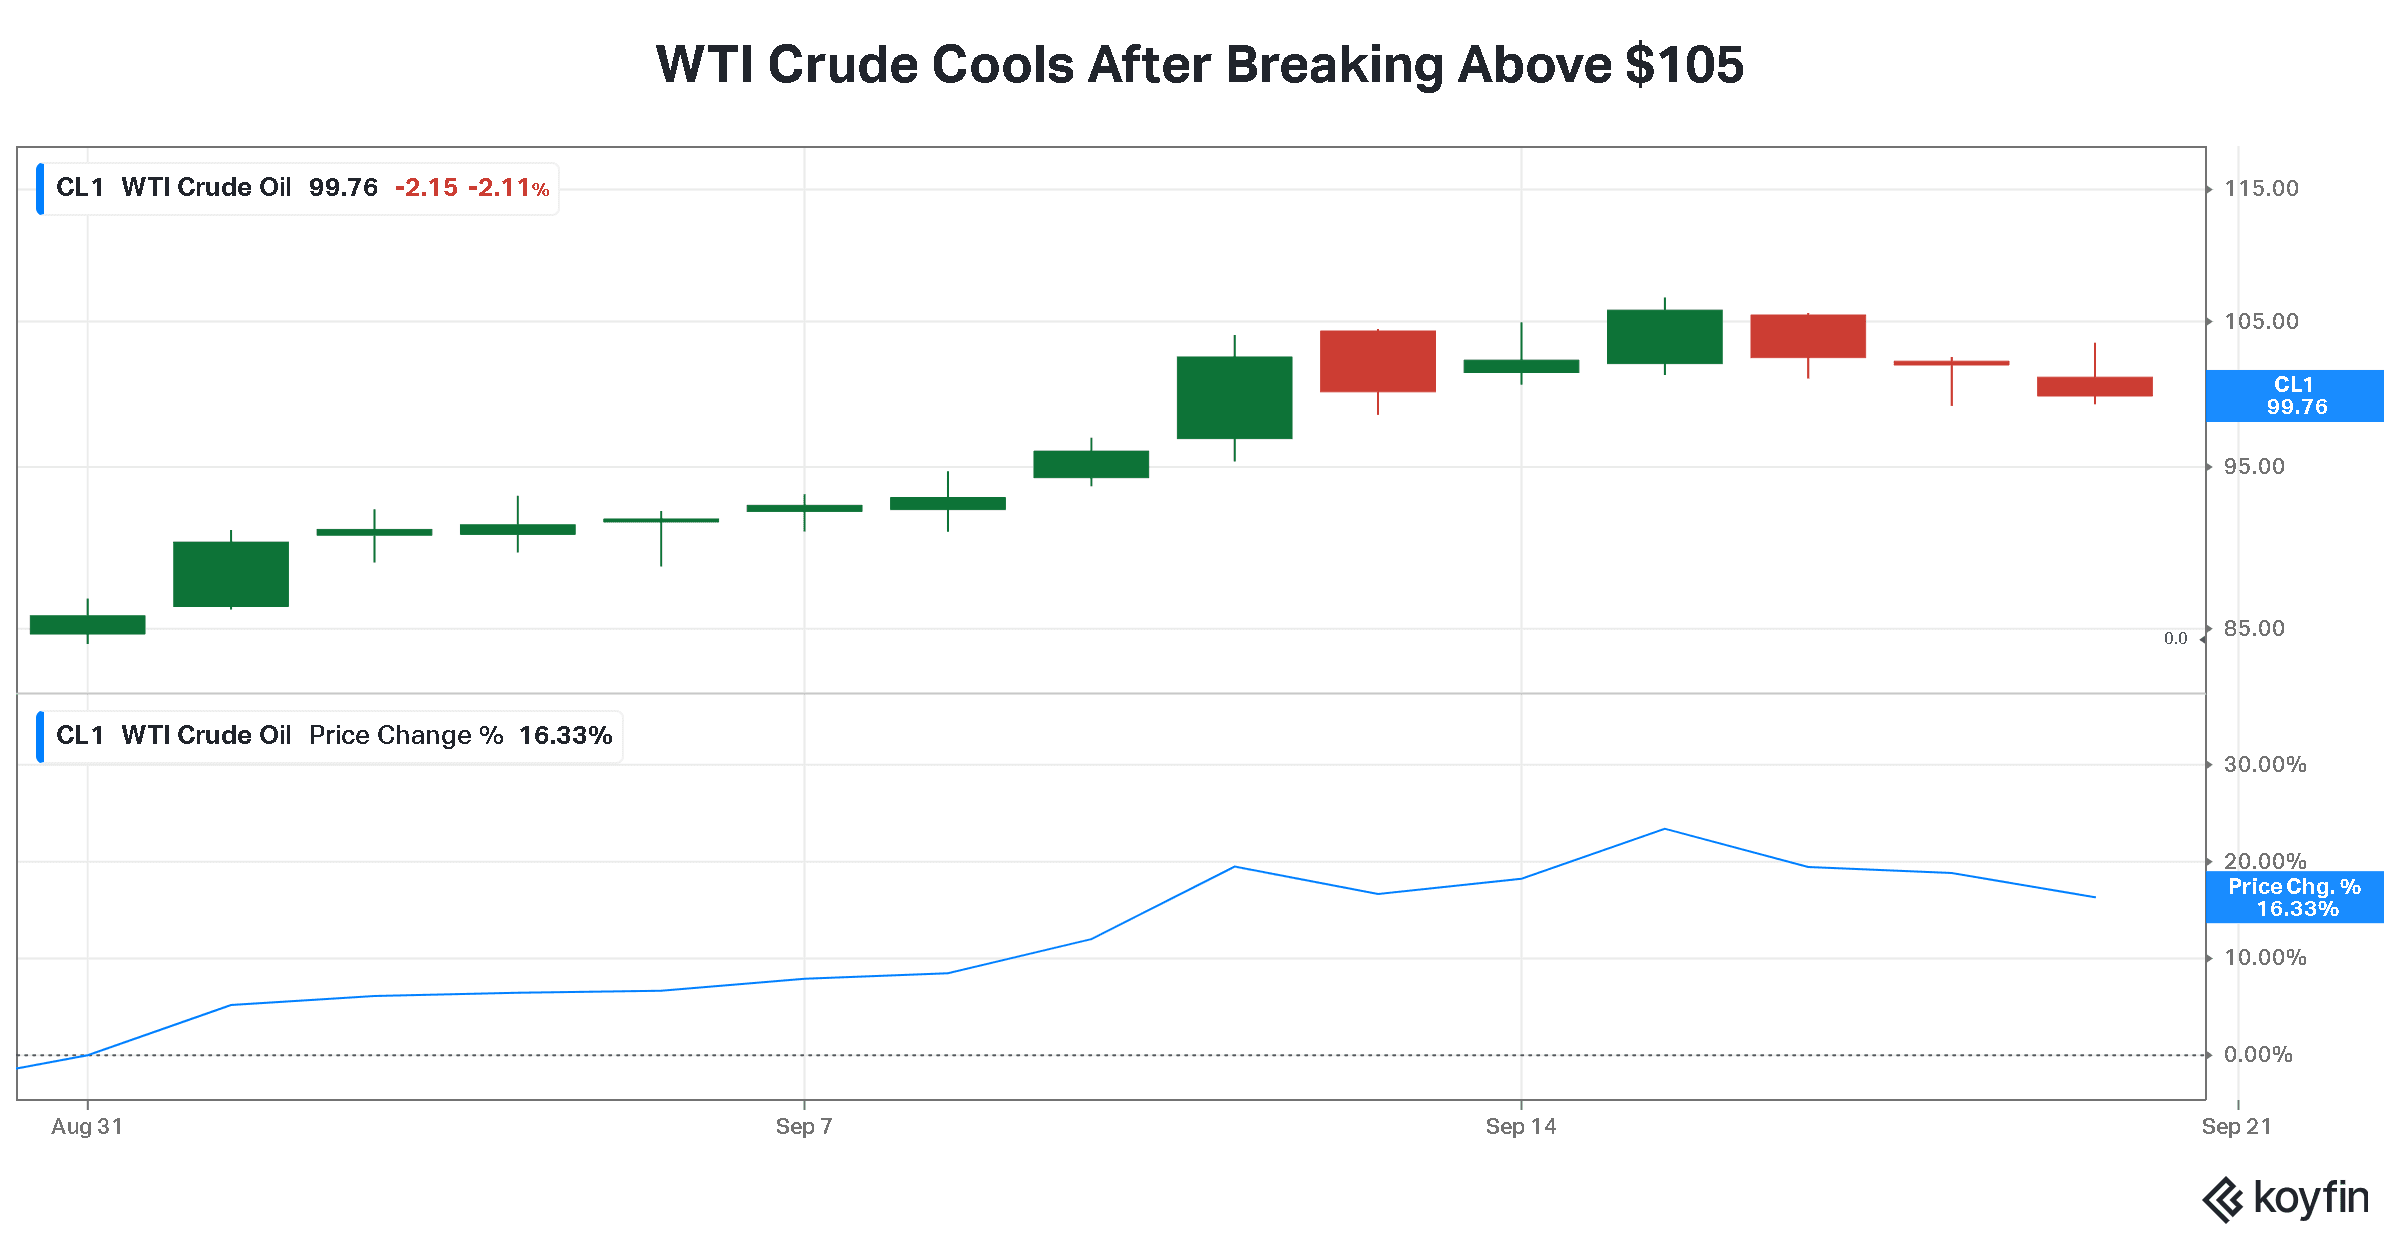
WTI crude oil futures jumped 4.38% last Monday to settle at $105.83 a barrel after Saudi Arabia suspended oil loadings at its Red Sea port of Yanbu following attacks by Iran-aligned Houthi forces on the kingdom’s East-West pipeline.
Prices eased after Saudi Arabia indicated that its East-West pipeline could resume roughly half of its capacity within days. U.S. Central Command also said oil shipments through the Strait of Hormuz had reached a six-month high, helping reduce some of the immediate supply concerns.
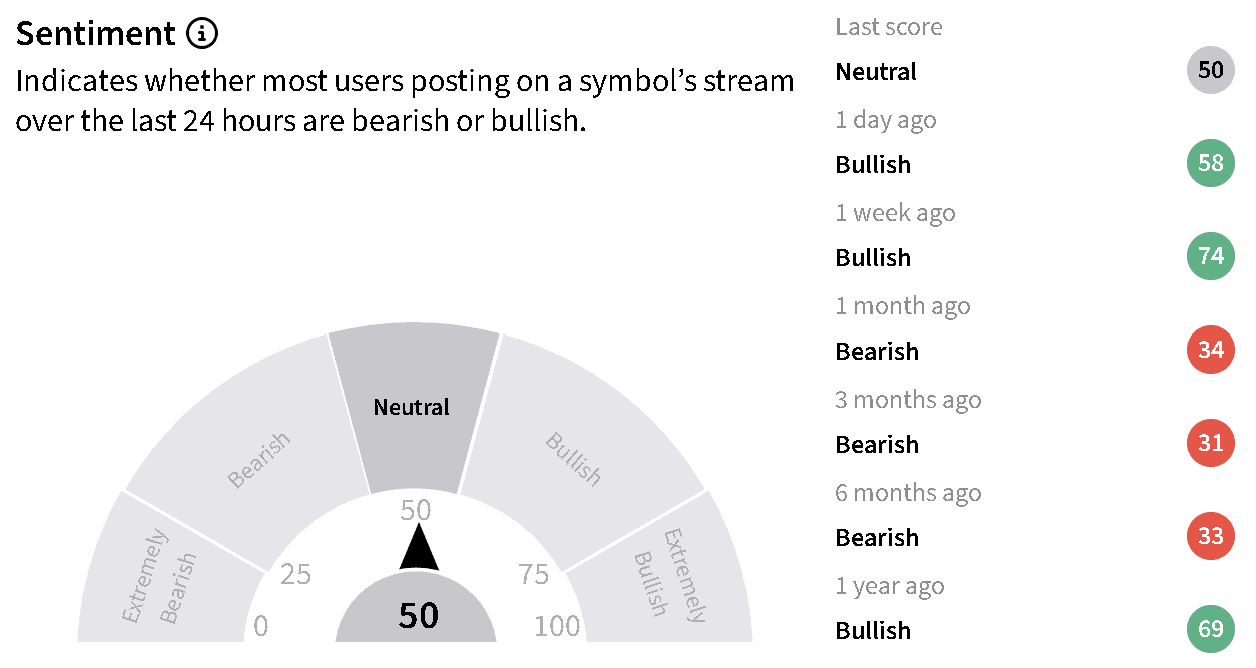
For markets, another sustained move above $100 could reinforce concerns about inflation and keep pressure on longer-term Treasury yields. The United States Oil Fund (USO) moved 1.6% lower in pre-market trade on Monday. On Stocktwits, retail sentiment around the ETF fell to ‘neutral’ from ‘bullish’ territory over the past week.
Treasury Yields Aren't Falling With The Fed
The 10-year Treasury yield crossed the psychological 5% level on Monday and closed above it Tuesday for the first time since July 2007, a level that weighed on stocks through the middle of the week even before the Fed acted.
On Wednesday, the Federal Reserve raised its benchmark interest rate by 25 basis points last week to a range of 3.75% to 4%, citing elevated inflation and a still-solid economy. This was the Fed’s first rate hike in three years.
Markets had priced in the move, but Fed Chair Kevin Warsh's press conference, in which he emphasized persistent inflation risk, turned an expected but tense session into a rout. Short-dated Treasuries sold off hard enough to send two-year yields to their highest level since 2024.
Bitcoin Above $80K: Recovery Or Rangebound Trade?
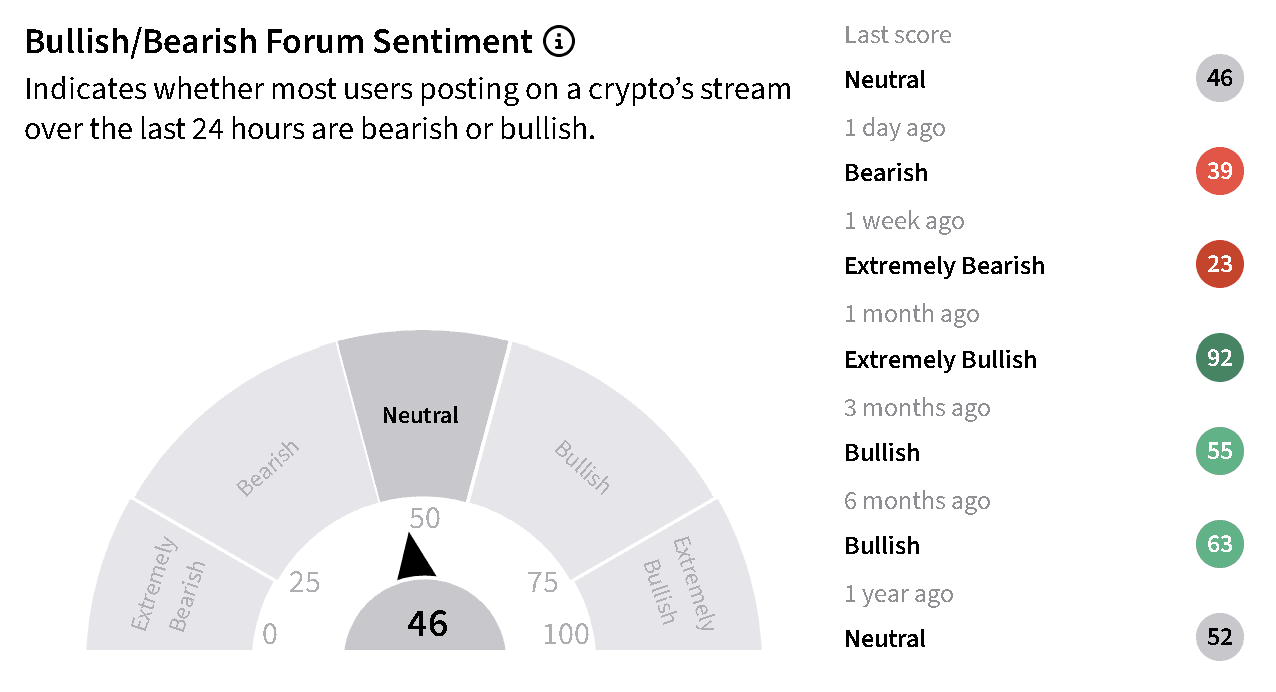
Against that backdrop, Bitcoin's chart looks almost calm. Bitcoin’s price gained over 3% in the last 24 hours, to cross $83,000 on Monday morning. On Stocktwits, retail sentiment around BTC moved to ‘bearish’ from ‘extremely bearish’ over the past week.
The apex cryptocurrency remains down by about 7% for the year, a period that included a sharp slide into the $60,000s earlier this year followed by a recovery into the low $80,000s by late summer and a mostly rangebound drift since.
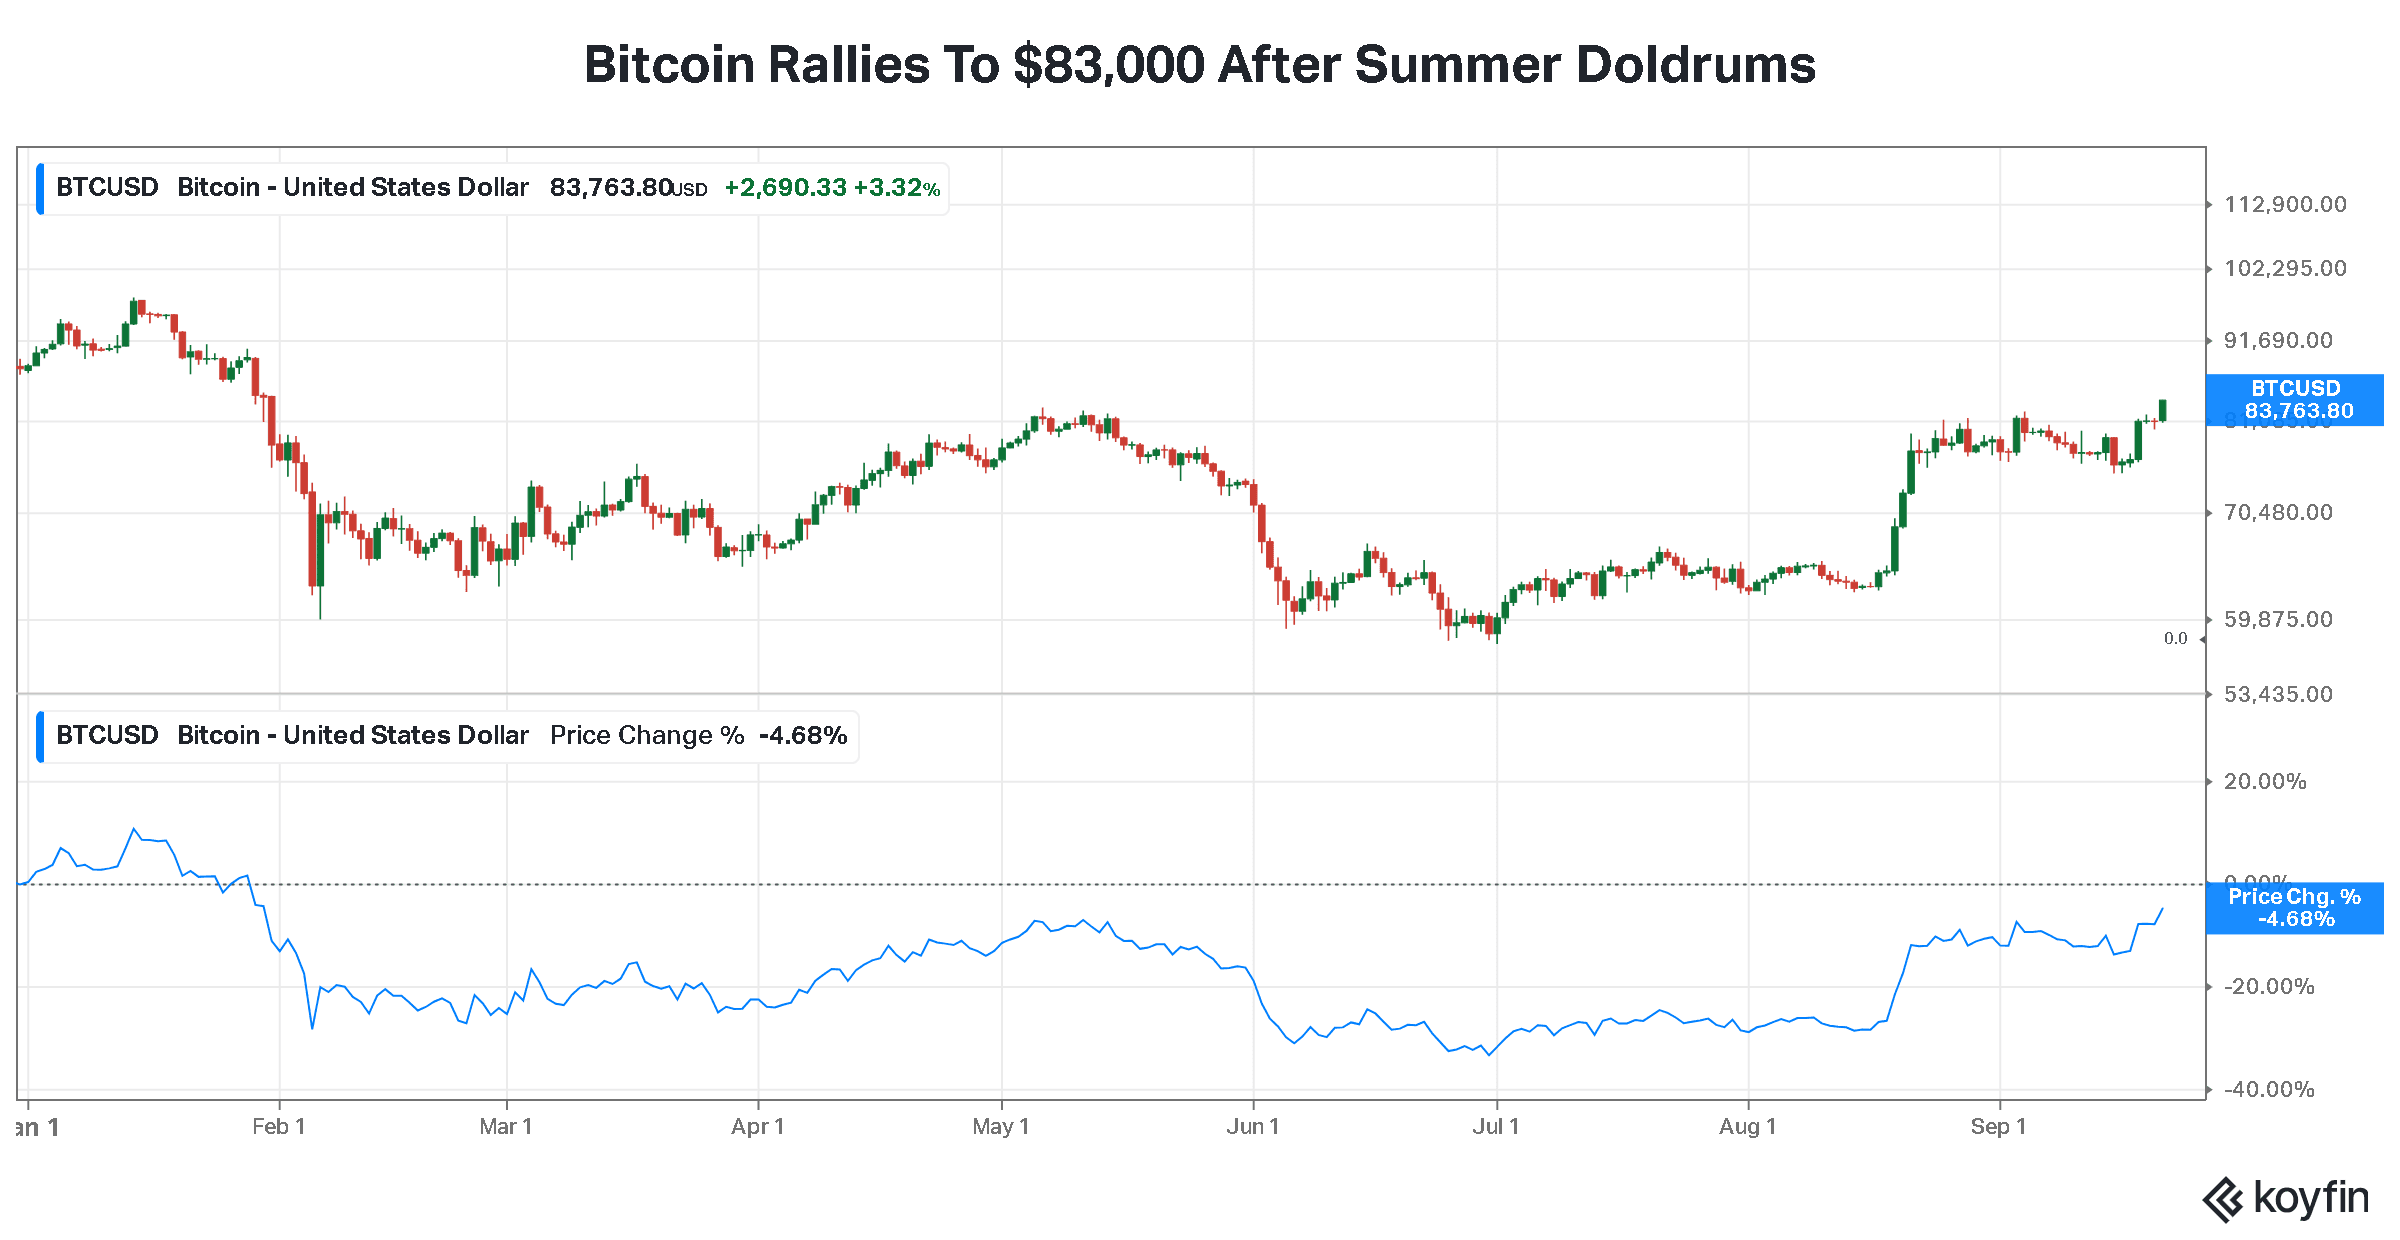
Bitcoin’s price dropped to $75,000 on Tuesday after the CLARITY Act vote didn’t clear the Senate. However, the cryptocurrency market charted higher after the Securities and Exchange Commission (SEC) cleared a path for authorized venues to offer tokenized U.S. stocks under a five-year conditional exemption the next day.
On Friday, the Commodity Futures Trading Commission (CFTC) also filed two new proposals, the Regulation Crypto Asset Transactions and the Regulation Crypto Asset Markets, with the White House's Office of Information and Regulatory Affairs (OIRA) for review, despite the Senate vote.
The Week Ahead: Market Signals To Watch
With the Fed's latest decision behind markets and odds of another October hike roughly split at around 53%, according to the CME FedWatch tool, this week's data will help shape expectations for the next move.
The calendar includes Tuesday's flash S&P Global Manufacturing and Services PMIs, followed by the final second-quarter (Q2) GDP revision, existing home sales, and durable goods orders.
August PCE inflation, the Fed's preferred gauge, will be the week's key release. Several Fed officials are also scheduled to speak, giving investors a chance to gauge how much of the committee shares Warsh's hawkish stance.
Middle East oil-supply developments, President Donald Trump’s meeting with China’s President Xi Jinping and the market's response to the Bank of Japan's hike are the main wildcards in the meantime.
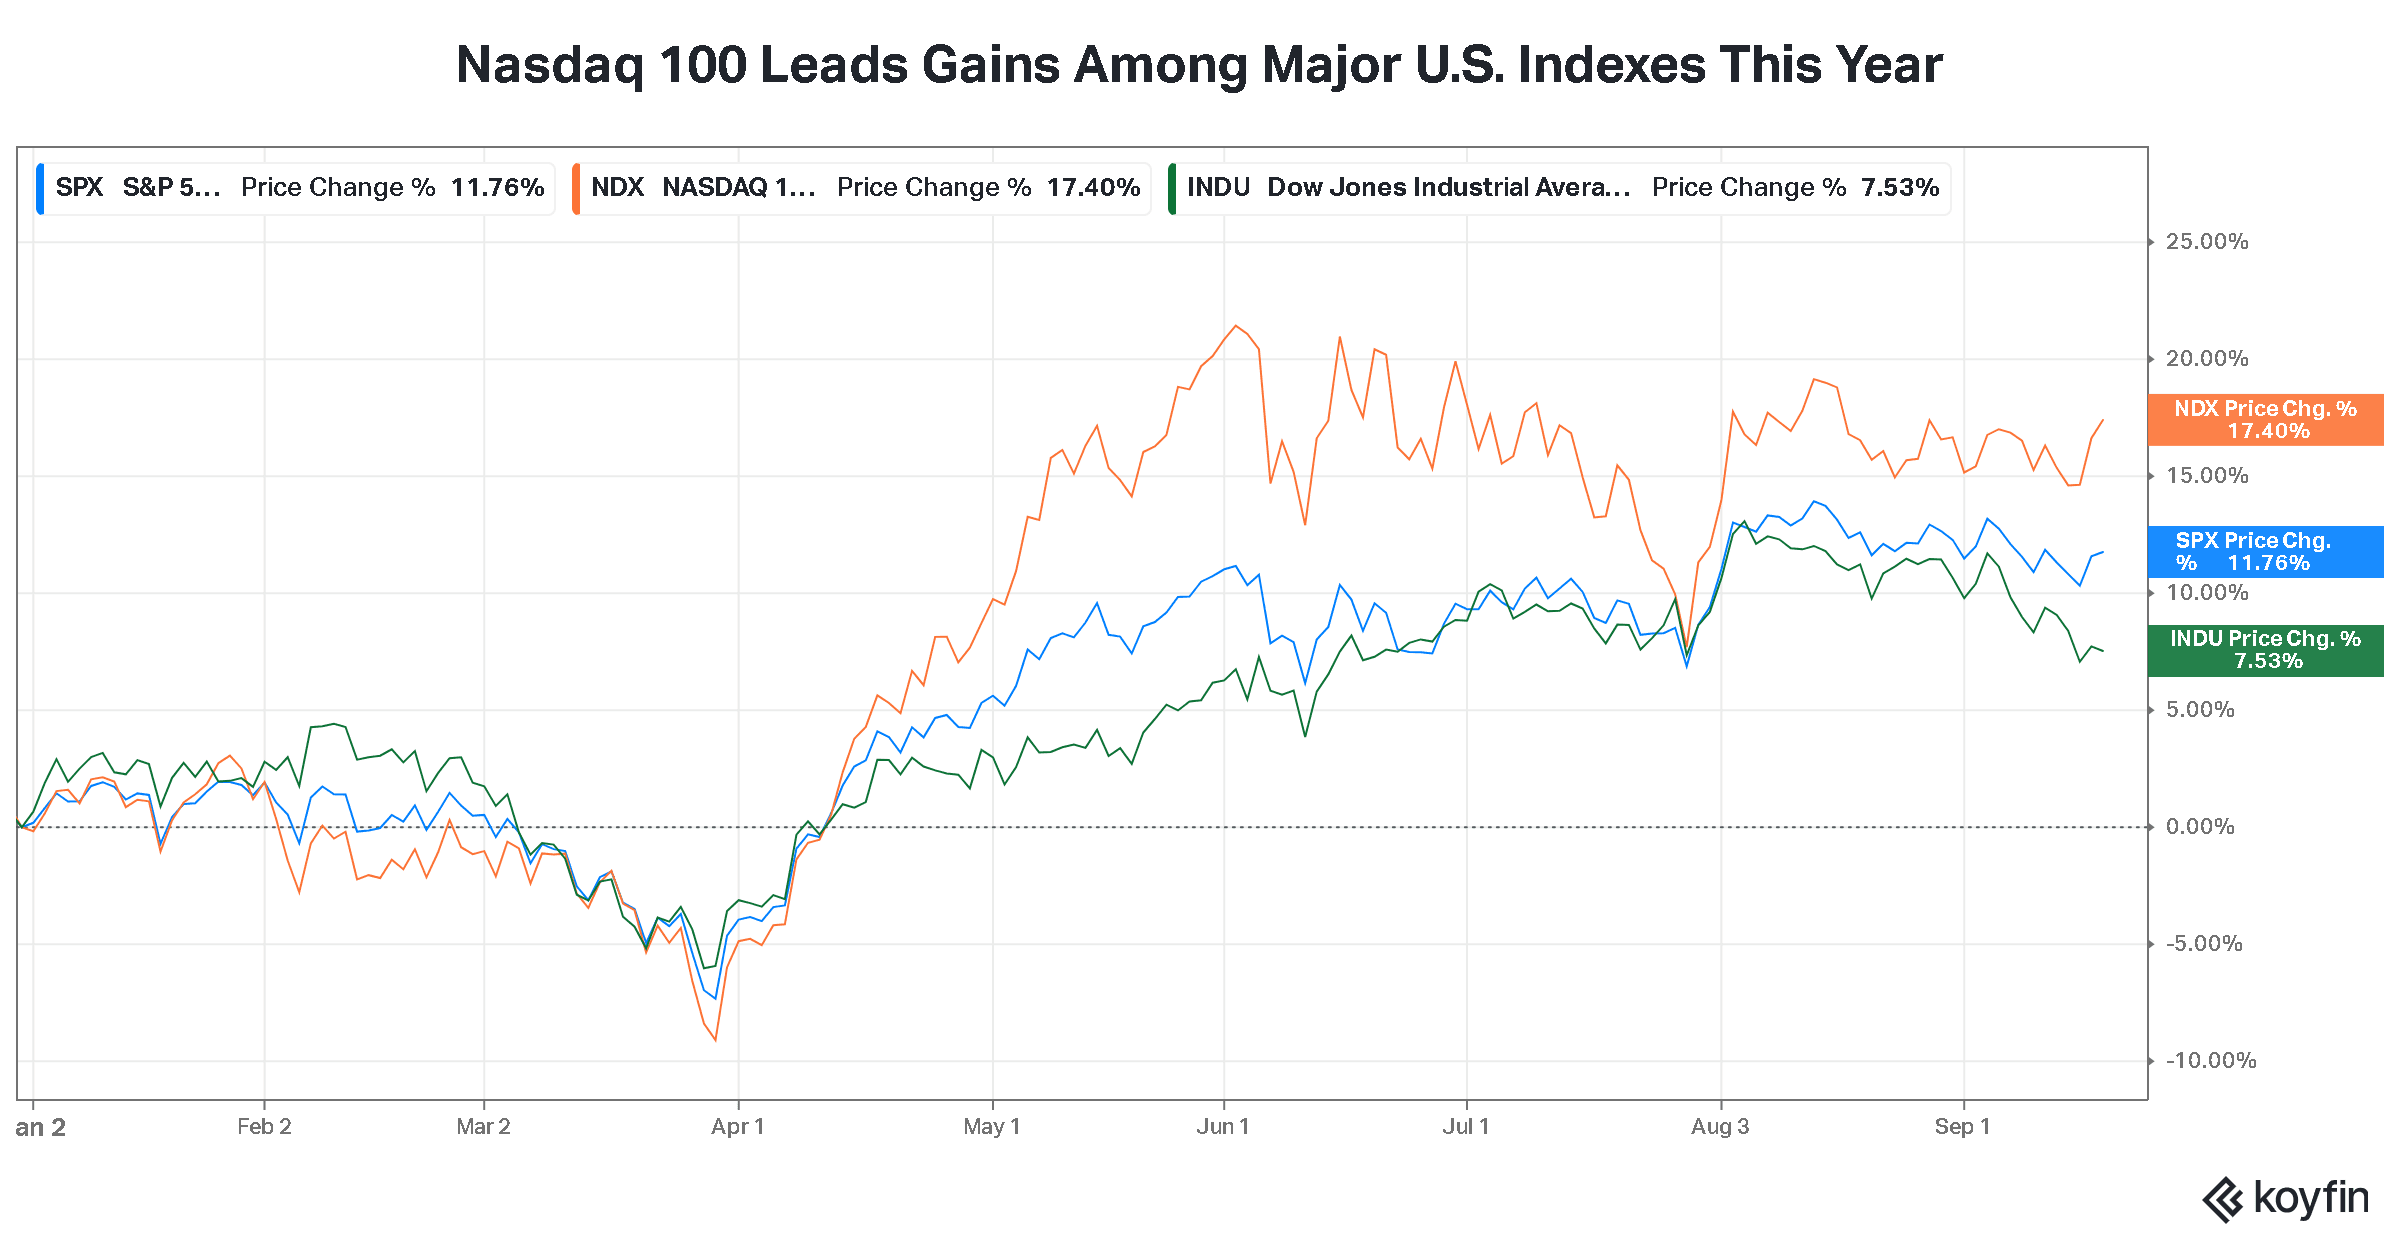
Last week, the major indexes told a split story. The Dow finished the week down 1.69% at 51,681, the S&P 500 was essentially flat at 7,650.50, and the Nasdaq Composite actually gained 0.72% on a late rebound in semiconductor shares.
In pre-market trading on Monday, the indexes edged higher. The SPDR S&P 500 ETF (SPY) was up 0.62%, the SPDR Dow Jones Industrial Average ETF (DIA) gained 0.65%, and the Nasdaq-100 tracking Invesco QQQ Trust (QQQ) climbed 0.86%. On Stocktwits, retail sentiment around SPY improved to ‘bearish’ from ‘extremely bearish’ over the past week.
Read also: Dan Ives Says AI Leaders Can't 'Stop The Elevator' With Meta In The 'Ferrari Left Lane' As AI Race Accelerates
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
