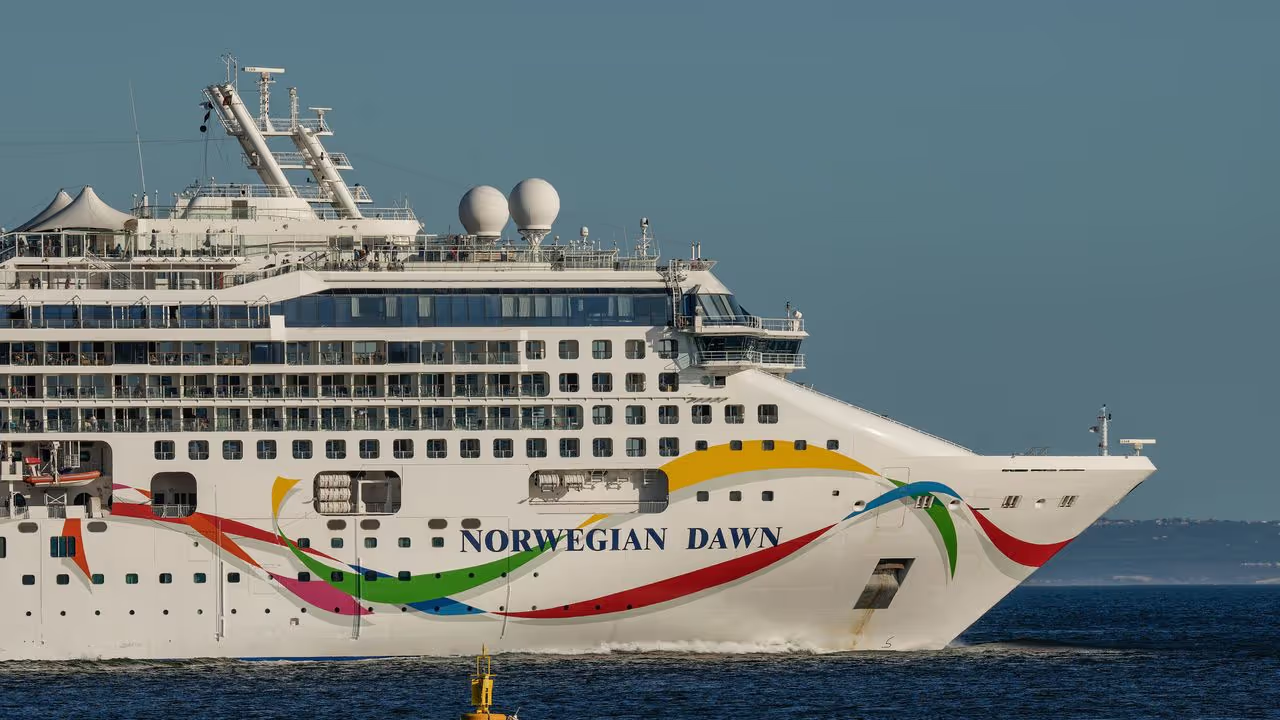
Norwegian Cruise Line received a slew of price target hikes following its third-quarter earnings beat.
- Freedom Broker upgraded Norwegian Cruise Line to ‘Buy’ and raised its price target to $22.
- Wells Fargo also raised its price target to $22, citing stronger passenger occupancy.
- Goldman Sachs pointed to improved financial strength and 2027 yield growth prospects.
Norwegian Cruise Line Holdings (NCLH) stock ticked higher overnight as multiple Wall Street analysts raised their price targets following stronger-than-expected third-quarter (Q3) results. Freedom Broker upgraded the stock to ‘Buy,’ while Wells Fargo and Stifel also lifted their targets. Improving bookings, stronger pricing, a reduced risk of equity issuance, and $100 million in additional cost savings boosted optimism.
Norwegian Cruise Line stock traded over 1% higher overnight, ahead of Monday. Last week’s 16% gain was the stock’s best performance in over two years.
Analysts See Room For NCLH’s Further Gains
Freedom Broker upgraded Norwegian Cruise Line to ‘Buy’ from ‘Hold’ and raised its price target to $22 from $20, implying 25% upside from the stock’s last closing price. The analyst said the cruise operator surpassed expectations on important operating measures in Q3. Revenue and adjusted earnings also came in above the firm's estimates.
Norwegian reported $2.9 billion in Q3 revenue with adjusted earnings of $1.12 per share. Both surpassed the analysts’ consensus estimates of $2.8 billion and $0.94, respectively, according to Fiscal.ai. Better last-minute bookings and higher onboard passenger spending helped the company outperform expectations. Lower operating expenses also supported profit.
Norwegian also raised its full-year 2026 adjusted EBITDA forecast to around $2.55 billion. The company now expects adjusted earnings of about $1.70 per share and adjusted net income of about $789 million.
Wells Fargo increased its price target to $22 from $18 while maintaining an ‘Overweight’ rating. The firm highlighted stronger-than-anticipated passenger occupancy as a key factor behind the quarterly performance.
Improving Bookings And Cost Savings Support Norwegian Cruise Line Outlook
Goldman Sachs raised its price target to $16 from $14 but maintained a ‘Neutral’ rating. The firm's revised outlook followed a 13% rally in Norwegian shares, supported by better 2027 net yield guidance of 1%-2% and improved financial flexibility. The analyst said the company's strengthened balance sheet eases concerns about a potential share offering.
The company said it plans to generate another $100 million in annual savings through changes to guest and crew air travel arrangements and adjustments to promotional activities. The initiatives will gradually take effect through 2028.
Last week, Norwegian Cruise Line also appointed Chief Strategy Officer Meghan Montana as CFO, effective Jan. 1, 2027, succeeding Mark A. Kempa. Stifel analyst Steven Wieczynski also raised his price target on Norwegian Cruise Line to $24 from $22, maintaining a ‘Buy’ rating.
NCLH Stock: Retail View
On Stocktwits, retail sentiment around the stock remained ‘bullish’. The stock saw a 20% increase in message volume over the past week, with a 0.2% gain in watchers.
NCLH stock has declined 21% year-to-date.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<