
- Southwest had $8.4 billion in Q3 revenue as new seating options and basic economy fares helped increase income.
- Morningstar expects Southwest’s costs to rise and growth to slow in 2027, tripping the fair value to $34.40.
- Southwest cut its 2026 earnings guidance as rising fuel costs outweighed higher fares.
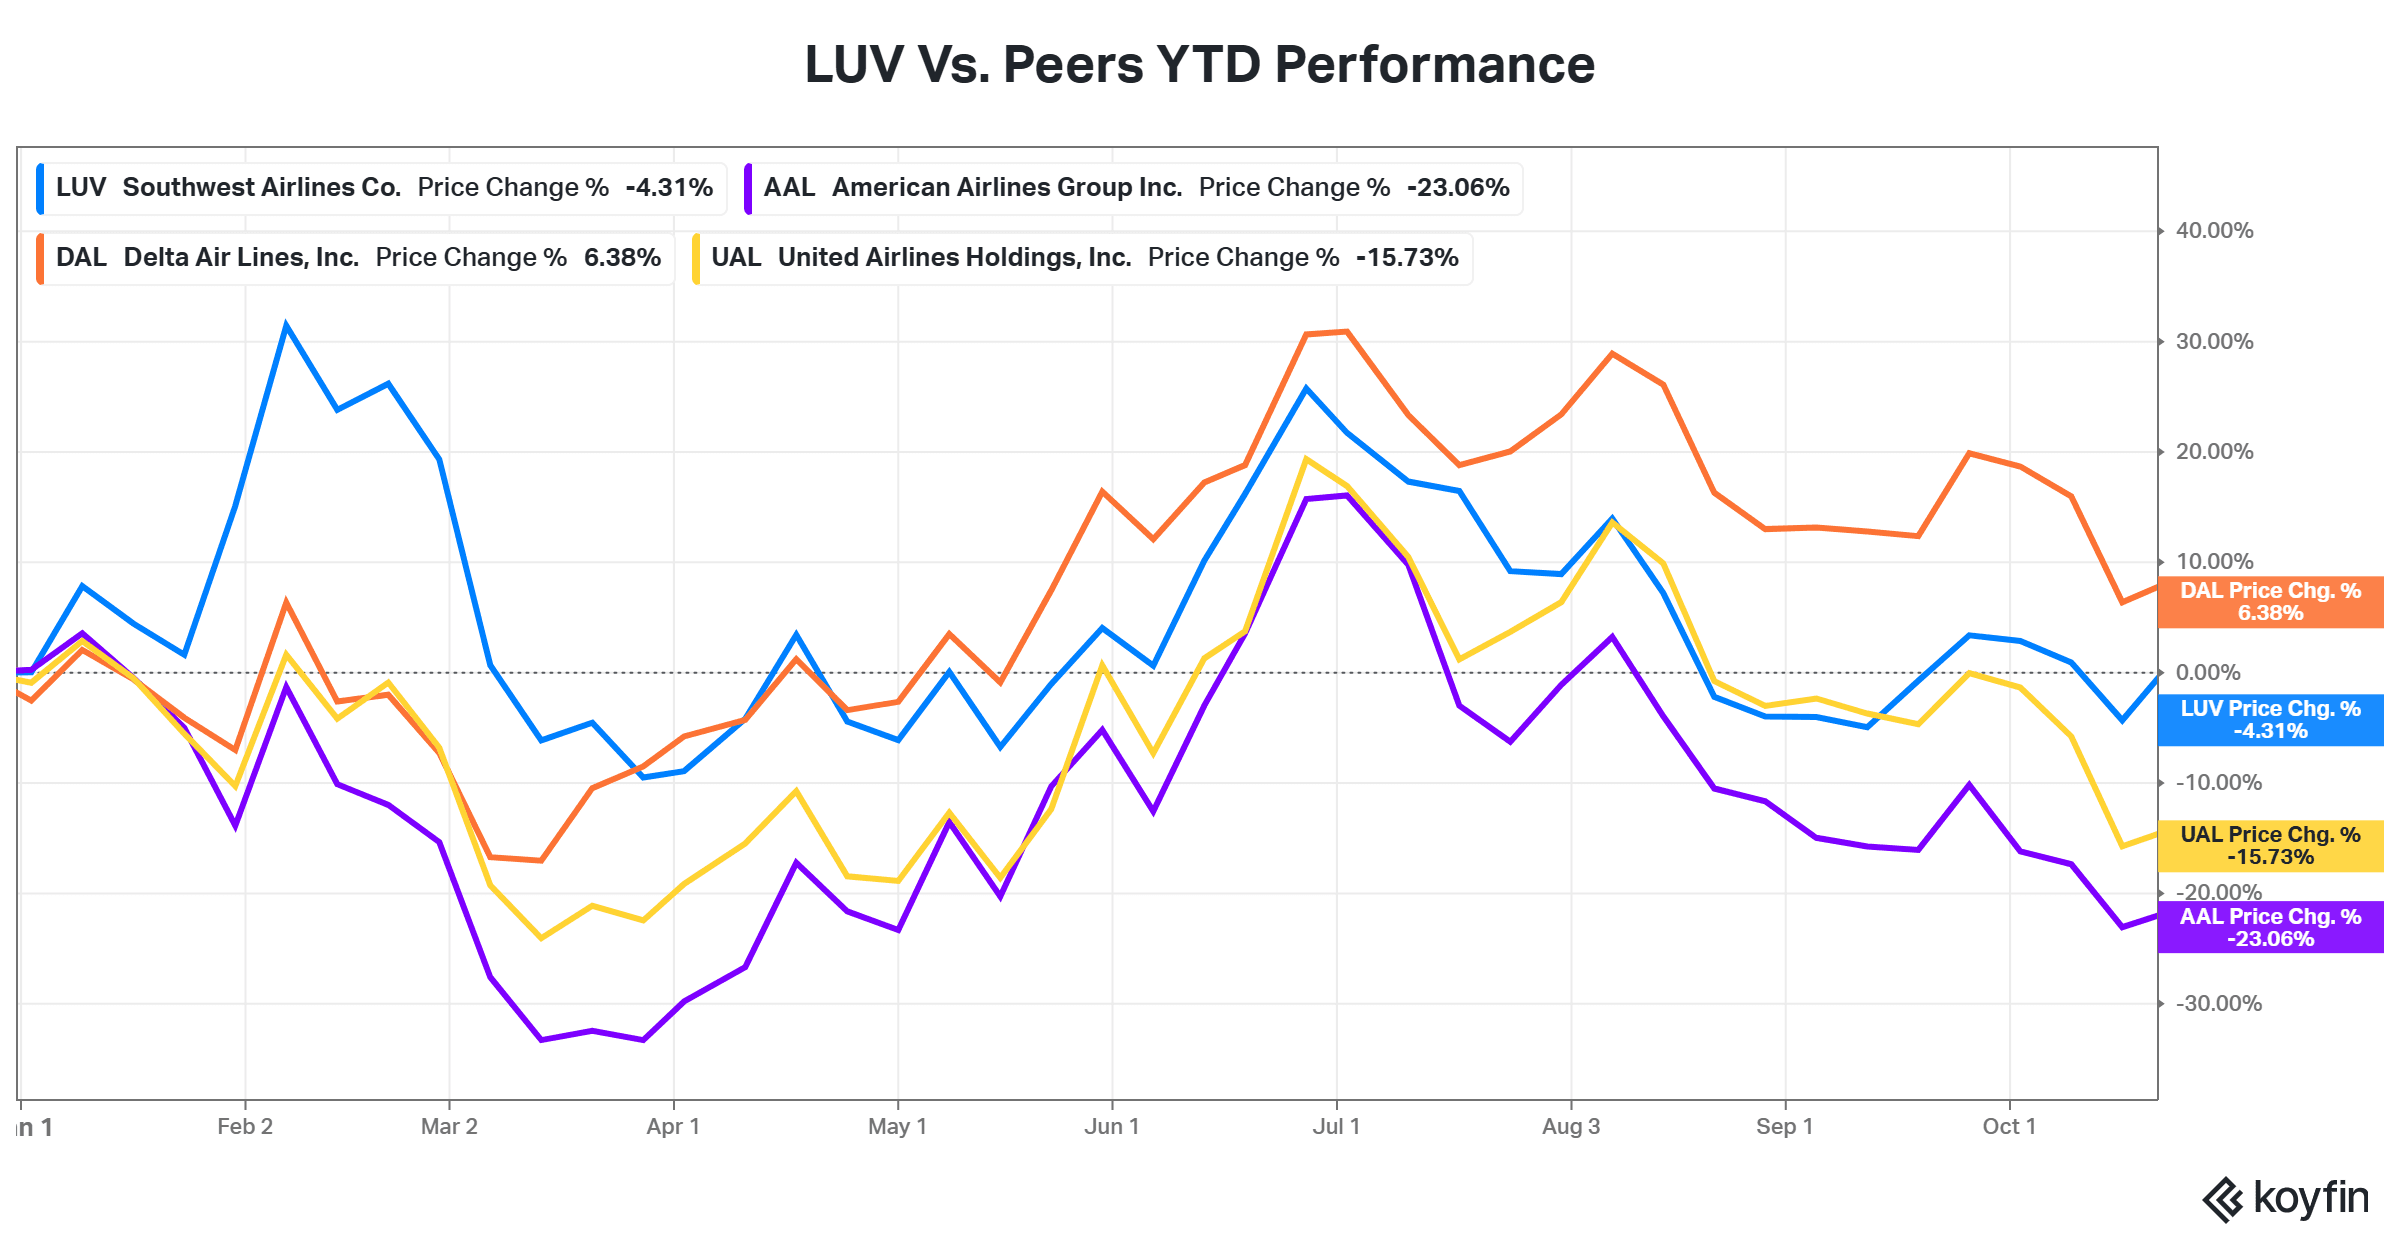
Southwest Airlines Co. (LUV) stock wrapped up its best week since June as investors cheered its pricing makeover and premium seating push. But Morningstar sees a reality check ahead, saying shares are 22% overvalued. The analyst lowered its fair value estimate to $34.40, citing rising costs, competition and slower growth expectations for 2027.
Southwest Airlines stock traded 1% lower overnight, ahead of Monday. The stock gained 5.7% last week, logging its best since June.
Southwest’s New Pricing Strategy Could Lift Revenue
In the fiscal third quarter (Q3) 2026, the airline’s operating income was $379 million on $8.4 billion in revenue, matching Morningstar analyst Nicolas Owens' expectations. Southwest's latest pricing changes continued to lift revenue per available passenger seat above the analyst's estimates, despite fewer seats being filled.
Southwest introduced assigned seating and extra legroom in January, charging more for comfortable seats. In late 2025, it also launched a cheaper basic fare that excludes two free checked bags, similar to budget tickets offered by other airlines.
According to the analyst, these changes could help Southwest attract customers who previously went with full-service airlines while allowing it to earn more from passengers willing to pay for additional benefits. Morningstar expects strong leisure travel demand and a recovery in business trips to support higher passenger revenue per mile.
Higher Costs Could Limit Southwest’s Profit Growth
Despite the potential revenue gains, Morningstar expects Southwest to face high expenses and slower growth in 2027.
The firm estimates an average operating margin of 7.8%, well below Southwest's 16.4% average between 2015 and 2019. Higher labor expenses, renewed staffing needs and updated labor agreements have weakened the cost advantages the airline previously enjoyed, said Owens. Southwest also plans to spend about $3 billion on capital investments in 2026, largely as it prepares to receive dozens of Boeing 737 MAX aircraft.
Competition Remains A Long-Term Challenge
Morningstar said the airline industry remains exposed to fuel-price swings, labor inflation, economic downturns and aggressive ticket-price competition.
Southwest faces pressure from established carriers such as Delta Air Lines Inc. (DAL) and United Airlines Holdings Inc. (UAL), along with lower-cost competitors. Boeing's delayed aircraft deliveries have also complicated Southwest's expansion plans. The analyst reduced the airline's fair value estimate to $34.40 per share from $35.20, citing higher operating costs and a less favorable growth outlook.
“Shares trade 22% above our revised fair value estimate, which we interpret as investors
anticipating Southwest's new recipe may boost its yield indefinitely”, said Owens.
The analyst expects competition to eventually limit those gains and bring yields closer to industry levels.
Southwest Airlines cut its 2026 profit outlook last week as soaring fuel costs offset gains from higher fares. The airline now sees adjusted earnings of $2.60-$2.85 per share, below its previous $3.25-$4.25 outlook. Fuel costs rose to $3.92 per gallon in Q3, above the earlier estimate of $3.70 - $3.75, impacting adjusted earnings per share by $1.08.
LUV Stock: Retail View
On Stocktwits, retail sentiment around the stock remained ‘bearish’.
LUV stock has gained 29% over the past twelve months.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
