
William Blair called the IPO valuation “very reasonable” and said a higher sales multiple could put shares at $130 to $150.
- Needham put Anthropic in the same league as Amazon, Google and Microsoft.
- Melius set the highest target at $155 over two years, nearly 60% above the debut close.
- NYU Stern’s Aswath Damodaran valued Anthropic at about $76, citing higher data center costs and regulatory pressure.
Shares of Anthropic PBC (ANT) jumped 17% in their Wall Street debut on Thursday as analysts cast the Claude maker as a rare growth opportunity in the same league as Amazon and Google, with the most bullish target pointing to nearly 60% more upside.
ANT stock opened at $111.50 on Thursday before settling at $97.17, well above its $83 offer price even on a day the Nasdaq Composite fell over 2%.
The $81.34 billion offering overtook SpaceX’s June listing as the largest IPO on record. Alongside a separate $26 billion private placement, Anthropic expected to receive $104.8 billion after fees and expenses, giving it cash to fund the next generation of Claude.
Analyst Puts Anthropic In Big Tech’s League
Needham initiated coverage with a ‘Buy’ rating and a $150 target, implying 54% upside from current levels. “Growth opportunities like ANT rarely come along but we think history puts ANT in the same dominant bucket as fellow tech titans AMZN, GOOG, and MSFT,” the firm said.
Needham estimates that AI could address a tenth of the $56 trillion global labor market. Anthropic already earns more when customers put Claude to work on more tasks. Usage-based charges accounted for 79% of revenue in the first nine months of 2026, according to its prospectus.
Needham expects revenue to grow more than 150% in fiscal 2027 and believes Claude’s brand and Anthropic’s scale could drive operating margins above 35% over time, even as the company spends tens of billions of dollars a year training models.
William Blair also expects Anthropic to win a larger share of corporate budgets. “We think AI is a generational shift in the tech landscape, and Anthropic is leading the charge in developing AI with a select handful of other companies,” the firm said.
William Blair initiated coverage at ‘Outperform,’ calling the IPO valuation “very reasonable” at nine times estimated 2027 sales. It said a multiple of 17 to 20 times sales could put the stock at $130 to $150, or 34% to 54% above its debut close.
What It Would Take ANT To Hit $155
Melius initiated coverage at ‘Buy’ with a two-year target of $155, implying nearly 60% upside from Anthropic’s $97.17 debut close. The firm expects customers to use Claude more often and buy more products as the cost per task falls. Over time, it sees earnings power above $5 a share and operating margins above 30%.
Melius also pointed to Anthropic’s flexibility. Claude can run on chips from Nvidia and AMD, as well as Amazon’s Trainium and Google’s TPUs. “If the model scales accordingly, shares could trade at a nice premium to hyperscalers given its outsized growth and high gross margins,” the firm said.
Additionally, Wolfe Research initiated coverage at ‘Outperform’ with a $135 target, implying 39% upside from the same close.
Cathie Wood Sees Edge In Unreleased Models
Citizens pointed to Claude’s role in building its own successor as a reason for its ‘Market Outperform’ rating. “Over 90% of the contributions to our codebase in September 2026 were written by Claude,” Anthropic said in its prospectus. Citizens’ $125 target implies 28.6% upside from the debut close.
Meanwhile, ARK Investment Management CEO Cathie Wood sees an edge in the models Anthropic keeps in-house. She estimates AI training costs are falling about 75% a year, allowing Anthropic to train better models while giving rivals fewer chances to learn from its most advanced work. Wood compared the potential lead over open-weight models to a decade of progress at the slower pace of earlier chip advances. “It would be like being 10 years ahead in that world,” she said.
ANT Valuations Below Debut Close
Morningstar kept its fair value estimate at $92, about 5% below Thursday’s close, with a ‘3-star’ rating. It sees Claude’s meeting and spreadsheet tools as an early test of whether businesses will shift spending from existing software to Anthropic as Claude takes on more valuable work. With about $900 billion in computing commitments, Morningstar believes Anthropic’s cash and IPO proceeds can cover its near-term bills even if sales stop growing. A drop in sales would be tougher. “I think declines in revenue would be quite difficult for the company to manage,” Morningstar said.
Similarly, NYU Stern professor Aswath Damodaran valued Anthropic at about $76 a share after accounting for employee options, which is 22% below its debut close. His estimate assumes higher data center construction costs and tighter regulation will weigh on profits.
How Do Retail Traders Feel About ANT?
On Stocktwits, retail sentiment around ANT was ‘extremely bullish’ amid a 885% surge in 24-hour message volumes.
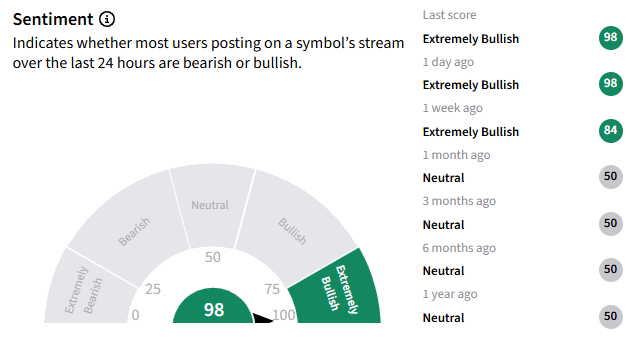
One user said they would buy at $65. Another user said they would wait for $75. A separate user said they were sticking with Nvidia, Intel and SpaceX, adding, “Long-term holding has always been my strategy, and I’m not changing it now.”
View this Stocktwits post
Most voters in a Stocktwits poll sat out Anthropic’s debut, with 68% of the 17,500 votes going to “Avoiding it.” Another 16% chose to buy for the long term, 9% favored a short-term trade and 7% planned to trade around the volatility.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<









