
According to TheFly, Piper Sandler believes that Anthropic’s commitment could drastically alter Akamai’s financial profile, with Cloud Infrastructure Services potentially surpassing Security by late 2028.
- Piper Sandler raised its target to $158 from $125, saying the Anthropic deal alone implies about $1.66 billion in annual recurring revenue.
- Evercore ISI sees deal profitability skewing toward the high end of Akamai’s prior operating-margin framework.
- BofA highlighted another $9 billion of potential expansion for Akamai.
Akamai Technologies Inc. (AKAM) shares were in the spotlight on Friday as analysts argued its expanded Anthropic agreement could materially change the company’s growth and profitability profile.
According to TheFly, Piper Sandler delivered the strongest reassessment, raising its price target to $158 from $125 and maintaining an ‘Overweight’ rating on AKAM stock.
The firm said the deal’s magnitude is impressive and “drastically changes the financial profile,” potentially shifting Akamai from a “value” asset toward a “hypergrowth” one.
At the time of this writing, AKAM stock was up around 19% and was one of the top-trending tickers on Stocktwits.
Piper Sees Cloud Overtaking Security
Piper estimates the $11.6 billion commitment implies about $1.66 billion in annual recurring revenue at full run rate, roughly four times Cloud Infrastructure Services’ annual recurring revenue at the end of the second quarter, according to The Fly.
The firm expects Akamai to reach that run rate by the fourth quarter of 2028. At the current pace, Piper said Cloud Infrastructure Services could surpass Akamai’s Security business by no later than then.
Piper also said it does not believe Akamai is finished securing large deals for central processing unit (CPU) or graphics processing unit (GPU) workloads.
BofA, Evercore See More Upside To The Economics
BofA raised its target to $185 from $175 and maintained a ‘Buy’ rating on the stock. The firm expects Anthropic revenue to ramp through fiscal 2027 and 2028 before reaching about $1.7 billion annually thereafter and highlighted that Akamai laid out another $9 billion expansion opportunity beyond the initial commitment, per TheFly.
Evercore ISI reiterated an ‘Outperform’ rating and $175 target. The firm said CPU workloads carry higher revenue per megawatt and cash gross margins than GPU workloads and expects profitability to skew toward the high end of management’s prior low-to-mid-20% to low-30% operating-margin framework.
Evercore said the agreement takes Akamai’s Cloud Infrastructure Services total contract value to roughly $14.4 billion.
JPMorgan also raised AKAM's price target to $167 from $158 and kept a ‘Neutral’ rating on the shares. Akamai's large deal with Anthropic affirms the differentiation of its platform and ability to drive favorable economics on capacity, the firm stated, per TheFly note.
Anthropic Commitment Could Reach About $20 Billion
Akamai said Anthropic committed $11.6 billion over seven years to dedicated cloud capacity and related services to support its growing CPU workloads. The agreement expands an existing relationship between the companies and adds to more than $2.8 billion in other multi-year Cloud Infrastructure Services commitments that Akamai previously announced this year.
The initial contract could expand by another $9 billion, taking the potential relationship to roughly $20 billion. That additional amount is not currently committed; each incremental $3 billion in cloud services would require mutually agreed-upon terms.
Akamai expects about $5.5 billion in capital expenditure to support the initial contract, with revenue beginning to ramp in 2027 and reaching full run rate by the end of 2028.
Retail Sentiment Around AKAM Stock
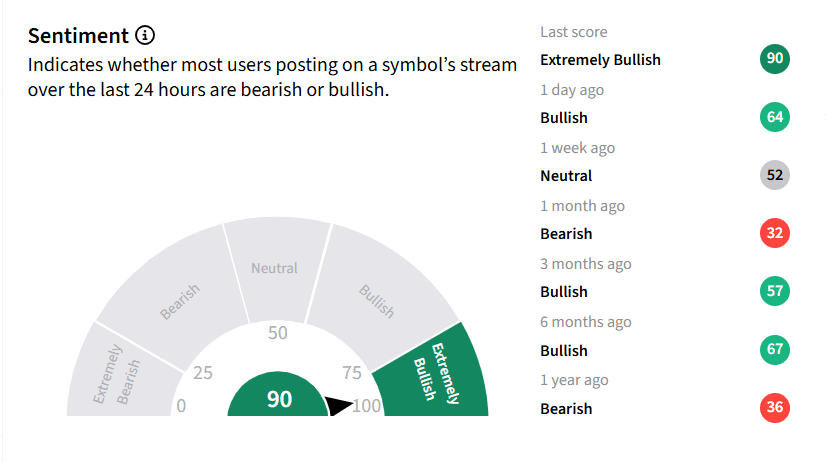
On Stocktwits, retail investor sentiment surrounding AKAM stock turned ‘extremely bullish’ amid extremely high message volume.
So far in 2026, AKAM stock has rallied nearly 30%. In comparison, the iShares AI Innovation and Tech Active ETF (BAI) and the First Trust NASDAQ Cybersecurity ETF (CIBR), which hold the stock, have risen 39% and 46%, respectively, over the same period.
See Also: Meta’s AI Spending Shows ‘Clearest Signs’ Of Payoff Yet, TD Cowen Says — Muse Revenue Seen At $27B By 2031
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
