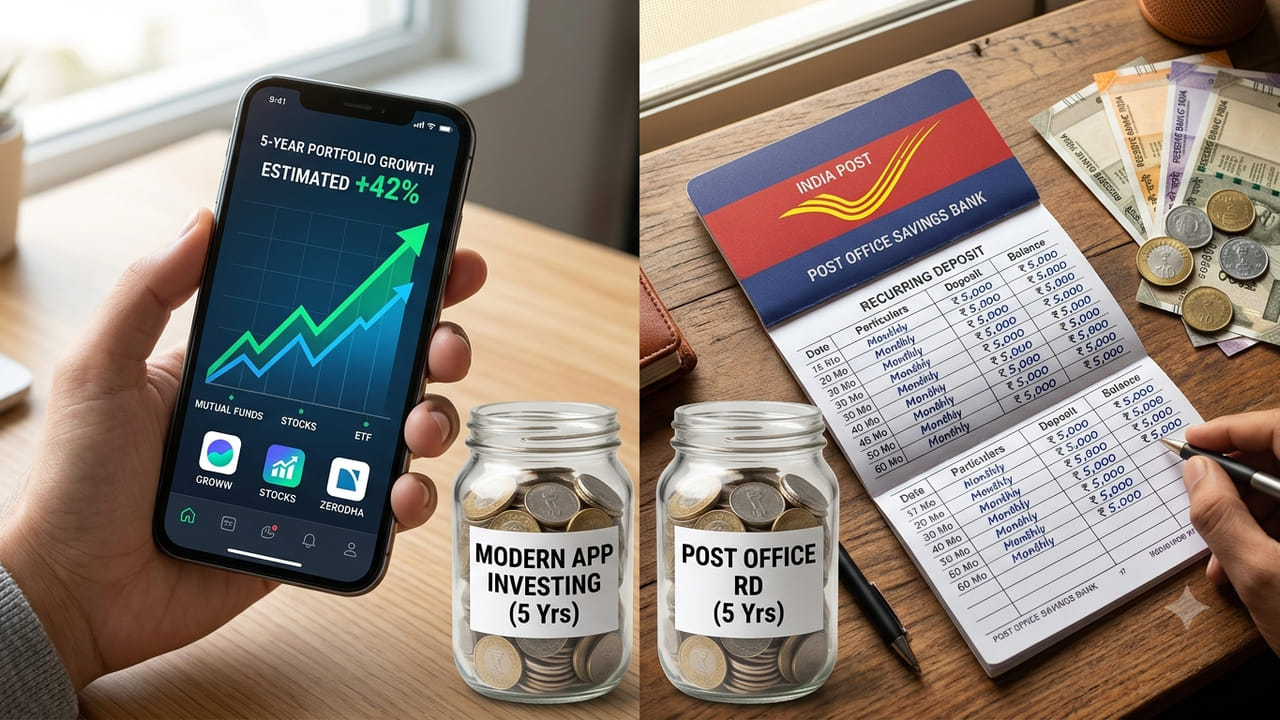
Investing Rs 10,000 monthly in a mutual fund SIP or a Post Office RD offers different potential returns. While SIPs may yield higher market-linked gains, RDs provide fixed, predictable interest. Choose based on your risk tolerance and financial goals.
By investing Rs 10,000 each month, it is possible to build up a sizeable corpus of savings over a period of time. But how much you end up with depends on where you invest your money. For investors comparing a Systematic Investment Plan (SIP) of a mutual fund with a Post Office Recurring Deposit (RD), the choice usually boils down to potential return, risk and predictability.
Both options allow people to invest a fixed sum each month, but they work differently. Market-linked returns The mutual fund SIPs are market-linked and hence, the returns could be higher but there is no guaranty. Meanwhile, a Post Office RD provides fixed interest rates and predictable returns as per the scheme’s rules.
So, what happens if you invest Rs 10,000 every month in either option for five years? Here is a look at the estimated numbers.
Related Articles

Rs 10,000 Monthly Investment for 5 Years: The Calculation
To compare this, let’s assume an investor invests Rs 10,000 every month for a period of 60 months. The total amount invested over five years would be Rs 6 lakh. For the mutual fund SIP, an annualised return of 12% has been considered for illustration. The Post Office RD calculation uses an annual interest rate of 6.7%, the rate applicable for the October-December 2026 quarter. The RD interest is compounded quarterly.
Under these assumptions the estimated maturity values are:
Particulars — Mutual Fund SIP — Post Office RD
Monthly investment — Rs 10,000 ---- Rs 10,000
Investment period — 5 years — 5 years
Total investment — Rs 6,00,000 ---- Rs 6,00,000
Assumed annual return/interest: 12% — 6.7%
Estimated maturity amount — Rs 8,16,697 ---- Rs 7,13,700
Estimated earnings — Rs 2,16,697 ---- Rs 1,13,700
The calculation shows that the SIP can gain an additional amount of around Rs 1.03 lakh as compared to the Post Office RD in a span of five years. However, the difference is based on an assumed mutual fund return and should not be treated as a guaranteed outcome.
How Much Can a Rs 10,000 SIP Grow to in 5 Years?
So, SIP of Rs 10,000 per month will make you invest a total of Rs 6 lakh in 60 months. If the mutual fund delivers an annualised return of 12%, the investment could grow to approximately Rs 8.17 lakh.
This would translate into estimated gains of around Rs 2.17 lakh over the invested amount.
But mutual funds are market linked investment. Performance depends on the market conditions and the underlying assets of the scheme. Actual returns could be higher or lower than the assumed rate and investors could lose money.
So, the 12% figure is just an example to understand the possible growth of the investment. It is not a promise of returns.
How Much Will Rs 10,000 in a Post Office RD Earn?
In Post Office Recurring Deposit Scheme, a person can deposit a fixed amount every month for a period of 5 years. It offers a more predictable savings route compared with market-linked investments.
For the calculation an interest rate of 6.7% p.a. has been applied. At this rate, if you invest Rs 10,000 every month for five years, you will have deposited Rs 6 lakh in total. The estimated maturity amount would be around Rs 7.14 lakh, including interest earnings of approximately Rs 1.14 lakh.
Unlike mutual fund returns the RD interest rate is fixed for the account under the applicable scheme rules. This makes it easier for investors to estimate their proceeds at maturity. Interest payable may be affected by early closure and is subject to scheme rules.
SIP vs Post Office RD: Which One Should You Choose?
The two investment options cater to different financial needs and the choice depends on the investor’s risk appetite, objectives and investment horizon.
If you are okay with market volatility and want to earn higher returns, then you could go for a mutual fund SIP. But there is no guaranty that a fund will give 12 per cent annualized returns over five years. The value of the investment can fluctuate, and capital loss is possible.
Post Office RD can be ideal for those who are looking for predictable returns and they do not want to be exposed to market volatility. The returns may be lower than what you may expect from a successful mutual fund investment but you can easily calculate the maturity amount because of the fixed rate of interest.
At the end of the day, there isn't one size fits all option for every investor. Anyone considering either path should consider their financial objectives, their risk tolerance and their need for liquidity before making any investments. You should also talk to a qualified financial adviser to make a well-informed decision.