
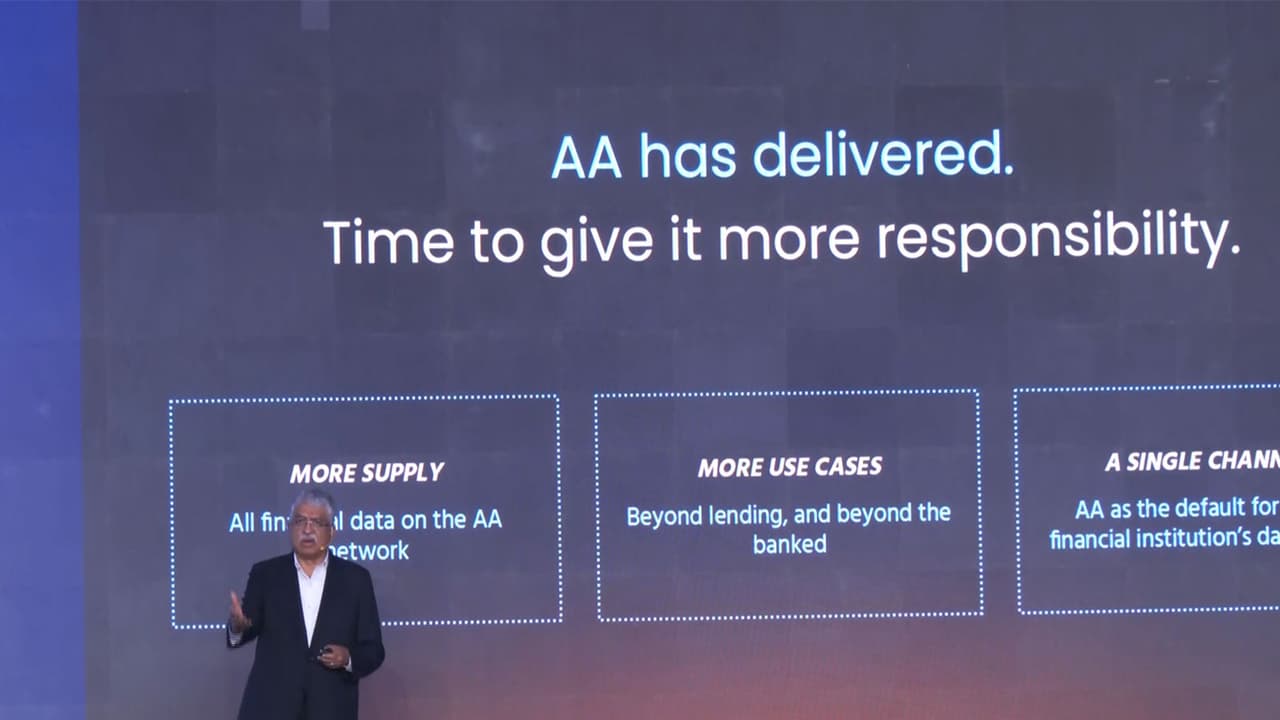
Infosys Chairman Nandan Nilekani said India's Account Aggregator framework can expand credit for micro-entrepreneurs by enabling them to use their financial data, fostering domestic growth and job creation at scale through small businesses.
Expanding Credit Access for Entrepreneurs
Infosys Chairman and Co-founder Nandan Nilekani said India's Account Aggregator (AA) framework can help expand access to credit and financial services for micro-entrepreneurs, gig workers and other underserved sections by enabling them to use their financial data.
Speaking at SamvAAd 2026-India Open Finance Summit, Nilekani said empowering small businesses with capital and access to digital markets is key to driving domestic economic growth and creating jobs.
“Effectively, what we are doing is that, through the AA system, we are unlocking data for everyone. We are making sure that everybody can use it for a variety of products. Through ONDC, we're unlocking market access, so small businesses can get market access,” Nilekani said.
A Vision for Domestic Growth
He said the focus should be on enabling millions of entrepreneurs to grow their businesses and generate employment, particularly at a time when automation and global economic shifts are changing the nature of work.
“The real thing we need to focus on is how do we create domestic growth by having millions of entrepreneurs, unleashing their capability, simplifying things for them and making sure that each of them creates jobs. And AA is part of this larger vision of enabling jobs at scale through small businesses,” he said.
The Scale of India's Digital Public Infrastructure
Highlighting the adoption of India's digital public infrastructure, Nilekani said Aadhaar records around 90 million authentications and 15 million e-KYC procedures daily, covering 95 per cent of adult citizens. The Unified Payments Interface (UPI) processes around 750 million transactions daily and has 550 million monthly active users, reaching about half of the adult population.
The AA ecosystem, meanwhile, handles around one million consents and 12 million data pulls daily, covering 20 per cent of adults. Nilekani said the aim is to increase its reach to more than 50 per cent of the adult population over the next two to three years.
Monetizing Data for Inclusive Lending
He said the framework could help people without significant assets access formal credit by allowing lenders to assess their financial data and income flows.
“Historically, lending in India was based on what assets you own. But a person does not own any assets. How do they get access to credit? They get access to credit by monetizing the data streams. And that's what we do here. So it's a very inclusive idea,” he said.
Nilekani said bringing self-employed individuals, nano enterprises, self-help groups and street vendors into the formal credit system would require the use of multiple data sources, including GST records, current accounts and livelihood-related information.
He added that integrating more sources, such as income tax records, Employees' Provident Fund Organisation (EPFO) data, small savings schemes and utility payments, could further expand the framework's reach.
“If you can increase the category of people who use AA and the use cases you get, you're going to create a dramatic explosion in the AA system and that should be our endeavour so that every use case, everything is using AA for every category of people,” Nilekani said.
Ensuring Ecosystem Sustainability
He also highlighted steps taken by the Reserve Bank of India to improve interoperability among account aggregators, establish formal self-regulatory governance through Sahamati and develop sustainable fee models for ecosystem participants. (ANI)
(Except for the headline, this story has not been edited by Asianet Newsable English staff and is published from a syndicated feed.)