
Prices per terabyte rose 28%, with further pricing upside expected over three to four quarters.
- Western Digital sees storage demand from its seven biggest customers extending into 2031.
- Revenue jumped 55% and adjusted earnings surged 161%, while second-quarter guidance also topped expectations.
- Higher capital spending will fund technology upgrades without expanding drive unit capacity.
Western Digital’s (WDC) strong earnings and outlook failed to halt a 7% after-hours slide on Thursday, even as Goldman Sachs saw reasons for shares to rise and the company outlined demand visibility extending into 2031.
WDC shares fell 6% to $354.19 on Thursday, snapping a three-session winning streak. The stock is still up about 7% for the week, on track for its strongest weekly gain in more than two months.
Goldman maintained a 'Neutral' rating and $615 price target, implying a 74% upside from current levels. The firm said the strong quarter and very strong guidance should support gains, while noting investor expectations were elevated after favorable HDD pricing and constructive company commentary during the quarter.
Top Customers Plan Storage Needs Into 2031
CEO Irving Tan said Western Digital had visibility into storage demand from its seven biggest customers through 2030 and 2031. “In fact, we see quarter after quarter, the demand signal actually increasing over time,” Tan said.
“There has not been any diminishing in demand, and we do not see the gap in supply or demand that exists today diminishing in the near term as well,” he added.
Product transitions are expected to accelerate shipment growth. When asked by UBS analyst Timothy Arcuri whether exabyte growth could reach about 35% in six quarters, compared with the latest 22%, CFO Kris Sennesael said: “We only guide in one quarter at a time, but you're thinking about it in the right direction.”
WDC Q1 Review
Western Digital beat first-quarter expectations as revenue jumped 55% from a year ago to $4.38 billion and adjusted earnings surged 161% to $4.64 a share. Analysts had forecast revenue of $4.15 billion and earnings of $4.10 a share.
The second-quarter outlook cleared Wall Street’s bar, too. The company projected revenue of $5 billion to $5.2 billion and adjusted EPS of $5.60-$6.00, versus consensus estimates of $4.57 billion and $4.82, respectively. Even the low end of each range topped expectations.
Adjusted gross margin is expected to climb to 60%-61%, from 58.1%. Western Digital also generated $1.4 billion in quarterly free cash flow, returned $1.1 billion to shareholders and raised its quarterly dividend 17% to $0.175 per share.
CFO Sees Pricing Runway For Another 3-4 Quarters
Selling prices per terabyte rose 28% from the previous year, up from 18% the prior quarter. Responding to Barclays analyst Tom O’Malley’s question about sustainability, CFO Kris Sennesael signaled further opportunities were open.
“But for the next three, four quarters, there is definitely further room to expand our ASP per terabyte year-over-year growth,” he said. The company cited contractual price increases, agreement renewals and stronger spot pricing. However, its extended demand visibility does not mean all future volume and pricing are secured under long-term agreements.
“The further you go out, the less of it is covered under LTAs [long-term agreements], and for sure, under pricing component of the LTAs,” Sennesael said.
Higher Spending Targets Next Storage Wave
Western Digital expects capex modestly above 4%-6% of revenue over the next two years, while targeting that range on a five-year average. “The CapEx is going to head and media and factory automation and not to expanding our unit capacity,” Sennesael said.
The spending supports heat-assisted magnetic recording (HAMR) production and higher-capacity drives, with initial HAMR volume shipments scheduled for the first half of calendar 2027. When asked about rival expansion, Tan said: “Other organizations that don't have that degree of vertical integration, I would say, will have a harder time being able to reach the same levels of growth that we are seeing.”
Western Digital is sampling high-bandwidth drives for AI inference key-value (KV) cache workloads and video streaming, with commercial pricing still under development.
“For WD, this creates an opportunity that extends well beyond the initial AI infrastructure build-out,” Tan said. “As AI scales, data creation and associated storage requirements will accelerate and compound.”
How Do Retail Traders Feel About WDC?
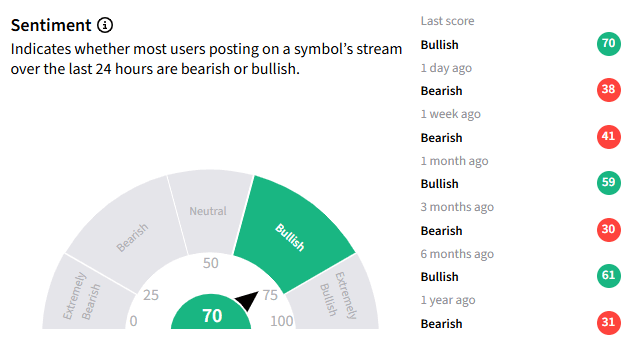
On Stocktwits, retail sentiment for WDC jumped to ‘bullish’ from ‘bearish’ levels a day ago amid a 754% surge in 24-hour message volumes.
One user said, “$WDC HUGE BEAT & great guidance. Memory is undervalued. I believe November will a HUGE month for this sector.”
View this Stocktwits post
Another user said, “$WDC I'm starting to think I don't understand stocks anymore since fundamentals stopped mattering in the thirty years I've been investing. Crush an earnings report and raise guidance, absolutely print money? Stock goes down because you didn't print enough despite being undervalued.”
View this Stocktwits post
WDC stock has surged 106% year-to-date.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
