
CFO Wayne DeVeydt called the lower end of the company’s 13% to 16% long-term earnings growth target a “reasonable starting point.”
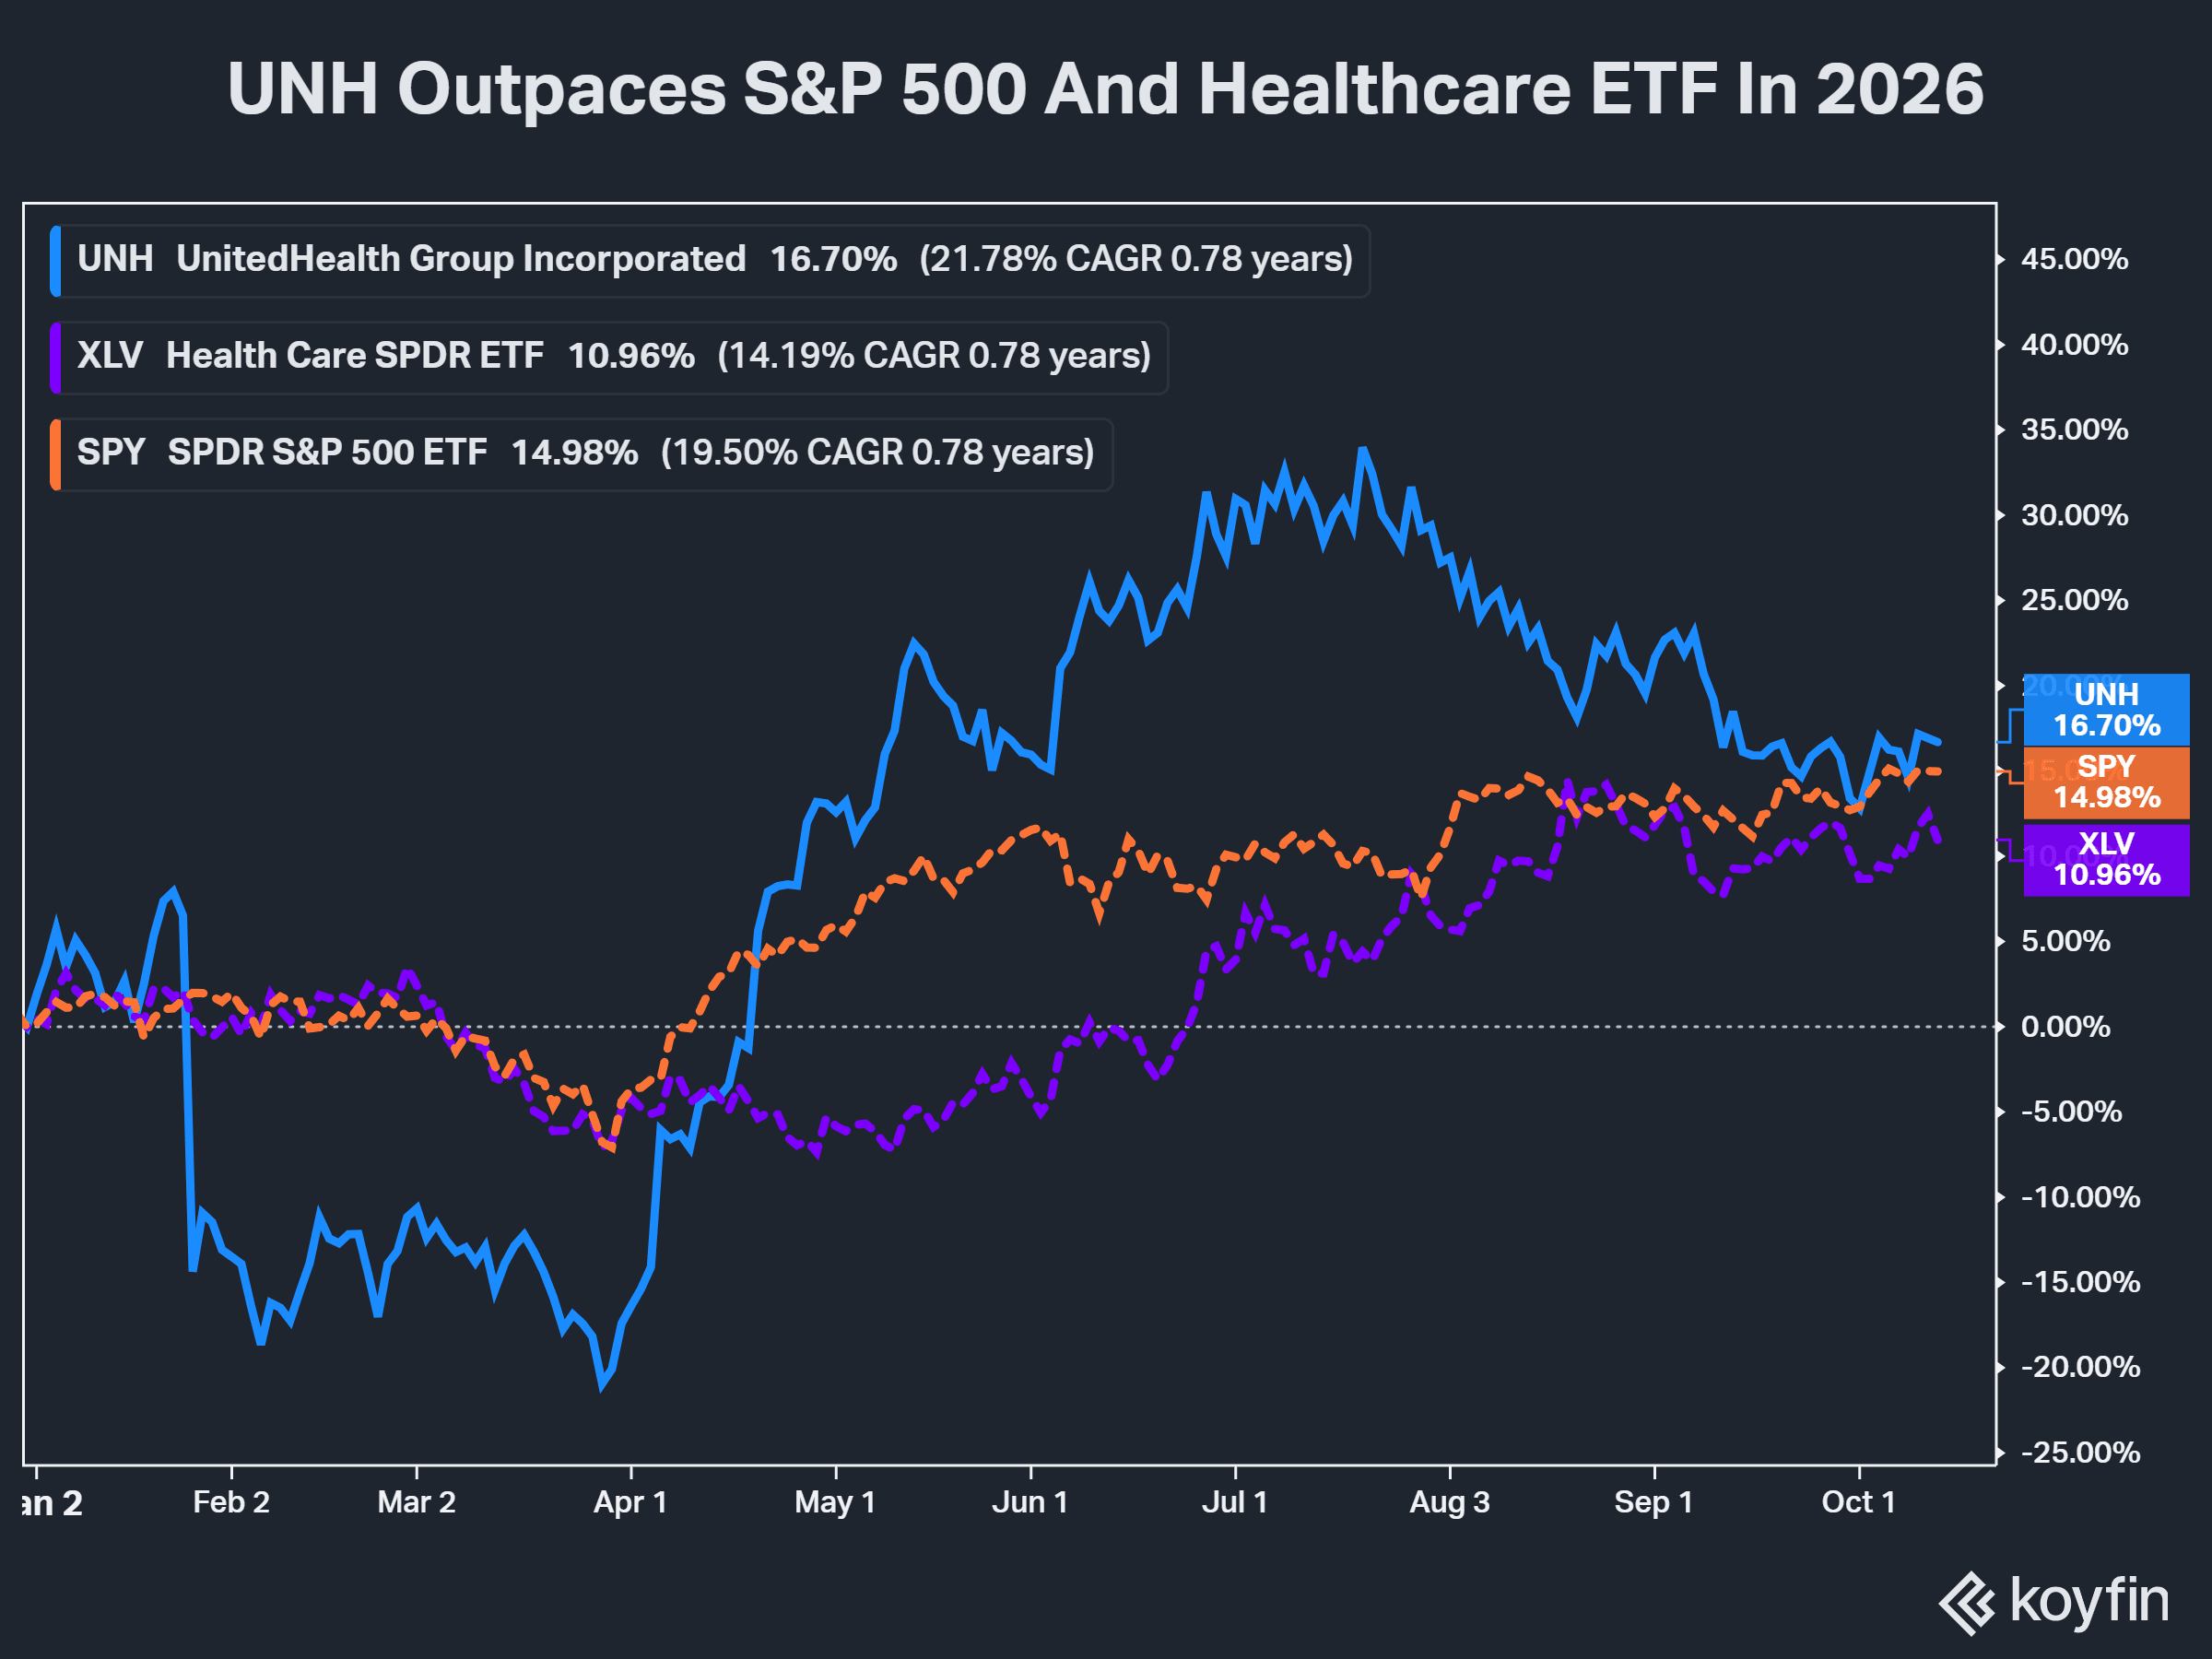
- UNH shares are up 17% in 2026, ahead of the S&P 500’s 14% gain but behind XBI’s 21% rise, after falling 33% last year.
- UnitedHealth beat Q3 estimates with adjusted EPS of $4.69 and revenue of $112.69 billion, then raised its 2026 adjusted EPS outlook to at least $20.50.
- External clients made up more than half of Optum Rx’s membership for the first time.
Shares of UnitedHealth (UNH) have outpaced the S&P 500 so far in 2026 and are on pace for their strongest year since 2021. Now, CFO Wayne DeVeydt says Wall Street may be underestimating the company’s earnings opportunity in 2027.
UNH stock is up nearly 17% in 2026, outpacing the S&P 500’s 14% gain and the Health Care Select Sector SPDR Fund’s (XLV) 11% rise. The rebound follows a 33% plunge last year.
UNH CFO Sees 2027 Upside Wall Street May Miss
UnitedHealth reported third-quarter (Q3) adjusted earnings of $4.69 per share, topping the $4.14 analyst consensus. Revenue also beat estimates, coming in at $112.69 billion on $111.49 billion, though it was slightly below the $113.2 billion reported a year earlier. Earnings from operations climbed to $6.6 billion from $4.3 billion. The company raised its 2026 adjusted earnings outlook to at least $20.50 per share, from a previous range of $19.50 to $20.
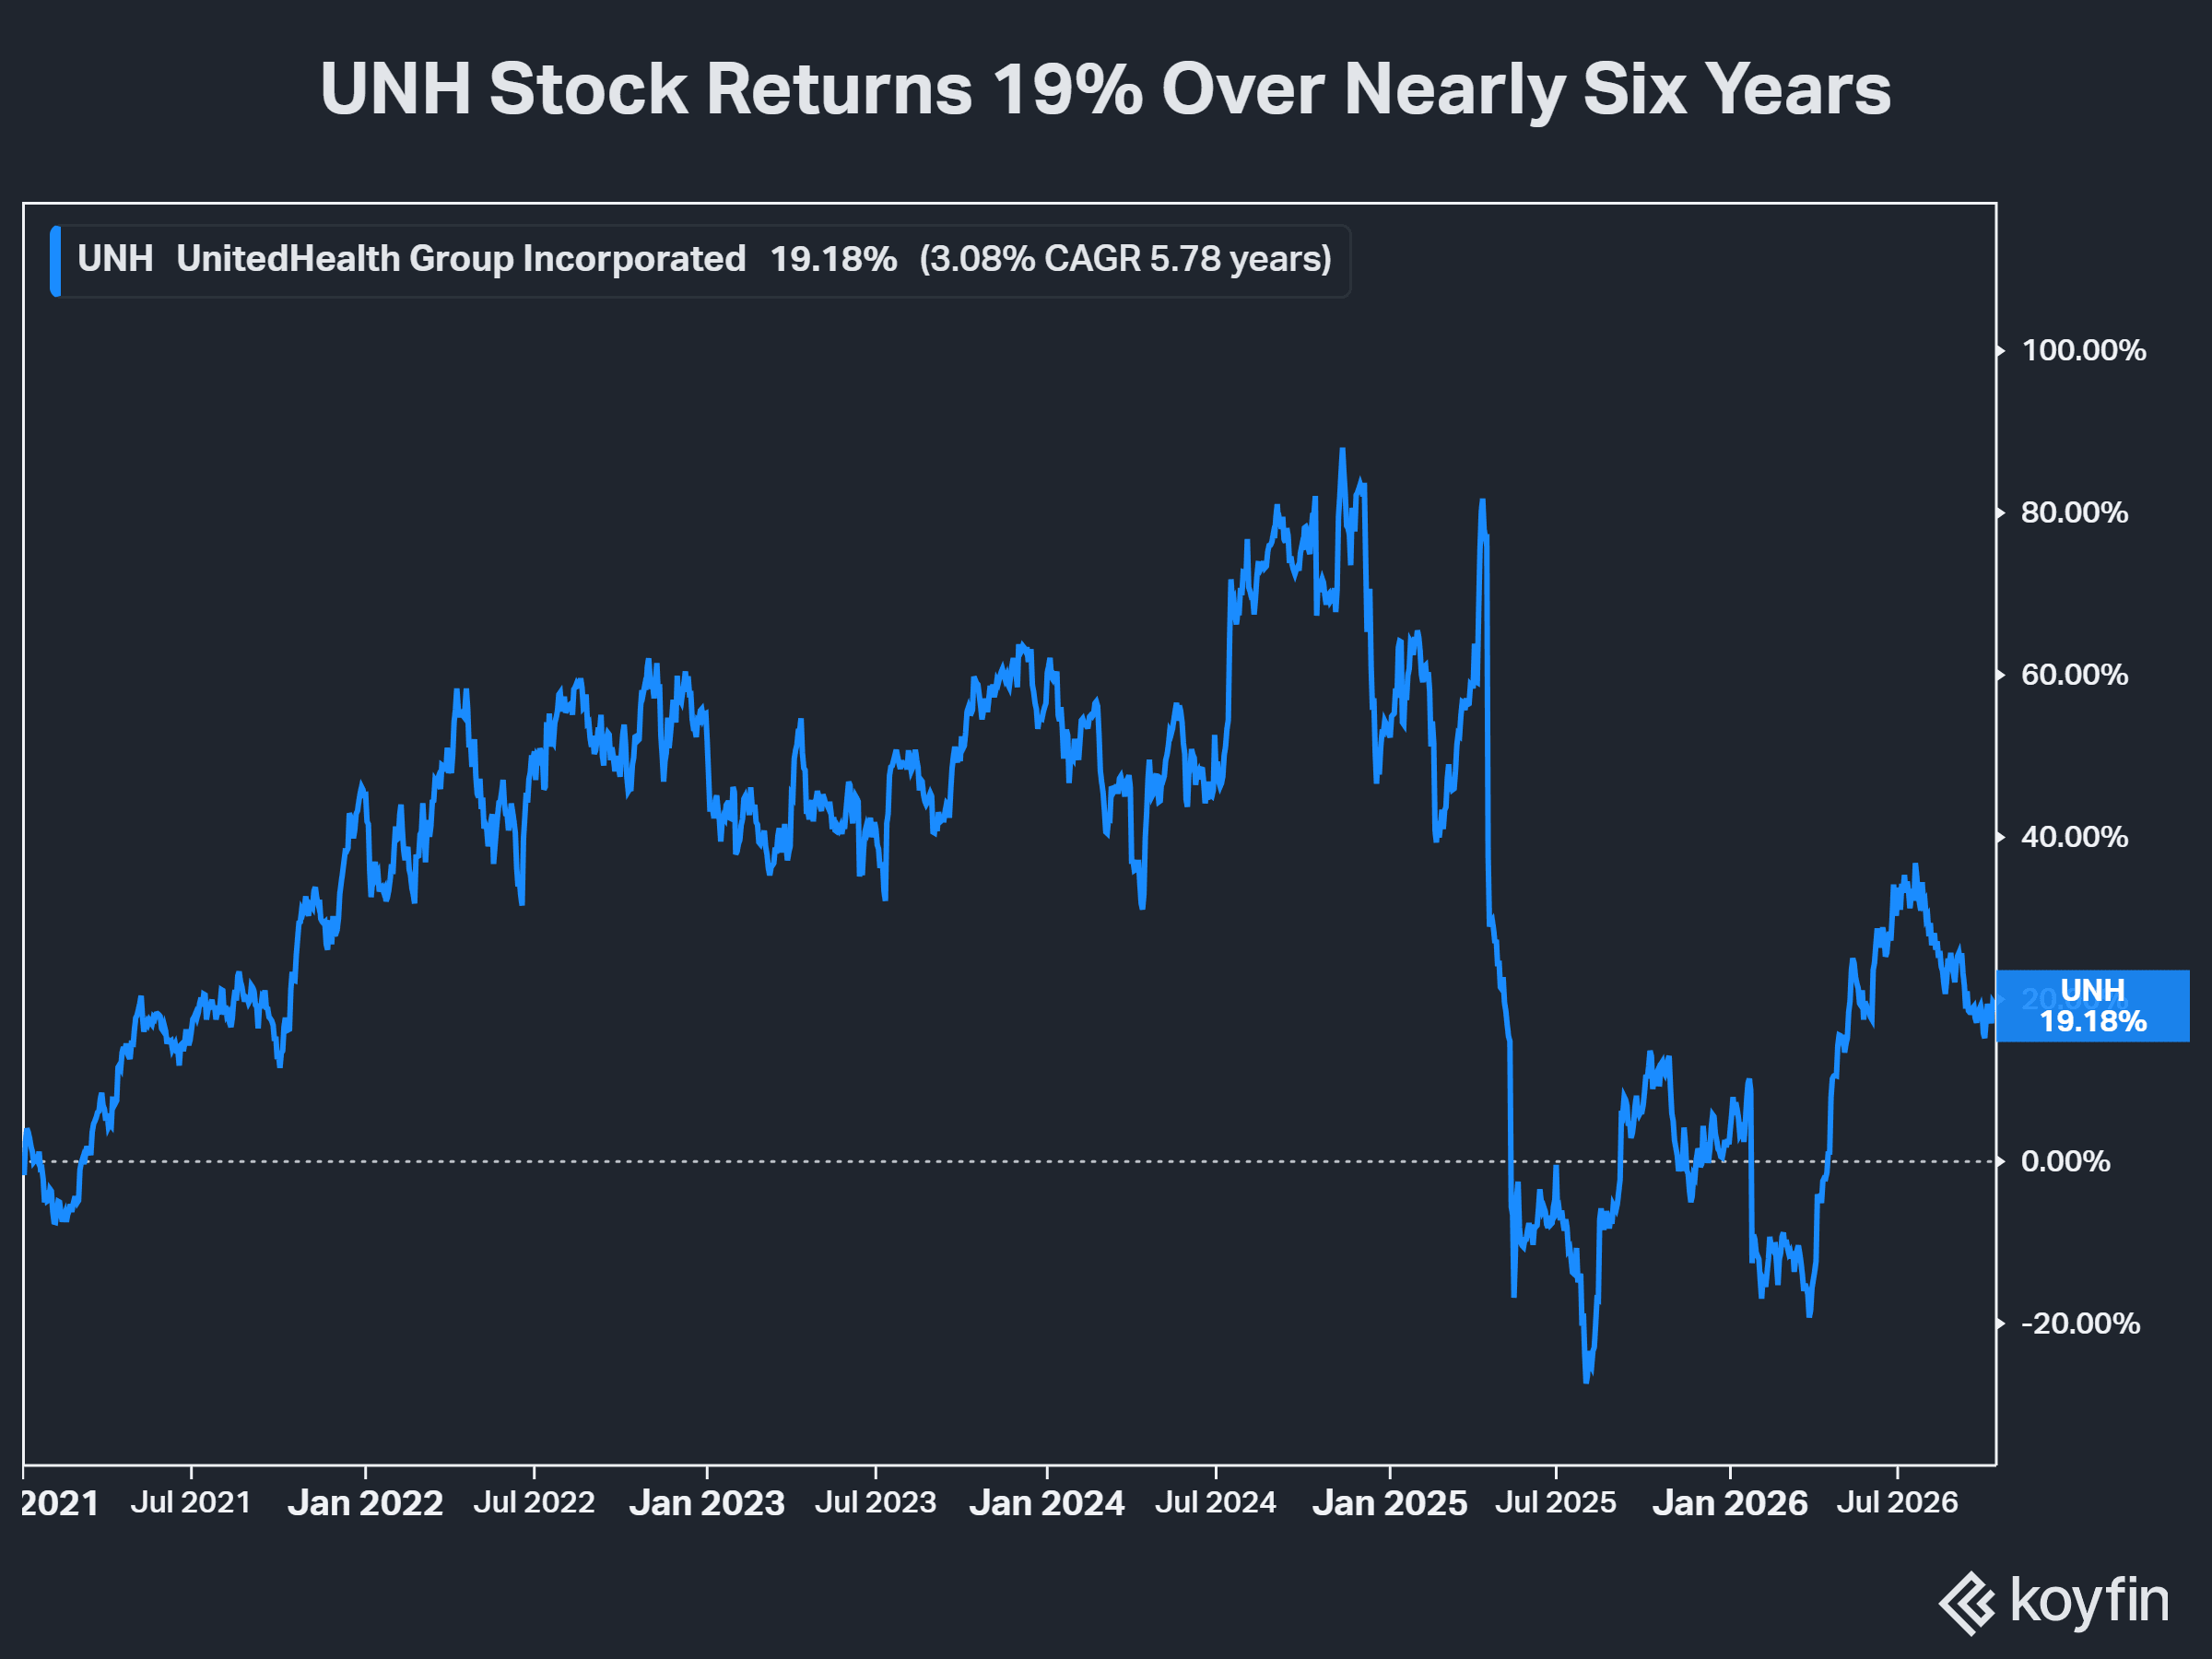
But even after its recent rebound, UNH shares are up just 19% since January 2021, a 3% annualized gain over nearly six years.
“Current analyst consensus for 2027 may understate the opportunity ahead,” DeVeydt said on the earnings call. He added, “The quality of earnings is strong and durable as we head into 2027.” He called the lower end of UnitedHealth’s long-term adjusted earnings growth target of 13% to 16% a “reasonable starting point.”
By Stocktwits’ calculation, 13% growth on the $20.50 floor would imply about $23.17 a share in 2027. Analysts’ quarterly estimates compiled by Fiscal.ai sum to about $22.80.
DeVeydt cited share repurchases, value-based care, enterprise-wide progress and gains from artificial intelligence and modernization as potential tailwinds. He also flagged policy reforms, modernization spending, medical-cost trends and pressure on health-benefit funding as headwinds.
UNH Sales Climb, But Profits Stall
Quarterly revenue climbed 61% from $70.2 billion in the first quarter of 2021 to $112.7 billion in the third quarter of 2026. Operating profit, however, was nearly unchanged, slipping from $6.7 billion to $6.6 billion. Revenue hovered around $112 billion in the second and third quarters of 2026, while earnings per share swung more sharply.
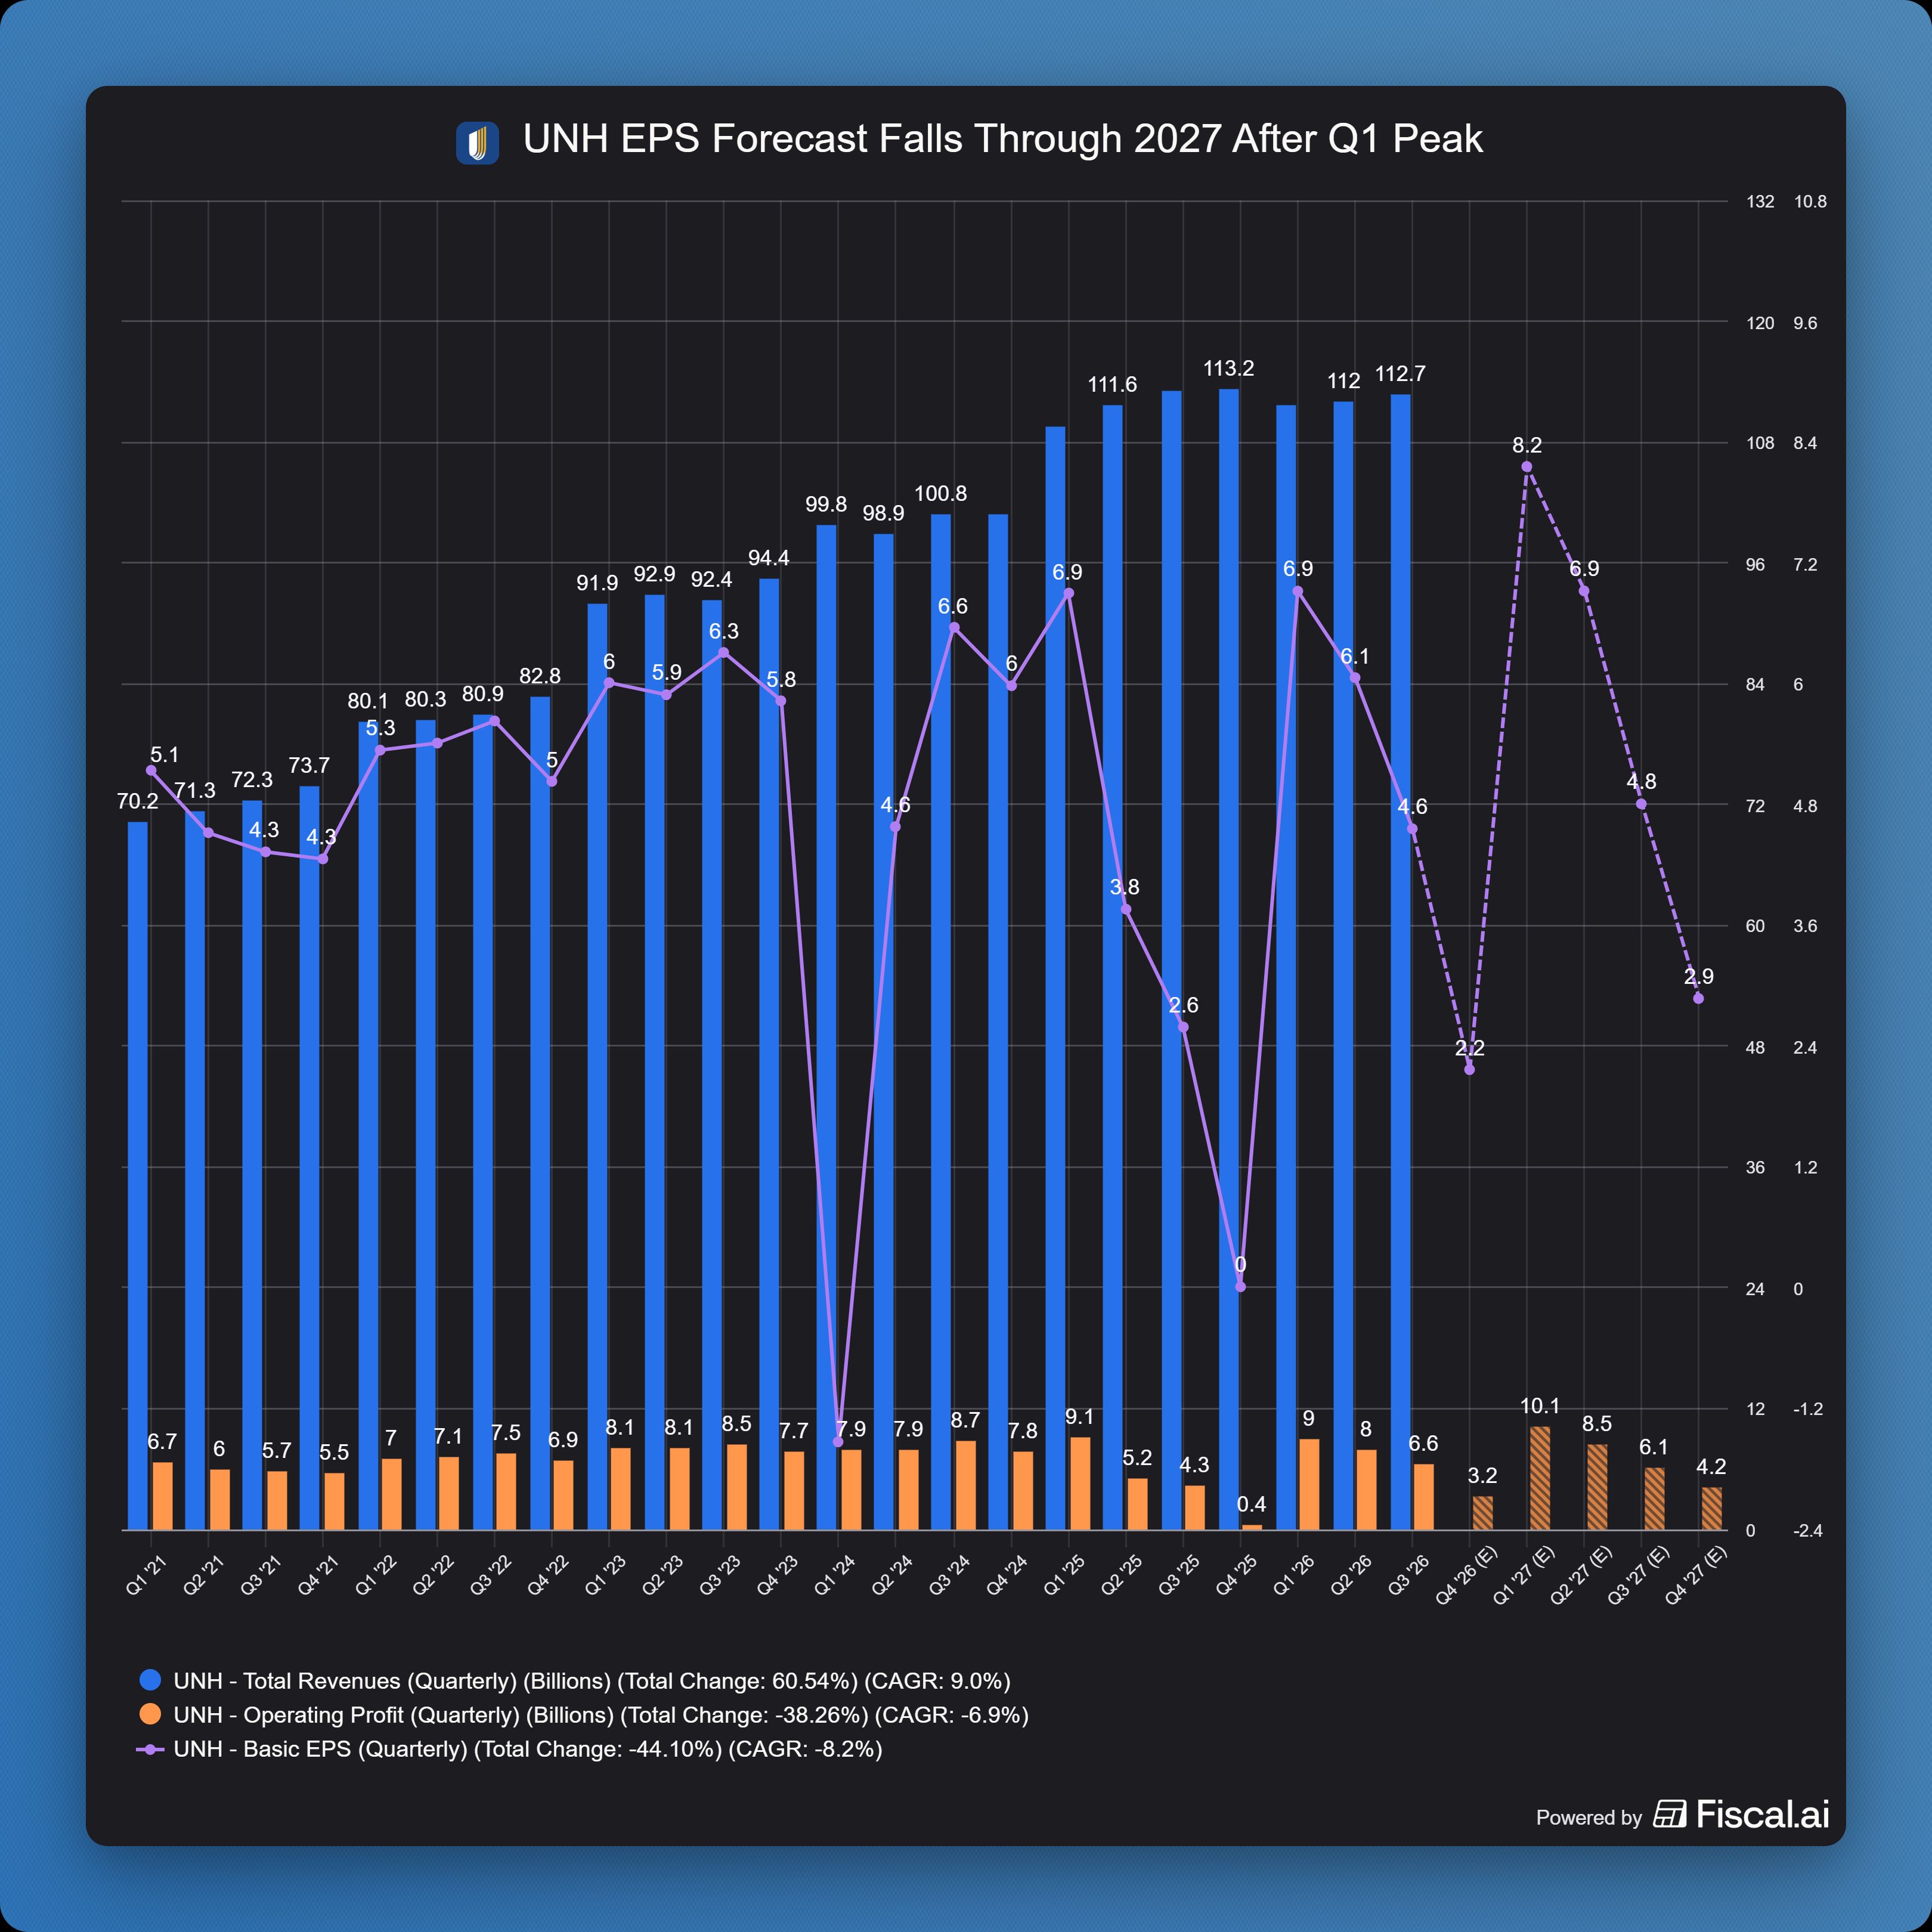
Basic EPS fell to nearly zero in the fourth quarter of 2025, rebounded to $6.90 in the first quarter of 2026, then declined to $6.10 in the second quarter and $4.60 in the third. UnitedHealth reported adjusted EPS of $2.11 for the fourth quarter of 2025. Analysts estimate basic EPS will peak at $8.20 in the first quarter of 2027, then fall to $6.90 in the second quarter, $4.80 in the third and $2.90 in the fourth, according to Fiscal.ai.
UnitedHealth’s average 12-month analyst price target is $480.68, implying about 27% upside from current levels. Of 26 analysts, 7 rate the stock ‘Strong Buy,’ 15 ‘Buy’ and 4 ‘Hold’; none rate it ‘Sell’ or ‘Strong Sell,’ according to Koyfin.
UNH’s Medicare Advantage Recovery Faces Membership Test
UnitedHealth’s medical care ratio fell to 88.4% in the third quarter from 89.9% a year earlier, reflecting tighter pricing, benefit changes and cost controls. The result also included $610 million in favorable reserve development. But the ratio rose from 86.7% in the second quarter, and commercial medical trends remained above 11%. When asked whether the trends were worsening, UnitedHealthcare CEO Tim Noel said, “We are not seeing the dynamics that you are talking about.”
Medicaid is another pressure point. UnitedHealth expects 2026 to be a trough year for core Medicaid margins, which it now projects to be moderately better than negative 1%. The firm expects margins to return to targeted levels by the end of 2028.
At least 69% of UnitedHealthcare’s Medicare Advantage members are in plans rated four stars or higher in the 2027 star ratings, which affect bonus payments in 2028. The company expects that share to reach 75% as it moves through 2027 and into 2028, compared with a 70% industry average. The company plans to focus on high-value Health Maintenance Organization (HMO) plans and special-needs plans for people with chronic conditions or who qualify for both Medicare and Medicaid.
Optum Lifts UnitedHealth’s Earnings
UnitedHealthcare is UnitedHealth’s revenue heavyweight, bringing in $86.3 billion in the third quarter. It provides health coverage to employers and individuals and runs the company’s Medicare Advantage and Medicaid plans. Revenue dipped from $87.1 billion a year earlier, but operating earnings climbed to $2.8 billion from $1.8 billion.
Optum is the group’s health-services engine. Optum Health delivers care and manages provider networks. Optum Rx handles pharmacy services and prescription benefits. Optum Insight provides tech and data services to healthcare organizations. Together, the businesses generated $66.9 billion in revenue and $3.7 billion in operating earnings. Optum Health’s earnings surged to $735 million from $41 million, while Optum Rx said external clients made up more than half its membership for the first time. Retention remained in the high 90s.
How Do Retail Traders Feel About UNH?
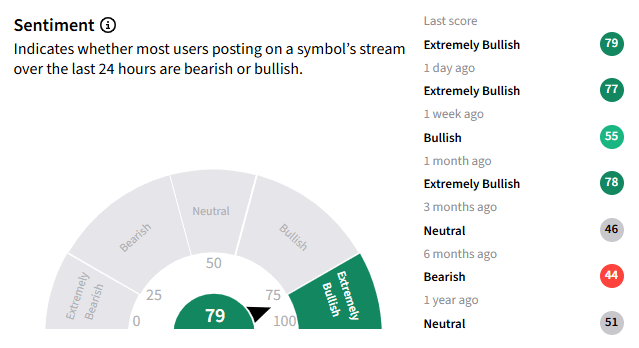
On Stocktwits, retail sentiment for UNH has surged to ‘extremely bullish’ from ‘bearish’ levels over the last six months amid a 5,075% surge in monthly message volumes. The ticker’s watcher base has risen 3% in a year, indicating modest retail interest.
One user said, “$UNH Solid support at $369. Absent any litigation news, I just don’t see them being able to bring this down anymore on back to back beats and a proven turnaround effort. Good place to add and go long.”
View this Stocktwits post
Another user said, “$UNH the stock is fine. It’s not an AI stock. Boring and slow moving 10-15% gain a year. Solid hold in a portfolio.”
View this Stocktwits post
For updates and corrections, email newsroom[at]stocktwits[dot]com.
