Analysts remain divided over whether Seagate's pricing power and HAMR technology advantages can offset slower storage shipments and potential industry supply increases.
- UBS warned of increased HDD supply as Western Digital Corp advances its HAMR transition.
- TD Cowen sees potential for more than 30% exabyte growth in calendar 2027 without higher capital intensity.
- Seagate forecasted Q2 adjusted EPS of $9.00 to $9.40 on revenue of $4.7 billion to $4.9 billion.
Seagate Technology Holdings (STX) drew a ratings downgrade and a slew of price target cuts on Wednesday, with analysts flagging weaker-than-expected shipment growth, valuation concerns, and potential increases in industry supply.
Summit Insights downgraded the stock to ‘Hold’, citing a less favorable industry backdrop heading into 2027, according to The Fly. Meanwhile, Baird bucked the broader trend, raising its price target by 25% to $1,350 from $1,080.
As of this writing, STX stock traded more than 6% lower and was among the trending tickers on Stocktwits.
Wall Street’s Take On STX Earnings
Summit Insights acknowledged management's disciplined approach to capacity expansion but expects Seagate and the broader storage industry's outperformance to moderate through 2027, according to The Fly.
Meanwhile, UBS warned that industry supply could accelerate as Western Digital (WDC) completes its transition to heat-assisted magnetic recording (HAMR). The firm also flagged elevated relative valuations, which could pressure Seagate's valuation multiples despite strong HDD pricing.
Morgan Stanley cited weaker-than-expected exabyte growth and cost reductions, prompting modest cuts to its earnings estimates.
Citi noted Seagate's strong pricing. However, lower exabyte shipments caused quarterly results to fall short of its estimates. The firm attributed its price target reduction to lower peer valuation multiples, even as it raised its estimates to reflect Seagate's pricing power and demand visibility.
Why Some Analysts Remain Bullish on STX Stock
Despite lowering its target, Mizuho described Seagate's September-quarter results as strong and said it would buy shares on weakness, citing limited competition as HAMR production ramps up, according to The Fly.
Wells Fargo expects the company's Mozaic 4 platform ramp to drive strong sequential growth through fiscal 2027. The firm highlighted improved demand visibility, a path toward gross margins above 70%, and potential shareholder returns.
According to a note cited by TheFly, TD Cowen viewed Seagate's decision not to increase capital intensity as the quarter's biggest positive surprise, suggesting that the HAMR transition alone could support more than 30% exabyte growth in calendar 2027.
Susquehanna expects several more quarters of double-digit increases in average selling prices, with operating margins trending toward the high-50% range. However, the firm said these expectations were already reflected in its above-consensus estimates.
Analyst / Firm | Rating | New Target Price | Previous Target Price | Change From Last Close |
Citi | Buy | $1,050 | $1,300 | +57.2% |
Morgan Stanley | Overweight | $1,148 | $1,200 | +71.9% |
UBS | Neutral | $750 | $780 | +12.3% |
Wells Fargo | Overweight | $820 | $865 | +22.8% |
Mizuho | Outperform | $900 | $1,090 | +34.8% |
Susquehanna | Neutral | $765 | $925 | +14.5% |
TD Cowen | Buy | $900 | $1,000 | +34.8% |
Baird | Outperform | $1,350 | $1,080 | +102.1% |
Summit Insights | Hold (Downgrade) | - | - | - |
Seagate's Latest Earnings And Outlook
Seagate reported fiscal first-quarter (Q1) revenue of $4.23 billion, up 61% year-over-year, while adjusted earnings per share (EPS) increased to $7.68 from $2.61 a year earlier.
CEO Dave Mosley highlighted strengthening demand and long-term customer visibility, saying the company's HAMR technology roadmap would help address growing storage capacity requirements while maintaining supply discipline.
For the fiscal second quarter, Seagate expects revenue of $4.8 billion, plus or minus $100 million, and adjusted EPS of $9.20, plus or minus $0.20.
Retail Investors’ Sentiment Around STX Stock
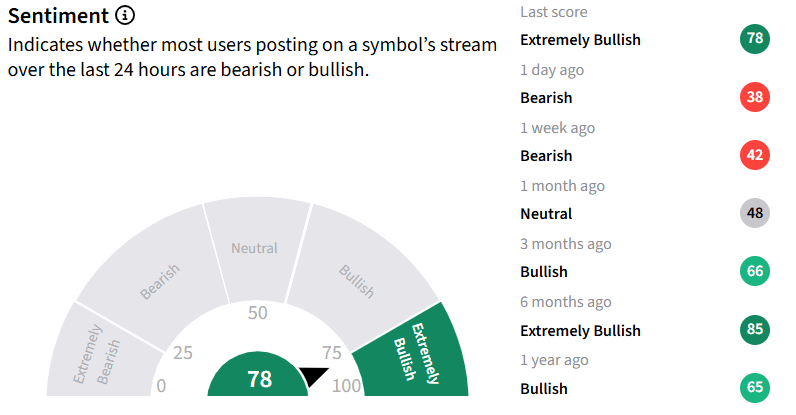
Despite the selloff in STX on Wednesday, retail investors' sentiment around STX stock improved to ‘extremely bullish’ from ‘bullish’ a day ago amid higher message volume.
So far this year, STX stock has surged over 117%. By comparison, the Roundhill Memory ETF (DRAM), which holds the stock, has risen over 90% over the same period.
See Also: SKHY Stock: Analyst Sees 175% Upside Potential For SK Hynix, Company's Q3 Beat Uplifts MU, SNDK, WDC
For updates and corrections, email newsroom[at]stocktwits[dot]com.<