
Despite the negative sentiment, Morningstar said in a report on Wednesday that Netflix’s drop has created the best buying opportunity for the company’s shares in years.
- The analyst maintained a ‘Narrow’ economic moat and a price target of $80 on NFLX shares, implying more than 16% upside from its last close.
- Morningstar highlighted the ad-supported tier set to launch in 15 international markets in 2027, saying it would be a catalyst that would drive a surge in new members.
- The analyst also highlighted the management’s comments on reduced customer churn from last year to levels better than expected in the U.S. and international markets.
Shares of Netflix Inc. (NFLX) fell more than 6% in the premarket session on Wednesday, extending overnight declines after the company’s fourth-quarter (Q4) revenue guidance came in softer than expected.
Despite the negative sentiment, Morningstar said in a report on Wednesday that this has created the “best buying opportunity for Netflix shares in years.”
The analyst maintained a ‘Narrow’ economic moat and a price target of $80 on NFLX shares, implying more than 16% upside from its last close.
Morningstar Sees ‘Growth Drivers’
In its report, the analyst noted that while many of Netflix’s markets are mature and will likely not grow at the rate they did when they were rapidly adding new subscribers, “it still has growth drivers.”
Morningstar highlighted the ad-supported tier set to launch in 15 international markets in 2027, saying it would drive a surge in new members, much like it did in markets where the ad tier was first offered.
Netflix is slated to introduce an advertising tier from March 2027 in nine EMEA countries, and in Colombia, Peru and New Zealand, in addition to the 12 countries it already exists in.
The analyst also highlighted management’s comments on reduced customer churn in the U.S. and international markets, down to levels better than expected from last year.
“We expect additional U.S. price increases in 2027 and further advertising growth, as Netflix better fills inventory and narrows the revenue gap between ad-supported and ad-free users,” the analyst said.
“A growth slowdown was inevitable, but Netflix remains far superior to its subscription streaming peers, and its valuation multiples are now very reasonable, as we still expect double-digit annual profit growth,” Morningstar said.
NFLX Valuation
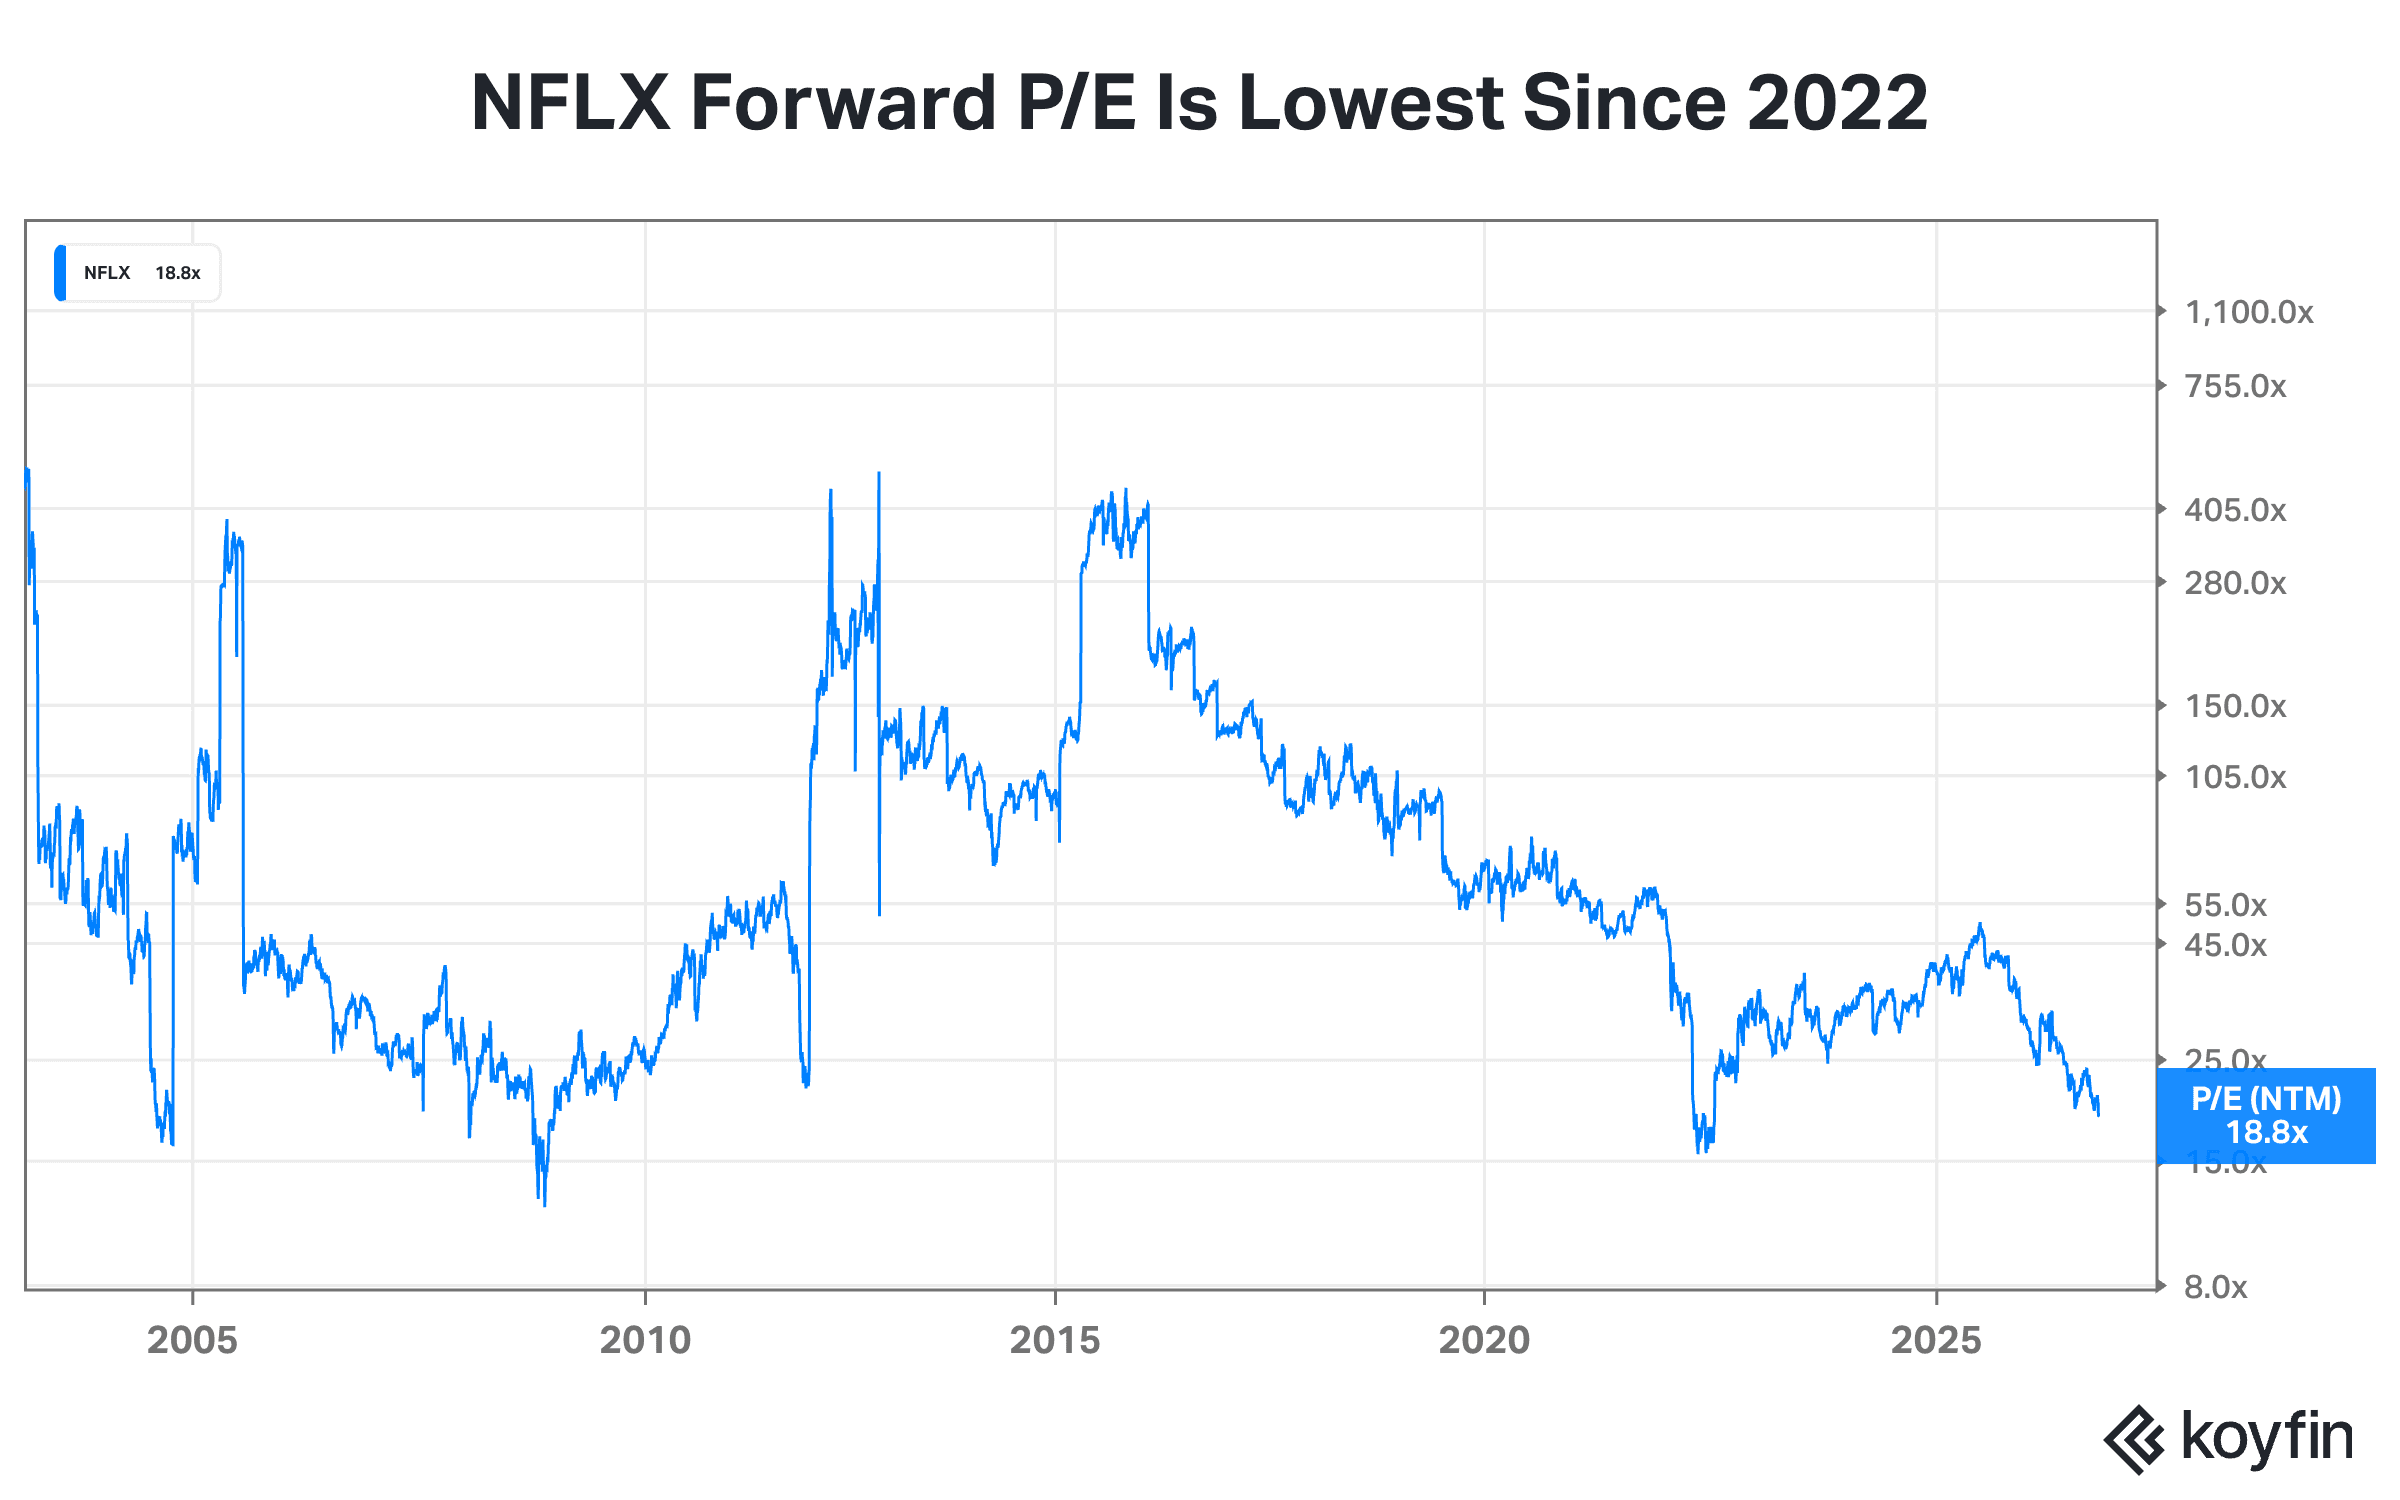
Netflix’s forward price-to-earnings ratio is 18.8x, the lowest it has been in more than four years, according to data from Koyfin. As per Fiscal.ai, this is the second-lowest multiple since 2010.
Meanwhile, Roku Inc. (ROKU) has a 12-month forward P/E ratio of 48x, while Apple Inc. (AAPL) trades at a multiple of 37x.
NFLX Earnings Snapshot
Netflix reported Q3 revenue of $12.9 billion, meeting analysts’ estimates, while earnings per share of $0.87 beat expectations.
For the upcoming quarter, the streaming giant projects revenue of $13.4 billion, below Wall Street estimates of $13.5 billion. Netflix also expects a Q4 operating margin of 26%.
NFLX Stock: Retail Stance
On Stocktwits, retail sentiment around NFLX stock improved from ‘neutral’ to ‘bullish’ over 24 hours, amid a 908% increase in message volumes, according to platform data.
One user said, “$NFLX Considering entry here. Eventual recovery to 80's looks likely.”
Another user said, “$NFLX honestly I’m gonna load everything I can into this stock now. Talk about mega cheap. So due for a big run to 80s.”
NFLX stock has tanked 24.5% in 2026.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
