
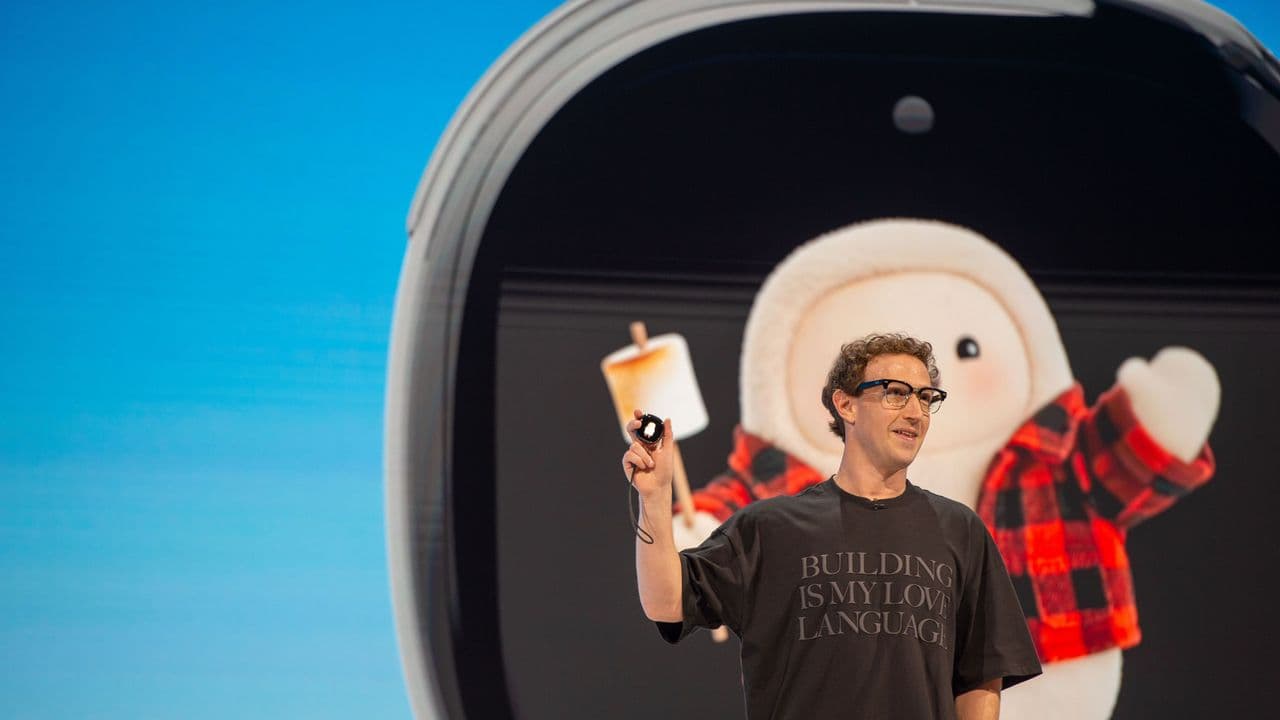
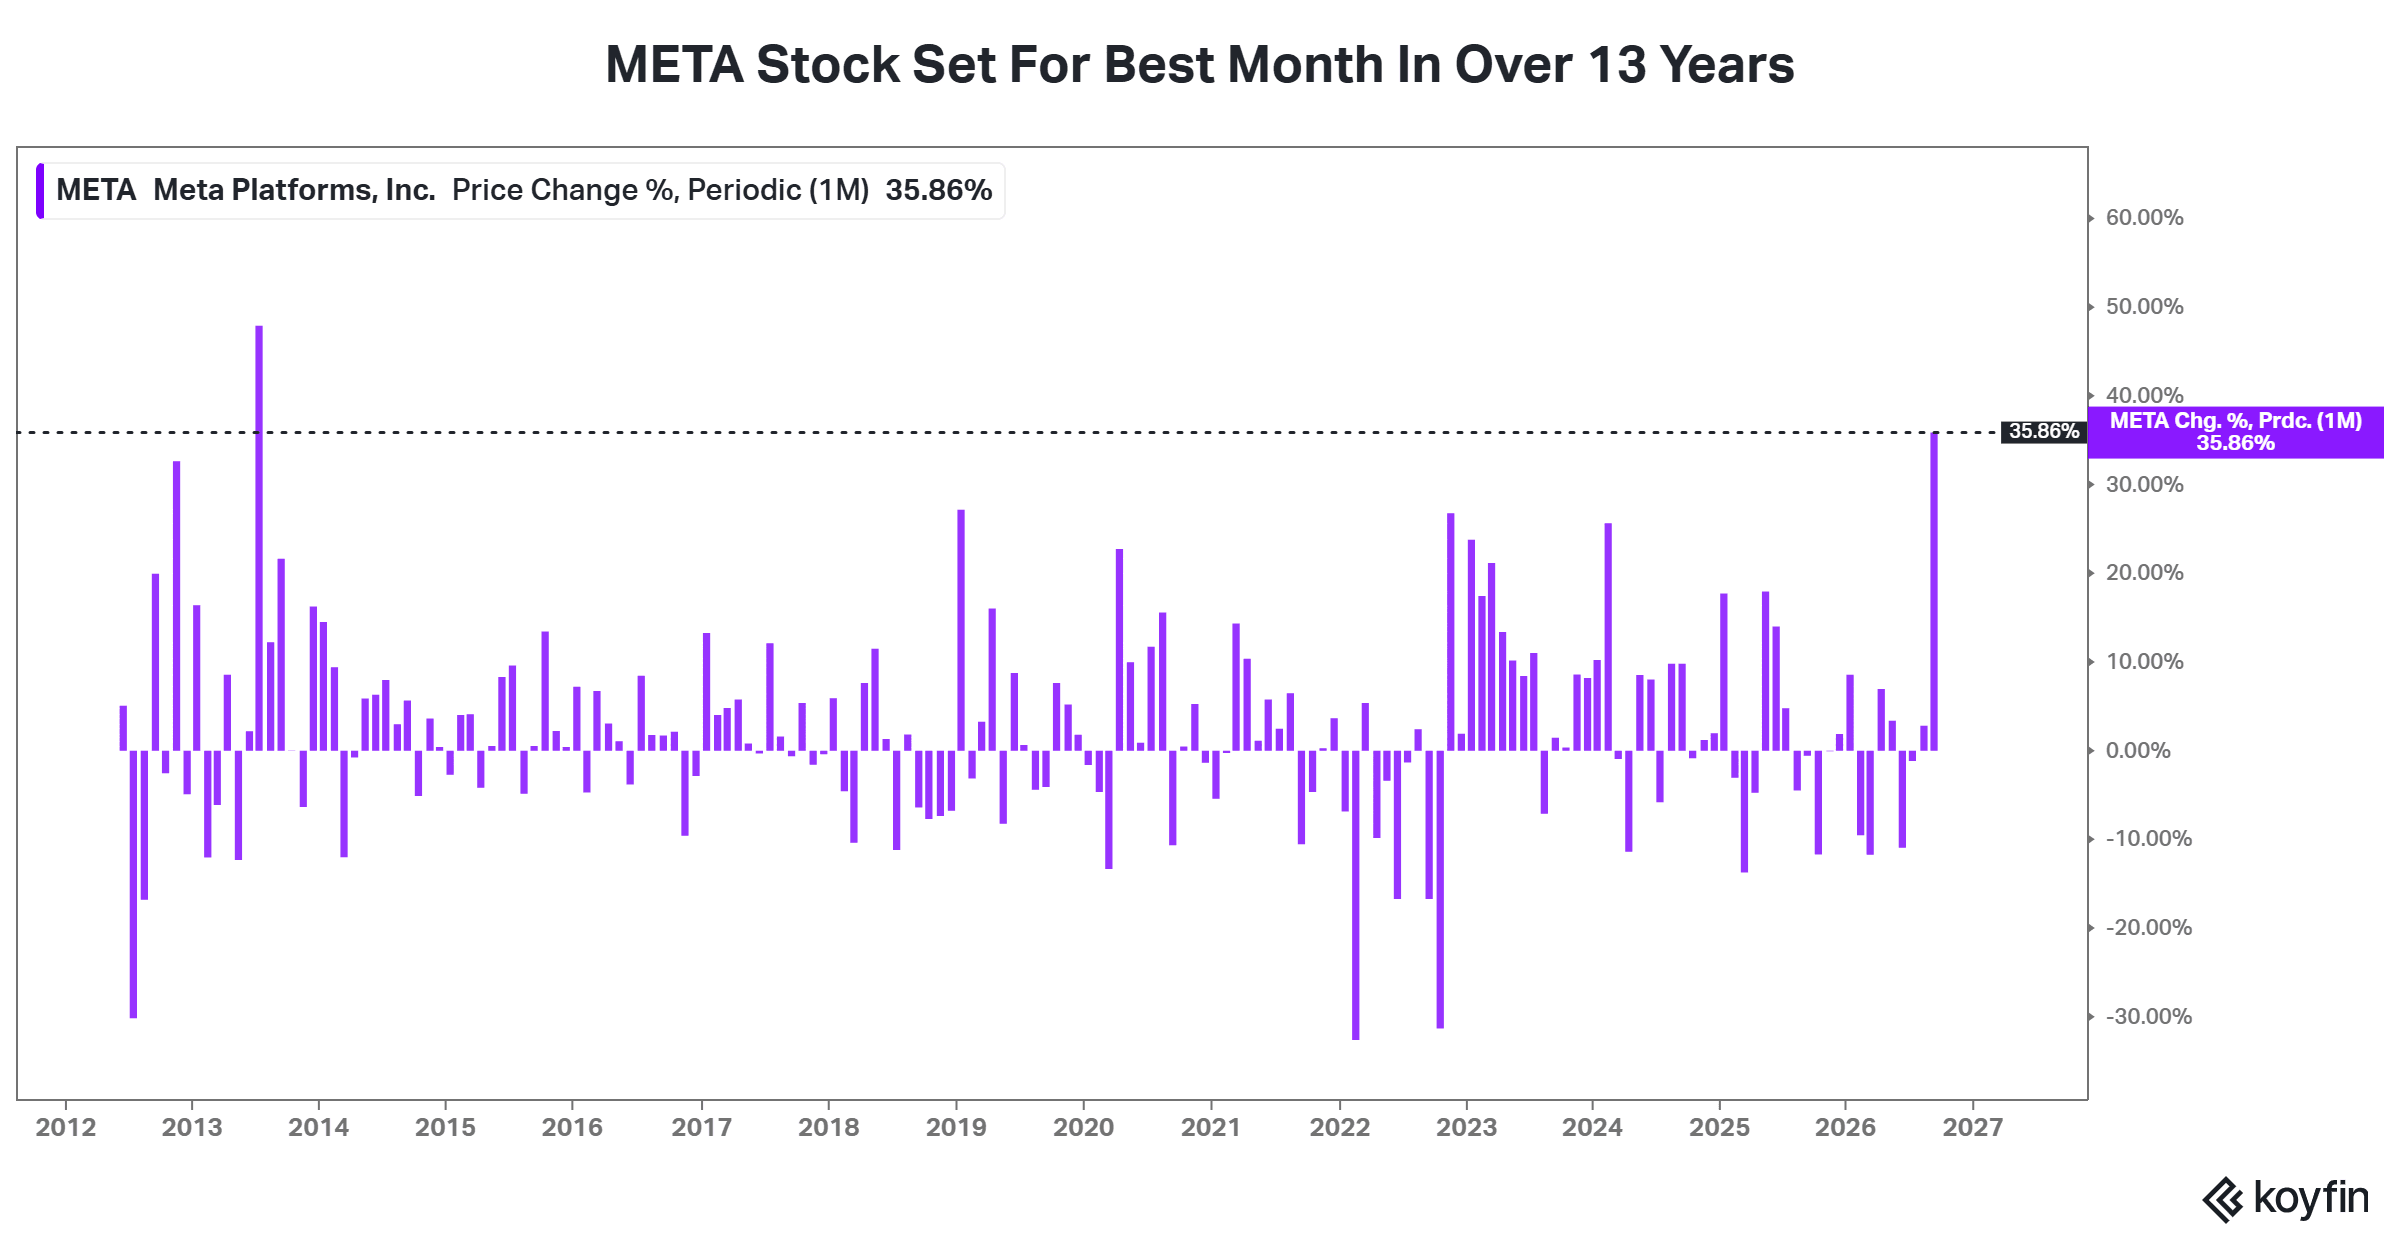
Meta shares are experiencing their strongest monthly surge in over a decade, driven by strong consumer adoption of its new Muse AI assistant.
- Meta stock jumped 36% so far in September, bringing the tech giant within 1% of a $2 trillion market capitalization.
- Wall Street sentiment rebounded following an $18 billion legal settlement and new commercial partnerships with Expedia and Maplebear Inc.
- Concerns linger over massive AI infrastructure costs, with capital expenditures projected to hit nearly $140 billion this year.
Meta Platforms Inc. (META) is approaching a $2 trillion market valuation following its strongest monthly stock performance since July 2013, largely driven by enthusiastic market response to its newly released Muse personal AI assistant.
The Facebook parent company's stock is up 36% so far in September, rebounding sharply from among the S&P 500's worst performers as recently as mid-August. Since then, shares have rallied 43%, positioning Meta as the index's third-best performer over that span.
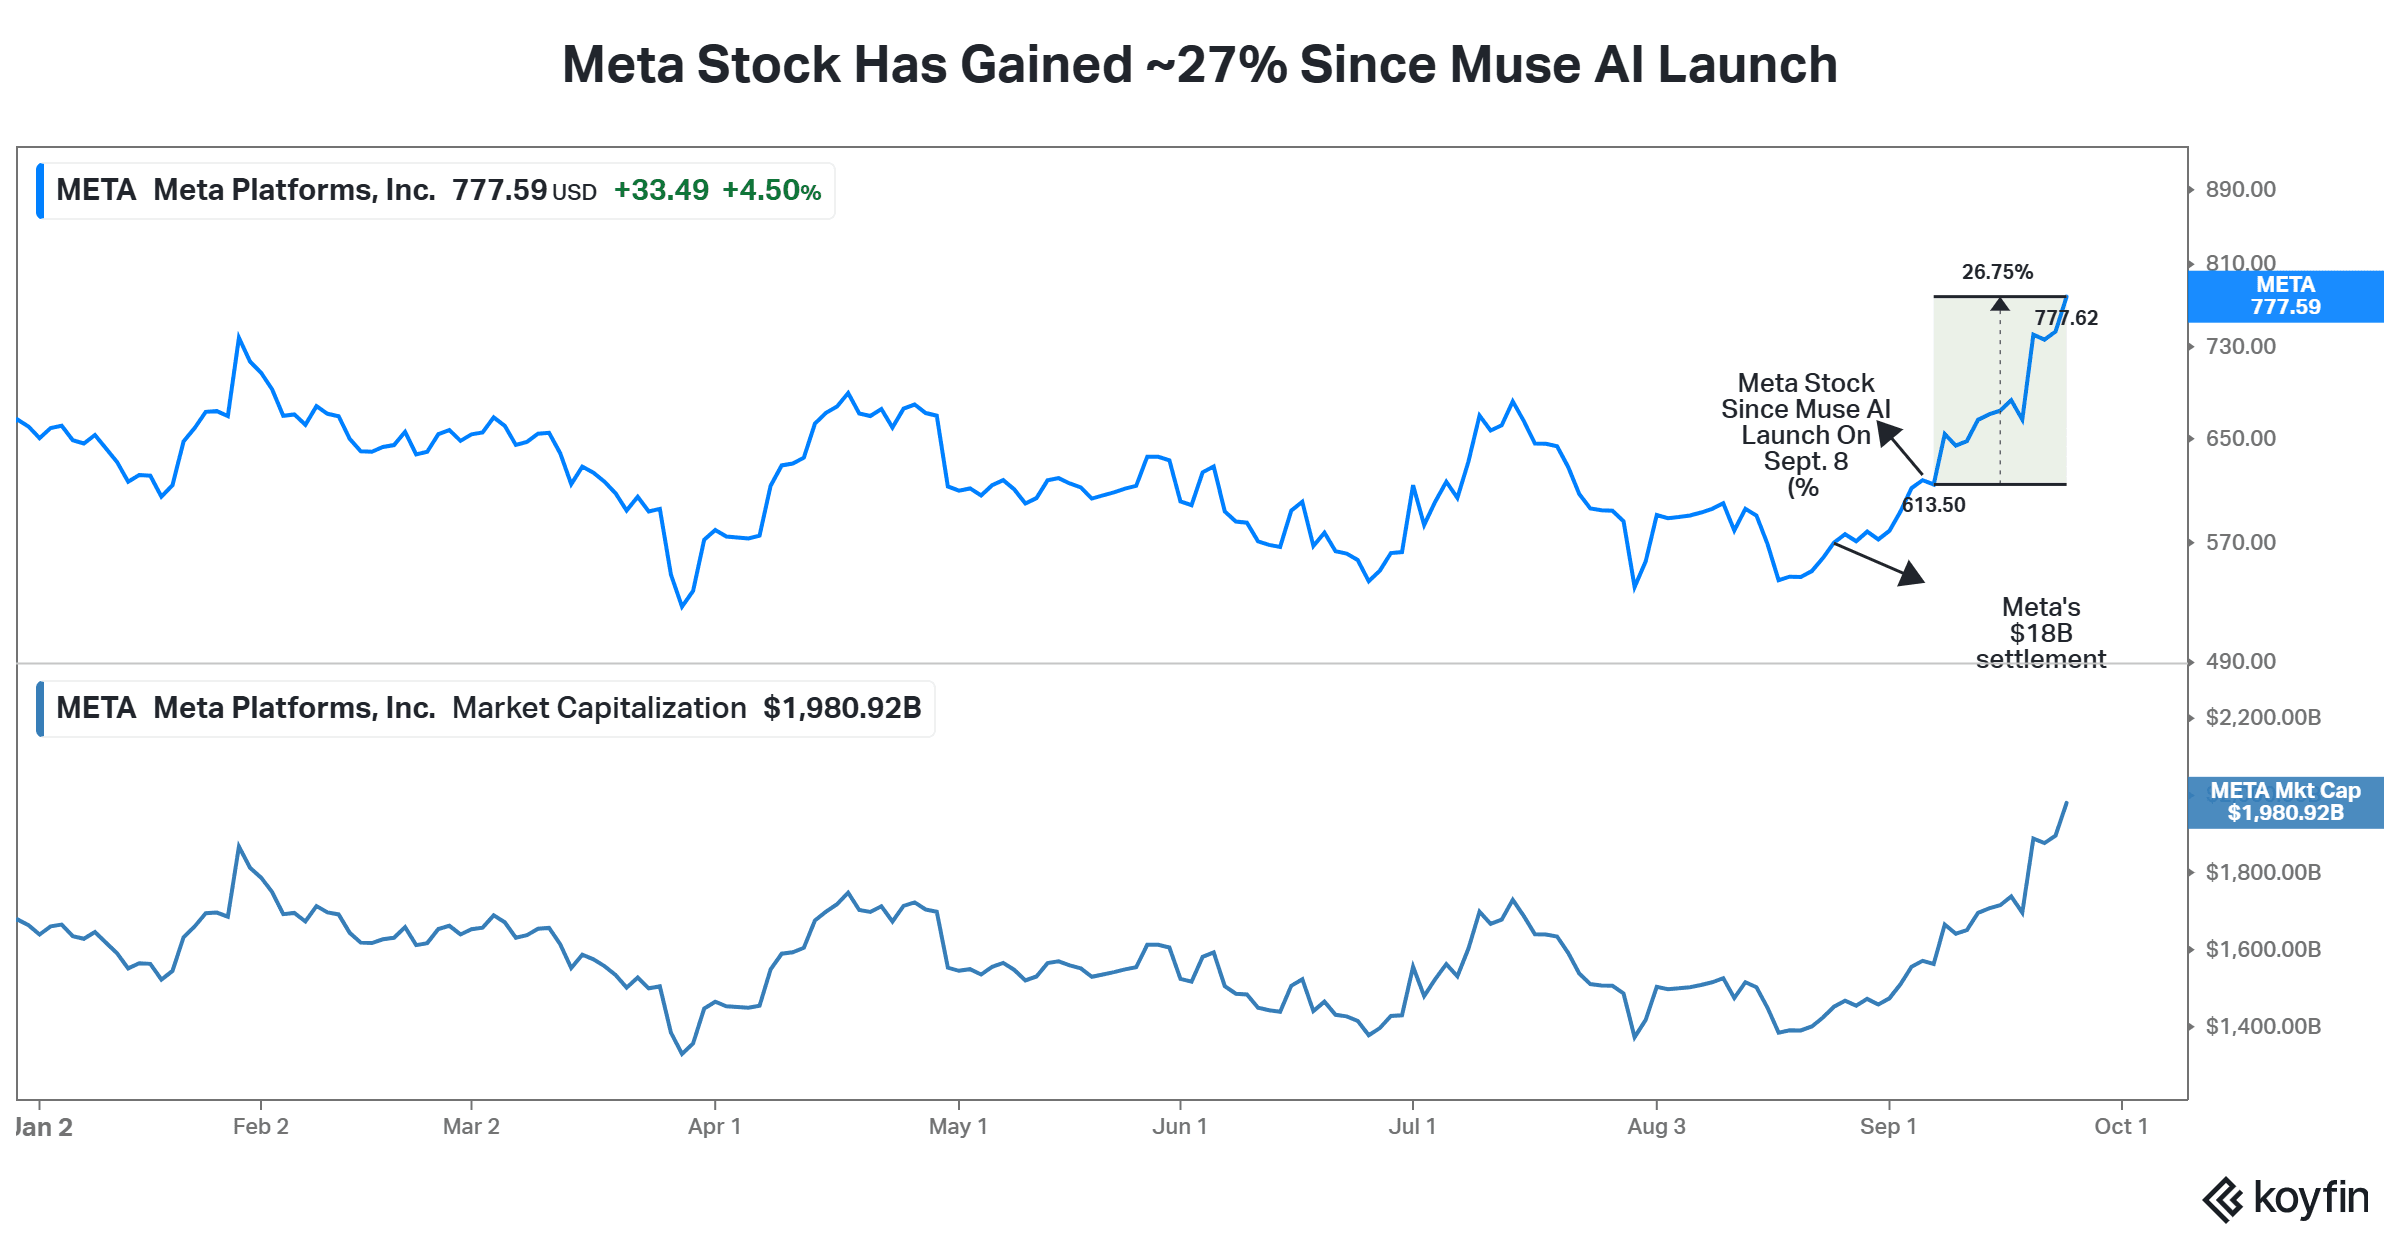
Meta stock has gained close to 27% since the launch of its Muse AI assistant on Sept.8 and is up about 18% year-to-date.
Muse AI Popularity And Partnerships Help
The lull in Meta's stock price started to reverse course after the company agreed to pay up to $18 billion to resolve a major social media lawsuit pertaining to social media addiction among children, eliminating a long-standing legal headwind. Investor focus has since shifted to Meta's aggressive deployment of consumer-facing AI products.
The rapid adoption of the Muse assistant, which quickly reached top rankings on mobile app stores, reassured investors regarding Meta's artificial intelligence expenditures.
“Muse clearly validates its AI strategy and position, after a year and a half where the stock was basically flat because people didn’t know if AI was going to be a net positive or a net negative,” Rob Biederman, co-founder and managing partner at Asymmetric Capital Partners, told Bloomberg in an interview.
“It’s logical that AI agents will become the front door to the internet for a lot of people, which puts the balance of power in Meta’s favor,” he added.
Expanding beyond software, Meta recently showcased new hardware offerings, including a portable device designed for Muse interactions and display-free smart glasses. The tech leader also announced direct e-commerce and booking integrations with Instacart parent Maplebear Inc.(CART) and Expedia Inc. (EXPE).
Capital Spending Risk Persists
Despite investor optimism, Meta faces ongoing scrutiny regarding its capital allocation. Capital expenditures are projected to reach approximately $140 billion this year, double the $70 billion spent in 2025, before expanding to $197 billion next year and $215 billion by 2028.
These expenditures are expected to strain immediate cash flow, moving Meta from $46 billion in free cash flow last year to an estimated negative $6.4 billion in 2026, and negative $29.2 billion in 2027.
Financial analysts project overall revenue to grow 26% to $254 billion this year, with net income expanding 33% to $80.6 billion. However, revenue growth is anticipated to moderate to 20% next year, with net income growth slowing to 9%.
META Stock: Retail View
Retail sentiment on Stocktwits was ‘bullish’ with ‘high’ message volumes.
META stock has gained 18.2% year-to-date.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
