
Oppenheimer sees rising contract values and early AI traffic monetization supporting growth in the high teens to low 20s over the next few years, according to TheFly.
- Oppenheimer sees Fastly’s growth potential as underappreciated, with stronger growth and margin expansion expected to drive a higher valuation.
- Fastly's second-quarter revenue grew 23% to $183.3 million, with security revenue up 43%.
- Fastly is slated to report its fiscal third-quarter earnings on November 4.
Fastly Inc. (FSLY) shares jumped nearly 16% on Friday after Oppenheimer upgraded the edge cloud platform provider, citing growing contract values and early signs of revenue generation from agentic AI traffic.
According to TheFly, the brokerage said these trends could sustain stronger growth over the next few years and expects the stock to command a higher valuation as Fastly delivers growth and subsequent margin expansion.
As of this writing, FSLY stock was up 15.9% and among the trending tickers on Stocktwits.
Why Oppenheimer Turned Bullish
Oppenheimer's industry checks indicated that Fastly is seeing higher contract values alongside early monetization of traffic generated by agentic AI applications.
The firm believes these trends will persist and could collectively drive growth in the high teens to low 20s over the next few years, per TheFly.
The analyst also noted that the market is underappreciating this growth trajectory, with further upside in the stock's valuation dependent on management delivering stronger growth and improved margins.
What Other Analysts Are Saying About Fastly
Oppenheimer's upgrade follows several analyst assessments last month after Fastly's Investor Day. Freedom Broker maintained its ‘Buy’ rating, citing stronger monetization of existing customers, cybersecurity cross-selling, network convergence and infrastructure efficiency as drivers of long-term growth and margin expansion, according to The Fly.
DA Davidson maintained a ‘Neutral’ rating, noting Fastly's focus on expanding adoption beyond content delivery networks (CDNs). The firm highlighted robust demand for newer Bot Management and distributed denial-of-service (DDoS) protection products.
BofA, however, maintained its ‘Underperform’ rating. While becoming more receptive to potential benefits from agentic AI traffic, the firm said it wanted greater clarity on the traffic's contribution, monetization and Fastly's AI product differentiation.
Fastly's fiscal second-quarter (Q2) revenue increased 23% to $183.3 million, led in part by 43% growth in security revenue to $41.7 million.
The company has guided for third-quarter revenue of $184 million to $190 million and will report results after the market closes on November 4. The release will offer investors another opportunity to assess Fastly's growth and profitability trajectory.
What Retail Thinks About FSLY Stock
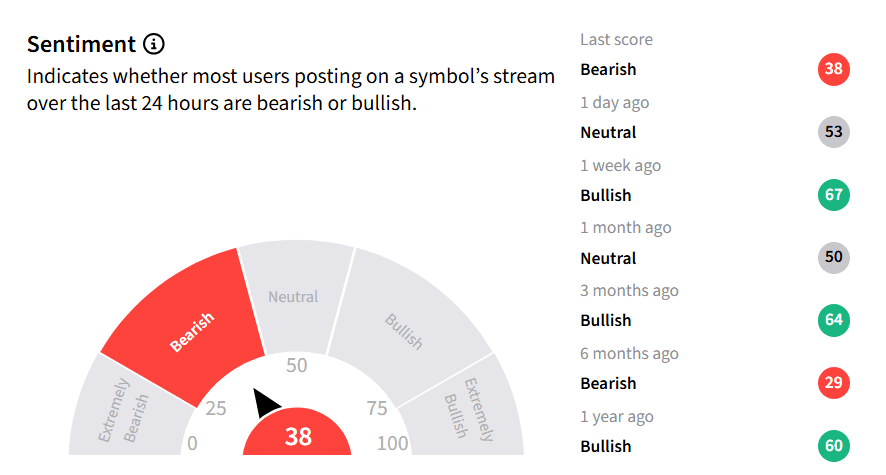
On Stocktwits, retail investors’ sentiment around FSLY stock remained in the ‘bearish’ territory.
So far this year, Fastly shares have nearly tripled, surging over 187%. In comparison, the Amplify Cybersecurity ETF (HACK) and the First Trust Cloud Computing ETF (SKYY), which hold the stock, have risen around 63% and 35%, respectively, over the same period.
Also Read: US Treasury Appoints Judy Shelton As Advisor To Bessent – To Focus On Currency Policy
For updates and corrections, email newsroom[at]stocktwits[dot]com<
