
Western Digital's December-quarter earnings guidance topped estimates, but analysts remain divided over whether strong hard disk drive pricing and elevated margins can persist.
- UBS warned that rising capital expenditures and accelerating industry supply could pressure hard disk drive stock valuations.
- Goldman Sachs said elevated near-term capital spending and potential capacity increases by rivals could pressure WDC’s valuation and shares.
- Western Digital's revenue rose 55% year over year to $4.38 billion, while adjusted EPS surged to $4.64.
Western Digital Corp. (WDC) drew mixed analyst reactions on Friday despite strong fiscal first-quarter earnings and guidance, as concerns over rising capital expenditures and potential increases in industry supply raised questions about the stock’s valuation.
Morgan Stanley raised its price target to $668 from $643 and maintained an ‘Overweight’ rating, saying Western Digital delivered a “strong, pricing-driven beat”. The firm highlighted robust December-quarter earnings guidance, but cautioned “the market continues to be fickle,” according to the note cited by TheFly.
UBS, however, lowered its target to $435 from $470 and kept a ‘Neutral’ rating. Despite acknowledging strong results and supply-constrained demand, the firm warned that rising capital expenditures, accelerating supply and uncertainty over demand beyond the current cycle could lead to further valuation compression.
As of this writing, WDC stock was down more than 4% in Friday’s premarket, on track to extend the previous session’s 6.4% decline. It was also among the top trending tickers on Stocktwits.
Citi Backs Demand Outlook, Goldman Flags Valuation Risks
Citi maintained its ‘Buy’ rating, saying Western Digital's strong quarter reinforced its positive outlook on the hard disk drive (HDD) storage cycle. The firm, however, lowered the price target, citing a reduced peer valuation multiple, per TheFly.
Goldman Sachs said WDC shares could trade modestly lower despite strong quarterly results and guidance well above consensus, as elevated near-term capex and potential capacity increases by competitors could limit valuation multiples.
The firm noted that management continues to expect sustained demand, constrained industry supply, and further growth in revenue, margins, and earnings.
Analyst Firm | Rating | New Target | Previous Target | % Change From Last Close (Oct. 22) |
Baird | Outperform | $900 | $630 | +154.1% |
Morgan Stanley | Overweight | $668 | $643 | +88.6% |
Citi | Buy | $660 | $740 | +86.3% |
Goldman Sachs | Neutral | $540 | $615 | +52.5% |
UBS | Neutral | $435 | $470 | +22.8% |
WDC Forecasts Stronger Revenue Growth And Margins
Western Digital's fiscal first-quarter (Q1) revenue rose 55% year over year to $4.38 billion, beating the $4.14 billion analyst consensus tracked by FiscalAI. Adjusted EPS surged to $4.64, exceeding the consensus estimate of $4.10.
The company forecast fiscal second-quarter (Q2) revenue of $5 billion to $5.2 billion, representing approximately 69% year-over-year growth at the midpoint. The company expects adjusted gross margin of 60% to 61% and adjusted EPS of $5.60 to $6.
Retail Investors’ Sentiment Around WDC Stock
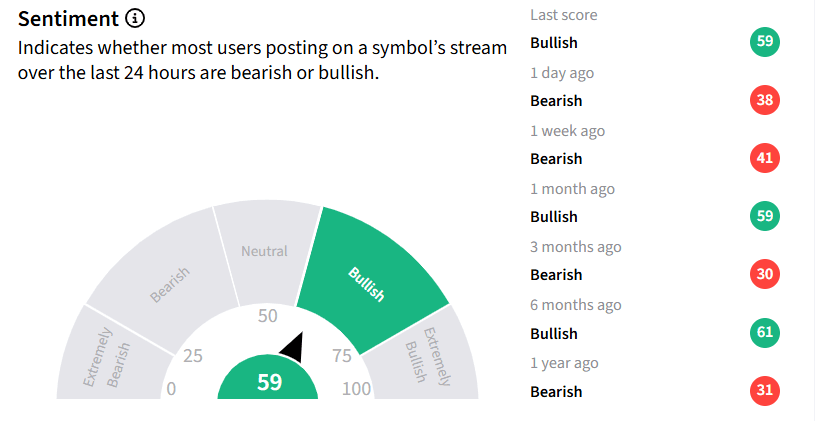
Despite the recent selloff, retail investors’ sentiment around WDC stock flipped to the ‘bullish’ territory amid ‘high’ levels of message volume.
So far this year, WDC shares have surged nearly 89%. By comparison, the iShares AI Innovation and Tech Active ETF (BAI), which holds the stock, has risen over 18% over this period.
See Also: Cathie Wood's ARK Loads Up 38,110 Meta Shares Across 3 ETFs Despite Mounting AI Spending Concerns
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
