
Market analysts highlight Nvidia as an attractive investment opportunity as its valuation drops to historic lows.
- Nvidia is trading at approximately 16.7 times forward earnings, marking its lowest valuation multiple in at least a decade.
- The chipmaker expanded its share repurchase authorization by $150 billion, bringing its total active buyback program to $235 billion through fiscal 2028.
- Holding roughly 97% of the server GPU market, Nvidia continues to see robust sales growth driven by unrelenting demand for AI infrastructure.
Nvidia Corp. (NVDA) presents a compelling buying opportunity for investors after a notable divergence between its underlying business performance and its relative market valuation, Stephanie Link, Chief Investment Strategist at Hightower Advisors, explained in an article published on CNBC.
Despite holding a commanding lead in the global artificial intelligence chip supply chain, the Santa Clara-based semiconductor leader has significantly underperformed broader semiconductor sector benchmarks like the iShares Semiconductor ETF (SOXX) and VanEck Semiconductor ETF (SMH) so far this year.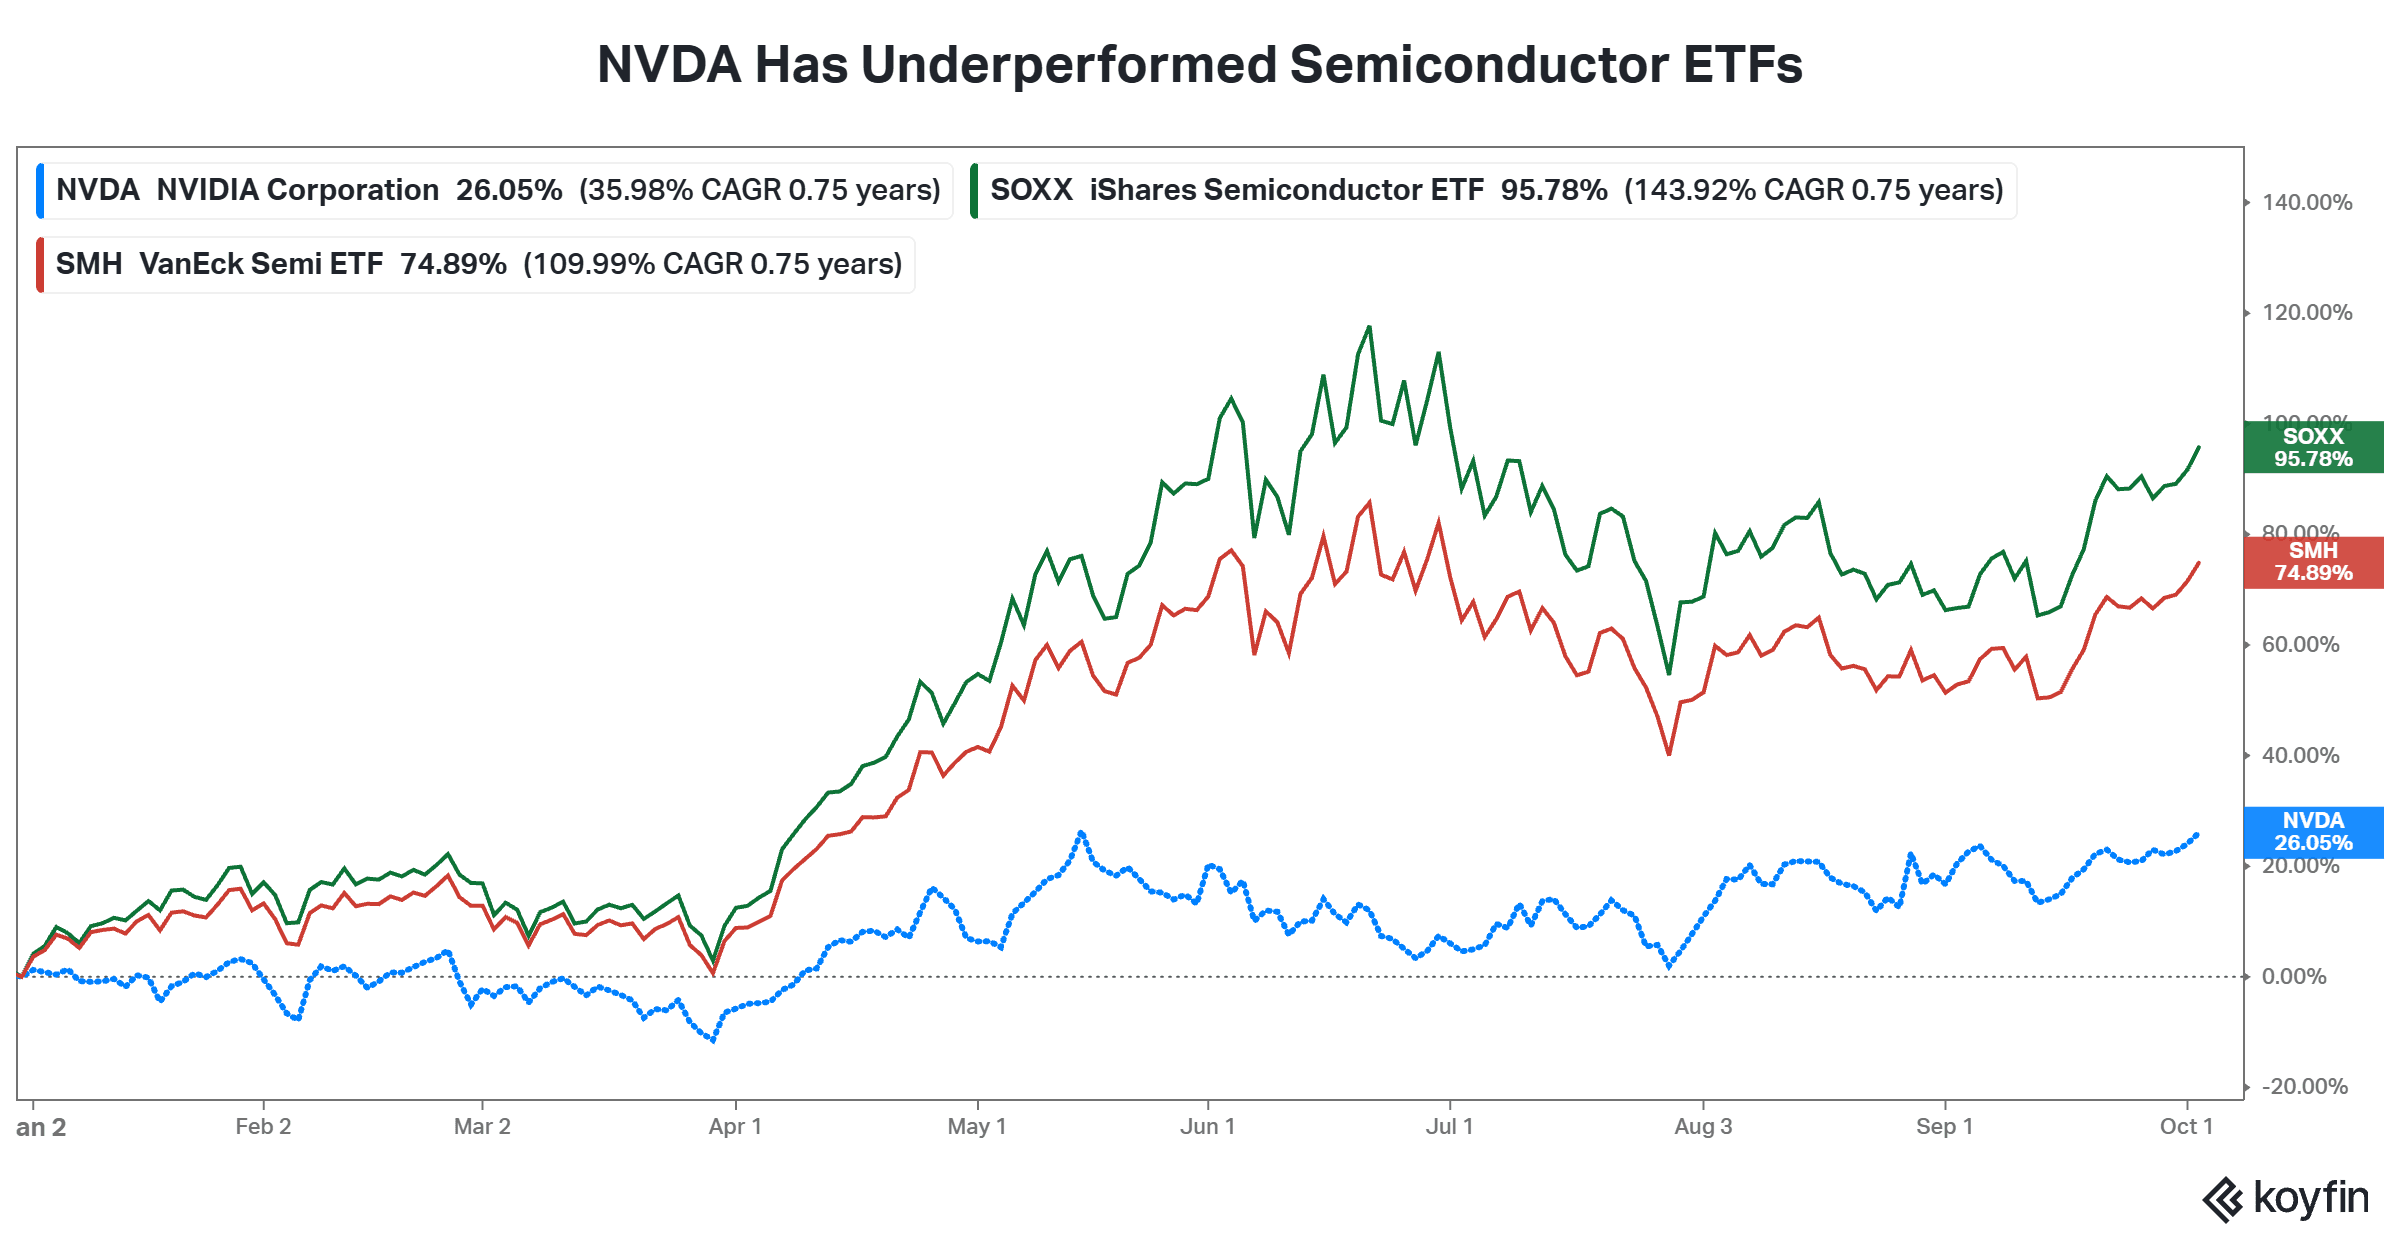
Sector Underperformance Creates Valuation Discount
While Nvidia shares have moved higher year-to-date, they have lagged the broader semiconductor space. The stock has underperformed the Philadelphia Semiconductor Index by 55% year-to-date and 75% over the trailing 12 months.
This price action has significantly compressed Nvidia’s valuation multiple. The stock trades at roughly 19 times forward earnings—a sharp discount compared to its five-year and 10-year historical averages of around 35 times forward earnings.
Link thinks valuation could become even more compelling as earnings grow. “I see Nvidia generating roughly $22 per share in earnings in fiscal 2028. At the current share price, that would put the stock at only about 10.7 times those earnings,” Link wrote in the published article.
Dominant Market Position And Financial Expansion
The disconnect in stock performance comes as Nvidia's operational metrics remain exceptionally strong. The company retains approximately 97% of the server graphics processing unit (GPU) market share. In its most recent quarter, revenue grew 106% year over year, with management forecasting about 70% top-line growth for fiscal 2028 alongside stabilized gross margins near 72%.
To capitalize on its balance sheet strength, Nvidia announced a record $150 billion expansion to its share repurchase program. The authorization brings the remaining capital earmarked for stock buybacks to $235 billion through fiscal 2028, representing about 4% of the company's total market value.
Sector peers have reinforced this trajectory, noting that ongoing capital expenditures for artificial intelligence infrastructure continue to drive sustained tight supply across semiconductor markets.
NVDA Stock: Retail View
Retail sentiment on Stocktwits was ‘bullish’ with ‘normal’ message volumes.
NVDA stock has gained about 25% year-to-date.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
