
In an interview with CNBC, CEO Matt Murphy said the custom silicon target would require roughly 13% of a market he expects to reach $235 billion by 2030.
- Murphy attributed Marvell’s increase in its fiscal 2028 revenue outlook to $20 billion from $18 billion “primarily because of connectivity.”
- He said scale-up optics could become a new growth opportunity when the shift from copper connections to optical technology begins next year.
- The CEO added that the firm has not seen any impact from data center opposition on its market potential or near-term revenue growth.
Marvell (MRVL) shares trended lower in morning trade on Wednesday amid broader market weakness despite a slew of price target hikes from Wall Street, but CEO Matt Murphy remained upbeat after the company’s Investor Day, stating that its custom chip goal for 2031 needs only a small slice of the market.
Nvidia CEO Jensen Huang said in June that Marvell could become a trillion-dollar company. Murphy said Huang’s comment came as a surprise, but acknowledged the potential scale of the opportunity.
“If you apply a multiple to $70 billion to $90 billion four years out, who knows what's possible,” Murphy said. MRVL stock has gained over 230% this year.
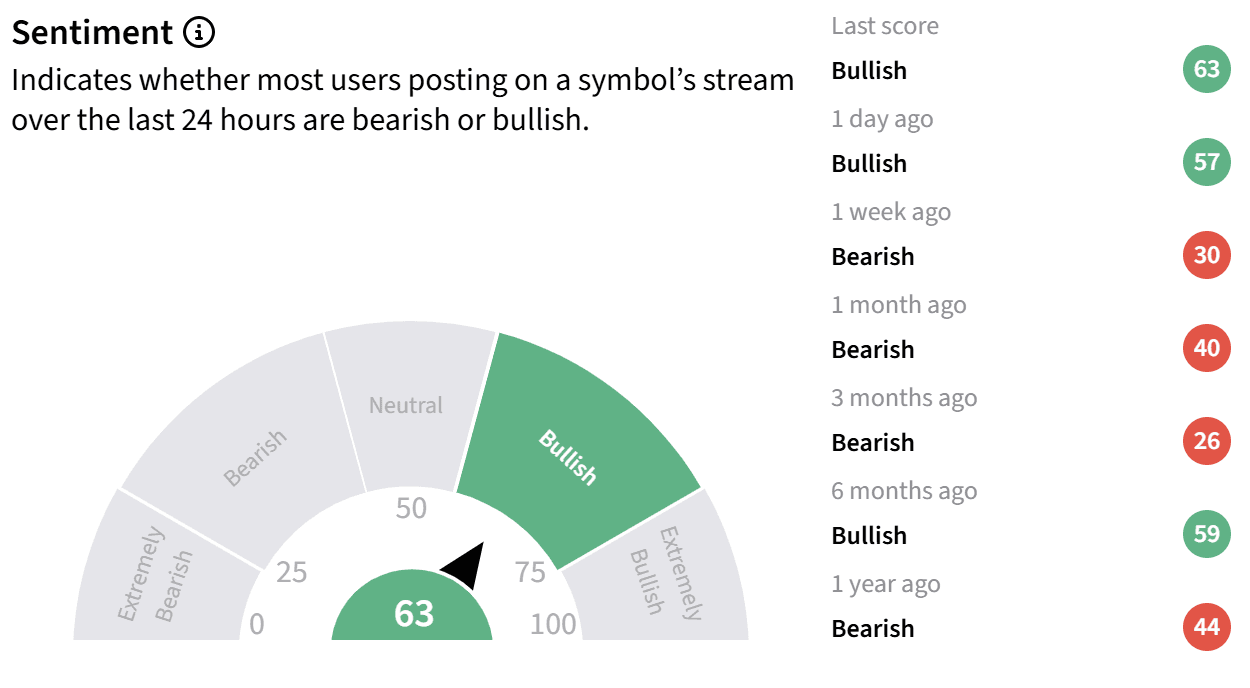
MRVL stock dipped around 1.2% in morning trade, with the S&P 500 trading lower. The SPDR S&P 500 ETF Trust (SPY) tumbled 0.5%, while the Nasdaq-100 tracking Invesco QQQ Trust Series 1 (QQQ) fell around 0.64%. On Stocktwits, retail sentiment around the MRVL stock remained in ‘bullish’ territory over the past day.
The Math Behind Marvell’s Revenue Target
At its investor day, Marvell set a fiscal 2031 revenue target of $70 billion to $90 billion. It put custom chips at about $30 billion of that. Murphy said the custom silicon market will reach $235 billion by 2030, and that the target is a small share of it.
"Somebody pointed out in the meeting, look, if you just divide that by the 235, it's only 13% market share," Murphy said. "And we've got customers there today." He added that custom silicon revenue is already on track to exceed $12 billion in fiscal 2029, making the next stage of growth “not a stretch.”
Marvell Raises Revenue Outlook On Connectivity Demand
Murphy said the company lifted next year's revenue outlook to $20 billion from $18 billion "primarily because of connectivity." His case is that compute and memory have been built out but lack the links to talk to each other. "What you don't want is any GPUs or memory sitting idle," he said.
He singled out scale-up optics, which connect chips inside a rack and are all copper today. The business is "$0 this year," he said, and the shift to optical starts next year. Two quarters ago, he said, he sized it at $300 million. Then it rose. "It's gone up again."
CEO Sees No Near-Term Impact From Data Center Opposition
Murphy said political resistance to data center construction has not affected Marvell’s market opportunity or near-term revenue growth. "We see no impact from any of these externalities right now on our market potential," he said, and none on near-term revenue growth.
He pointed to Marvell’s relationships with the largest hyperscalers, which have been investing in AI infrastructure for years. “We're a semiconductor company. We build world-class chips for a living.”
Marvell’s biggest customers include Amazon Web Services (AWS), Microsoft (MSFT), Alphabet (GOOG, GOOGL), Meta Platforms (META), Nvidia (NVDA), OpenAI and Anthropic.
Wall Street Raises Marvell Price Targets After Investor Day
MRVL stock saw a slew of Wall Street price hikes on Wednesday morning. Oppenheimer and RBC Capital set the highest targets at $425, implying nearly 50% upside from $283.60. Piper Sandler and Needham raised their targets to $400, while Wells Fargo lifted its target to $365 from $310.
| Firm | Rating | Previous PT | New PT | Potential upside/downside |
| Oppenheimer | Outperform | $325 | $425 | 49.90% |
| RBC Capital | Outperform | $360 | $425 | 49.90% |
| Piper Sandler | Overweight | $270 | $400 | 41.00% |
| Needham | Buy | $300 | $400 | 41.00% |
| Craig-Hallum | Buy | $300 | $380 | 34.00% |
| StoneX | Buy | $275 | $375 | 32.20% |
| Wolfe Research | Outperform | $280 | $375 | 32.20% |
| Stifel | Buy | $350 | $370 | 30.50% |
| Wells Fargo | Overweight | $310 | $365 | 28.70% |
| JPMorgan | Overweight | $305 | $360 | 26.90% |
| UBS | Buy | $335 | $350 | 23.40% |
| Cantor Fitzgerald | Neutral | $330 | $350 | 23.40% |
| Morgan Stanley | Equal Weight | $268 | $300 | 5.80% |
| Goldman Sachs | Neutral | $220 | $270 | −4.8% |
Source: Curated from TheFly, ranked in descending order of price targets. Upside calculated from MRVL stock price on October 7 as of 10:30 a.m. ET.
Analysts cited growth opportunities across custom silicon, optical connectivity and AI infrastructure.
UBS said Marvell’s long-term outlook could prove conservative, pointing to custom compute, interconnect opportunities, operating leverage and share buybacks. JPMorgan said it saw a “credible path” to $35 in earnings per share by 2030, while RBC said the company’s growth targets were achievable.
However, not all analysts were fully convinced. Morgan Stanley raised its target to $300 from $268 but retained an ‘Equal Weight’ rating, stating it was uncertain Marvell needed to set the bar so high. Cantor Fitzgerald and Goldman Sachs also maintained ‘Neutral’ ratings despite raising their targets to $350 and $270, respectively.
Read also: Nvidia Gets Another AI Demand Signal As Foxconn Sales Hit Record High – Apple Faces Holiday Test
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
