
According to The Fly, Citi raised its price target on Lockheed Martin to $706 from $691 and maintained a ‘Buy’ rating, citing increased confidence in accelerating momentum across its segments.
- RBC Capital raised its price target on Lockheed Martin to $600 from $550 while maintaining a ‘Sector Perform’ rating, citing strong bookings and encouraging initial commentary on 2027.
- Barclays also raised its Price Target to $560 from $554 and maintained an ‘Equal Weight’ rating.
- According to Koyfin data, 12 of the 23 analysts covering LMT rate it ‘Hold’, while 10 have a ‘Buy’ or ‘Strong Buy’ rating.
Lockheed Martin (LMT) shares were in focus on Friday after multiple analysts raised their price targets on the stock following better-than-expected Q3 results and increased full year 2026 outlook.
According to The Fly, UBS said Lockheed Martin’s long-term growth narrative is not priced into the stock, while RBC cited very strong bookings and encouraging initial commentary on FY2027 as it raised its price target to $600 from $550 and kept a ‘Sector Perform’ rating.
LMT shares traded 2% high at the time of writing.
According to Koyfin data, 12 out of 23 analysts covering the stock rate it ‘Hold’ whereas 10 rate it ‘Buy’ or ‘Strong Buy’.
Analysts Raise Price Targets On LMT
UBS raised its price target on Lockheed Martin to $692 from $653 and maintained a ‘Buy’ rating. The firm also noted that Lockheed’s growth had accelerated for two consecutive quarters, reaching 11% in the latest quarter.
Citi analyst John Godyn raised his price target to $706 from $691 and maintained a ‘Buy’ rating, according to The Fly. The firm cited increased confidence in accelerating momentum across Lockheed Martin’s segments.
Barclays analyst Anthony Valentini raised his target to $560 from $554 and maintained an ‘Equal Weight’ rating.
Q3 Earnings Highlights
Lockheed Martin reported third-quarter revenue of $20.71 billion, up 11% year over year and above the analyst estimate of $20.46 billion, while diluted earnings-per-share (EPS) rose to $7.97 from $6.95, beating the $7.52 estimate, according to estimates compiled by Fiscal AI.
The company also raised its 2026 revenue outlook to $80 billion–$82 billion and EPS forecast to $30.35–$30.75, marking its second consecutive quarterly guidance increase.
Lockheed Martin’s backlog reached a record $292 billion, up 27% from the previous quarter, with a book-to-bill ratio of 4x, meaning orders significantly exceeded sales during the quarter.
The company raised its full-year free cash flow outlook to $7.8 billion–$8.0 billion, up from its previous forecast of $7.0 billion–$7.2 billion.
F-35 Framework Still Awaits Formal Contract
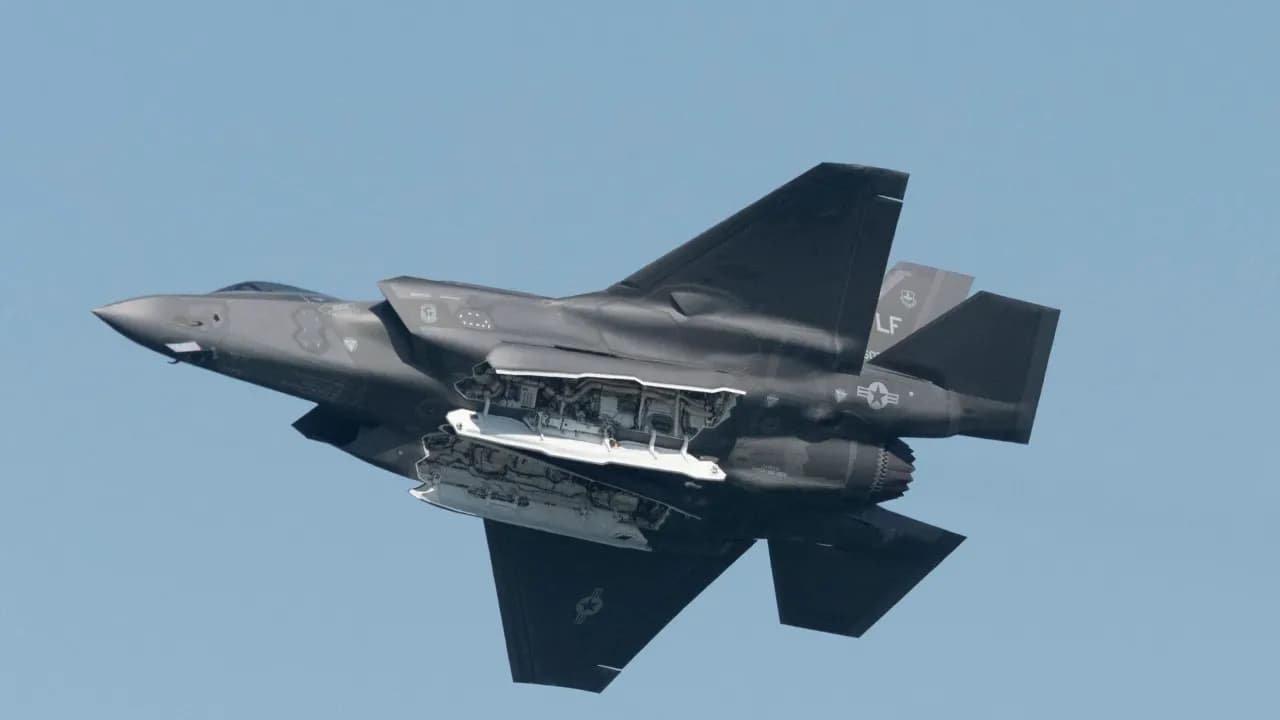
Separately on Thursday, Lockheed Martin and the Department of War announced a 10-year framework covering 850 U.S. F-35 aircraft, associated initial spare parts, 10 years of modification kits and sustainment, as well as international customer orders across Lots 21–30. Production is planned to continue at 156 aircraft annually across U.S. and international customers.
The framework is not yet a finalized contract. A formal award is subject to multiyear contracting authority and associated appropriations, after which Lockheed Martin and the F-35 Joint Program Office can finalize contract terms, pricing and schedules. Lockheed Martin said the proposed arrangement is intended to improve production planning and supply-chain stability, with expected savings from long-term pricing and volume discounts.
How Retail Views LMT
On Stocktwits, retail sentiment remained in the ‘bullish’ territory amid ‘high’ message volumes in the past 24 hours.
LMT shares have gained over 23% year-to-date.
Also read: Iovance’s Melanoma Therapy Shows Promising 4-Year Data – Retail Says Acquisition Imminent Before 2027-End
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
