
Morgan Stanley cut its price target to $14 from $17, maintaining an 'Equal Weight' rating, citing business complexity, uneven international growth and slower U.S. momentum, according to The Fly.
- BofA raised its target to $20 from $19 and maintained a 'Buy' rating, highlighting 32% year-over-year growth in transaction margin dollars to $371 million.
- JPMorgan cut its price target to $17 from $18 while maintaining a 'Neutral' rating, according to The Fly.
- Fourteen out of 25 analysts covering the stock rate it ‘Hold’, while 11 rate it ‘Buy’ or ‘Strong Buy’, according to Koyfin.
Klarna Group plc (KLAR) shares saw multiple analysts revise their price targets following the company's third-quarter results, offering differing views on its growth outlook and execution.
According to The Fly, Morgan Stanley analyst James Faucette lowered his price target on Klarna to $14 from $17 while maintaining an 'Equal Weight' rating.
The analyst argued that Klarna's business complexity, uneven international growth and slower U.S. momentum ‘warrant a persistent valuation discount’ to Affirm (AFRM), until Klarna's execution durably improves. Morgan Stanley applied a lower valuation multiple to its estimates for Klarna, according to The Fly.
KLAR shares traded over 3% higher at the time of writing.
KLAR’s Q3 Highlights
Klarna reported better-than-expected third-quarter revenue of $1.009 billion, up 12% year over year, while its net loss narrowed to $65 million from $95 million a year earlier. GMV rose 10% to $36.1 billion, driven by 24% growth in the U.S.
Transaction margin dollars increased 32% to $371 million, while adjusted operating income improved to $21 million from a $14 million loss in the year-ago quarter.
The company reiterated its FY2026 outlook, forecasting revenue of $4.08 billion to $4.16 billion and GMV of $149 billion to $151 billion.
Analysts Offer Mixed Views On Klarna's Outlook
BofA analyst Matthew O'Neill raised his price target to $20 from $19 and maintained a 'Buy' rating, citing a rise in transaction-margin dollars.
The analyst noted that transaction-margin dollars increased 32% year over year to $371 million, compared with 11.7% revenue growth. BofA now forecasts fiscal 2026 revenue of $4.184 billion and transaction margin dollars of $1.639 billion, according to The Fly.
Meanwhile, BMO Capital lowered its price target on the stock to $13 from $14 and maintained a 'Market Perform' rating, according to The Fly. The analyst said softer fourth-quarter guidance and strategic shifts raised questions despite a sound third-quarter performance.
However, management's comments on the earnings call helped ease initial concerns, with the company pointing to conservatism in its guidance and quarter-to-date trends running ahead of guidance, The Fly reported.
JPMorgan also cut its price target to $17 from $18 while maintaining a 'Neutral' rating, according to The Fly. The analyst cited macroeconomic headwinds in Europe as the reason for Klarna's reduced second-half outlook, despite third-quarter results coming in ahead of expectations.
Fourteen out of 25 analysts covering the stock rate it ‘Hold’, while 11 rate it ‘Buy’ or ‘Strong Buy’, according to Koyfin. Their 12-month price targets range from $13 to $38.30, with an average of $19.24.
How Retail Views KLAR
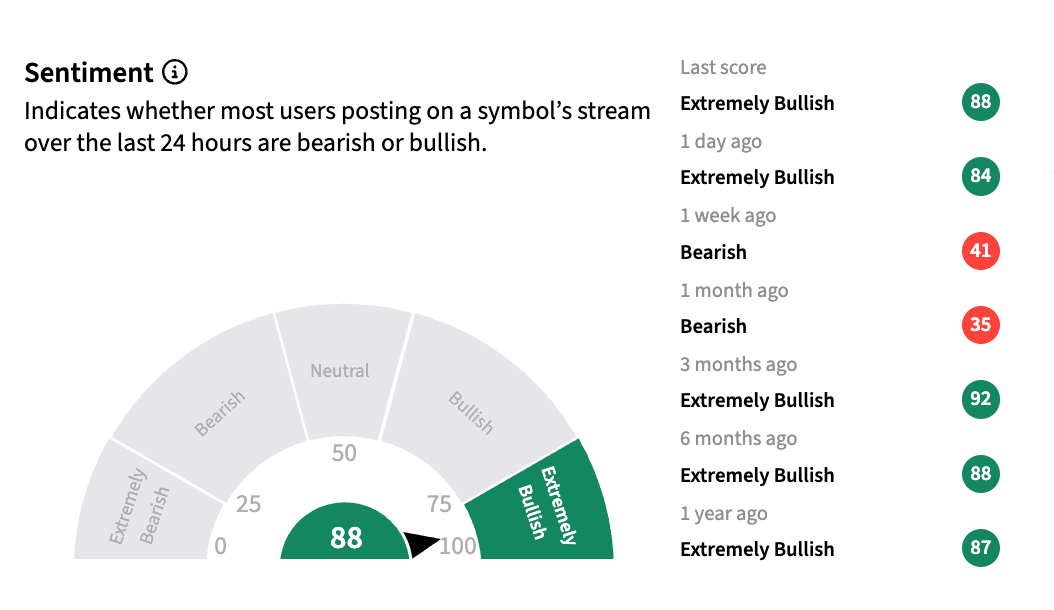
On Stocktwits, retail sentiment around KLAR stock remained in the ‘extremely bullish’ territory over 24 hours amid ‘extremely high’ message volumes.
KLAR shares have dropped over 48% year-to-date.
Also read: SpaceX Will Need Substantial Cell Tower Infrastructure To Build Mobile Network, Citi Says — Firm Sees Nearly 94% Upside In SPCX Stock
For updates and corrections, email newsroom[at]stocktwits[dot]com.<








