
Williams Trading analyst Sam Poser downgraded DICK'S Sporting Goods to ‘Sell’ from ‘Hold’ with a price target of $120, down from $130, according to The Fly.
- The firm said DICK’S Sporting Goods’ fiscal 2027 outlook is "about to get worse,” according to The Fly.
- Thirteen out of 28 analysts covering the stock rate it ‘Buy’ or ‘Strong Buy’, while 13 rate it ‘Hold’ and two rate it ‘Sell’ or ‘Strong Sell’, according to Koyfin.
- The retailer is set to report its third-quarter results on Nov. 24, with analysts expecting adjusted earnings of $1.42 on revenue of approximately $5.08 billion, according to Fiscal.ai.
DICK'S Sporting Goods Inc. (DKS) drew investor attention on Thursday after Williams Trading downgraded the stock, citing concerns about Foot Locker's performance and expected cuts to Brand Jordan allocations.
According to The Fly, Williams Trading analyst Sam Poser lowered his rating to ‘Sell’ from ‘Hold’ and cut his price target to $120 from $130, implying approximately 15.1% downside potential from the current levels. The firm believes DICK'S Sporting Goods’ fiscal 2027 outlook is "about to get worse”, The Fly reported.
DKS shares traded 2.8% lower at the time of writing.
Thirteen out of 28 analysts covering the stock rate it ‘Buy’ or ‘Strong Buy’, while 13 rate it ‘Hold’ and two rate it ‘Sell’ or ‘Strong Sell’, according to Koyfin. Their 12-month price targets range from $99 to $205, with an average of $158.34.
Foot Locker And Nike's Jordan Business Pose Risks
Williams Trading expects weak back-to-school traffic and elevated inventory levels at Foot Locker to leave DICK'S Sporting Goods at risk of either missing its fiscal 2026 guidance or reporting results at the low end of its outlook, according to The Fly.
The firm also expects Nike (NKE) to reduce Brand Jordan allocations by 15% to 20% in the first quarter of fiscal 2027 and 40% to 50% for the year. Williams estimates that Jordan accounts for approximately 25% of Foot Locker's annual U.S. revenue, The Fly reported.
The firm also described Foot Locker as a continued distraction for DICK'S Sporting Goods and said the Jordan-related headwinds would be difficult to overcome, according to Investing.com.
Separately, on Nov. 13, Wells Fargo raised its price target on the stock to $195 from $185, maintained an ‘Overweight’ rating and said it expected Q3 results to come in above lowered expectations, according to The Fly. The firm also said it was a buyer ahead of the earnings report.
When Is DKS Reporting Its Q3 Earnings
DICK’S Sporting Goods is scheduled to report its fiscal third-quarter 2026 results on Tuesday, Nov. 24, before the market opens. Analyst estimates currently point to earnings per share of $1.42 and revenue of approximately $5.08 billion, according to Fiscal.ai.
Following its second-quarter results, the company lowered its full-year 2026 outlook, citing increasingly promotional conditions across portions of the athletic footwear and apparel marketplace. DICK'S Sporting Goods now expects full-year 2026 net sales of $21.9 billion to $22.2 billion, operating income of $1.45 billion to $1.55 billion, and diluted earnings per share of $10.94 to $11.94.
How Retail Views DKS
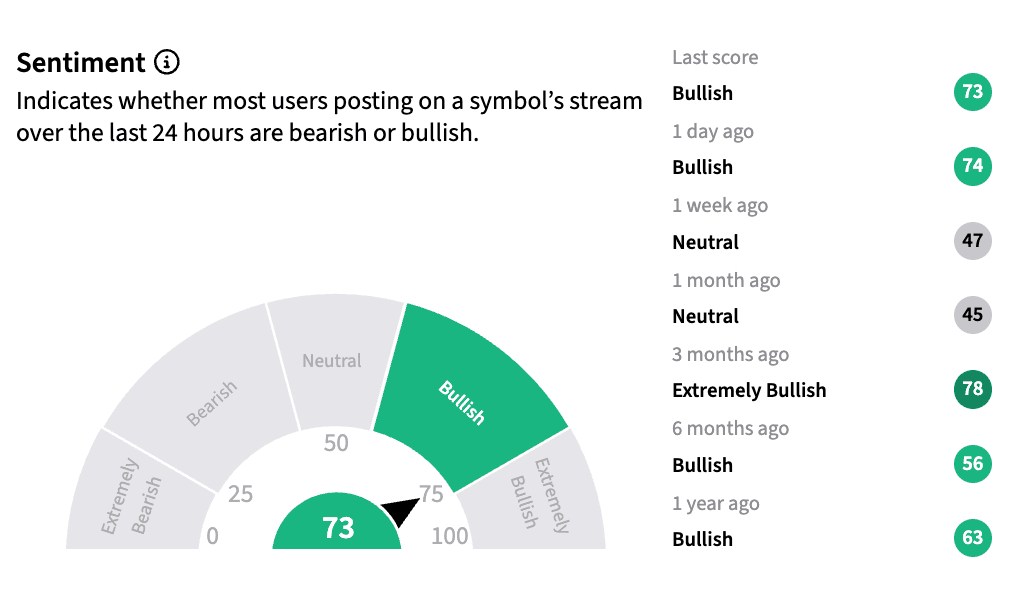
Retail sentiment surrounding the stock on Stocktwits turned ‘extremely bullish’ from ‘bullish’ over the past 24 hours, amid ‘high’ message volumes.
DKS shares have fallen approximately 27% year to date.
Also read: ASTS Stock Gets A Breather After Relentless Sell-Off: B. Riley Says Launch Delays, Funding Risks Are Already Priced In
For updates and corrections, email newsroom[at]stocktwits[dot]com.<









