
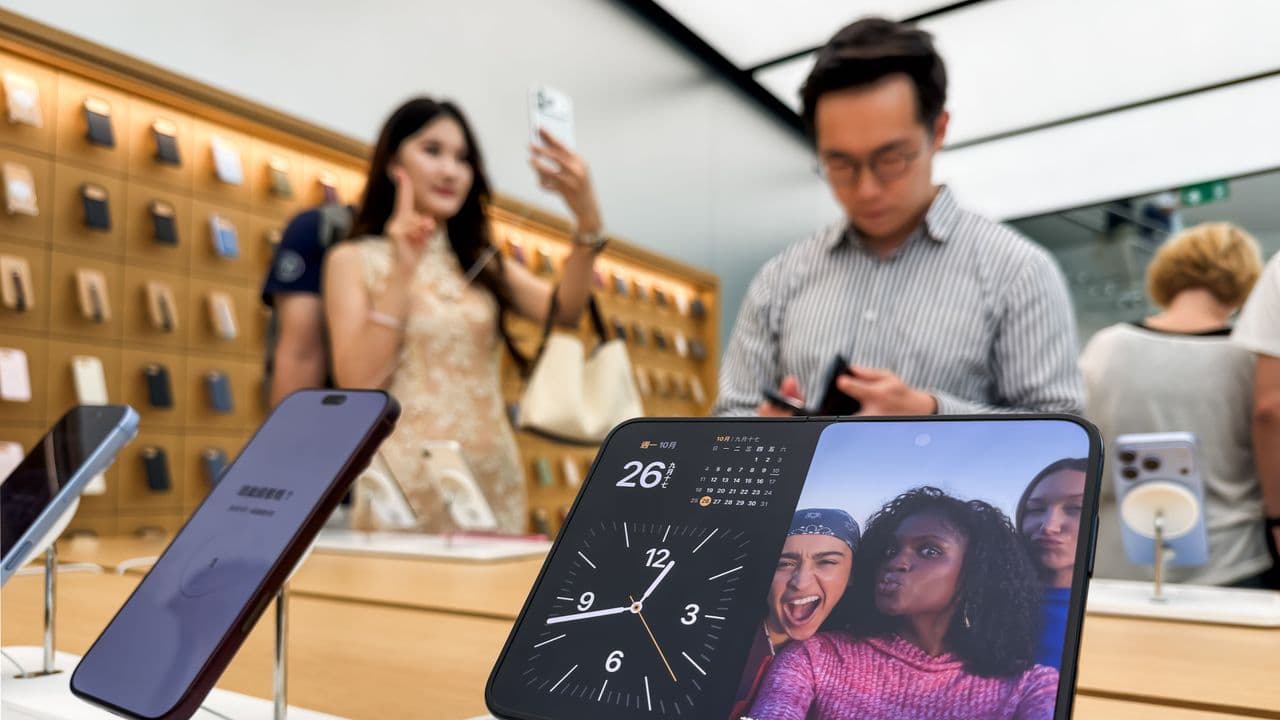
Apple is likely to face questions about hinge and screen issues with its new iPhone Duo, even as the device’s longer wait times point to strong demand.
- Apple’s Q4 revenue is expected to rise 11% to $113.35 billion, the slowest growth in the last four quarters, per Koyfin.
- Apple’s new touchscreen MacBooks, iPhone Duo, and HomeView, started shipping in the company’s current fiscal first quarter.
- Retail sentiment for AAPL dipped over the past week and was ‘extremely bearish’ on Monday, even as the stock hit an all-time high last week.
Apple’s (AAPL) fiscal fourth-quarter report, due after Monday’s market close, is significant for several reasons. It marks the first earnings report under new CEO John Ternus and follows the company's unveiling of a foldable iPhone and touchscreen MacBooks in a major product shift, with the gadgets drawing mixed reviews.
Also in the backdrop are elevated memory prices, with investors and analysts looking for comments on how Apple plans to manage rising component costs without putting further pressure on demand.
Apple would also face questions around the hinge and screen issues with its new iPhone Duo, even though the device’s longer wait times point to strong demand.
The buzz around its new devices, coupled with Apple’s decision to avoid the massive AI spending spree by other Big Tech companies, helped propel the stock to record highs last week, taking its market capitalization past Nvidia’s at the time.
The touchscreen MacBooks and iPhone Duo, as well as the newly announced HomeView, started shipping in the company’s current fiscal first quarter and as such their sales expectations will be reflected in the forecast.
Apple’s Q4 Report: Analysts’ Expectations
“We’ll be watching iPhone revenue, particularly guidance for the December quarter, which reflects the majority of the new iPhone release (including the new Duo),” Morningstar said in a report.
“We expect strong year-over-year growth but higher prices from memory inflation, and the impact on unit prices is the key metric. Prices and the impact across Mac and iPad will be notable too, but iPhone is the overwhelming driver of the business.”
It said that AAPL was “moderately overvalued” and the market was “a bit overenthusiastic about iPhone shipment growth” in the longer term.
Apple’s Q4 revenue is expected to rise 11% to $113.35 billion, the slowest growth in the last four quarters, according to estimates from Koyfin. Adjusted profit is seen rising 8% to $1.99 per share.
IPhone sales are projected to climb about 15% to $56.54 billion, according to estimates from LSEG-Reuters, while the services business is expected to grow almost 10% to $31.56 billion, its slowest pace in more than three years.
Last week, Bank of America removed Apple from its “US 1 List,’ a compilation of the firm’s top stock picks. The view on the Street is mixed: 24 of 43 analysts rate AAPL ‘Buy’ or higher, 13 rate it ‘Hold’ and six rate it ‘Sell’ or lower, per Koyfin.
Retail View On AAPL
On Stocktwits, the retail sentiment for AAPL dipped over the past week and was ‘extremely bearish’ on Monday.
“$AAPL it may buck the trend and not dump after earnings; who knows ; if see a good pop tomorrow and into the earnings report / call I’ll be selling some; honestly over extended; long term though we will always go higher,” said a trader, summarizing the broader view on the timeline.
“I am typing this bearish message on a broken duo screen… short this trash,” another wrote, poking fun at reported screen issues with the new iPhone.
AAPL shares are up 27% year to date, as of their last close, outperforming tech giants such as Microsoft, Alphabet, Meta and Amazon.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
