
BofA raised its earnings estimates after Synopsys laid out a financial framework through 2030 that calls for faster growth and expanding margins, according to TheFly
- BofA raised its fiscal 2027 and 2028 pro forma EPS estimates by 7% and 16%, respectively.
- Synopsys expects fiscal 2027 revenue of $11.1 billion to $11.2 billion, representing roughly 15% growth at the midpoint.
- The company is targeting a non-GAAP operating margin of about 50% by fiscal 2030 and plans roughly $1 billion in near-term share repurchases.
Bank of America raised its price target on Synopsys Inc. (SNPS) by $100 after the chip-design software company laid out new financial targets at its 2026 Investor Day.
According to TheFly, Analyst Vivek Arya maintained a ‘Buy’ rating on SNPS stock and raised the target to $600 from $500. The firm said Synopsys’ targets imply roughly a 23% compound annual growth rate (CAGR) in pro forma earnings per share (EPS) from fiscal 2026 through 2030, “well ahead” of consensus expectations.
BofA subsequently raised its fiscal 2027 and fiscal 2028 pro forma earnings estimates by 7% and 16%, respectively, per TheFly.
At the time of this writing, SNPS stock traded more than 2% higher in Thursday’s premarket.
Synopsys Targets Higher Growth, Wider Margins
Synopsys’ long-term framework calls for revenue to grow at roughly a 15% compound annual rate from fiscal 2026 through 2030, while non-GAAP EPS are expected to grow in the mid-20% range.
For fiscal 2027, the company expects revenue between $11.1 billion and $11.2 billion, with the midpoint representing about 15% growth. It is also targeting a non-GAAP operating margin of roughly 44% next year, rising to about 50% by fiscal 2030.
Within the business, Synopsys expects electronic design automation revenue to grow at least 13% annually through 2030, simulation and analysis revenue by at least 10%, and Design IP by at least 17%.
KeyBanc Says Investor Day Addressed Bear Concerns
KeyBanc also turned more constructive, raising its price target to $605 from $600 while maintaining an ‘Overweight’ rating.
According to TheFly, the firm highlighted better-than-expected initial fiscal 2027 guidance, higher long-term growth targets for electronic design automation and intellectual property, and meaningful operating-margin expansion.
The analyst also pointed to Synopsys’ explanation of the secular growth drivers across its portfolio, as well as incremental partnerships with Amazon Web Services and OpenAI.
KeyBanc said the event addressed many of the concerns raised by bears and reinforced its view that electronic design automation remains a compelling opportunity at current levels, per TheFly.
Cash Generation Supports Buybacks
Synopsys is also targeting free cash flow growth in the mid-20% range over the fiscal 2026-to-2030 period.
After investing in the business, the company said it expects to return up to 50% of free cash flow to shareholders through share repurchases. Synopsys intends to buy back approximately $1 billion of stock over the coming months, subject to market conditions.
The updated framework comes as Synopsys positions its design and simulation portfolio around what it describes as the expansion of digital and physical AI and the broader shift toward AI-powered engineering.
What Retail Thinks About SNPS Stock
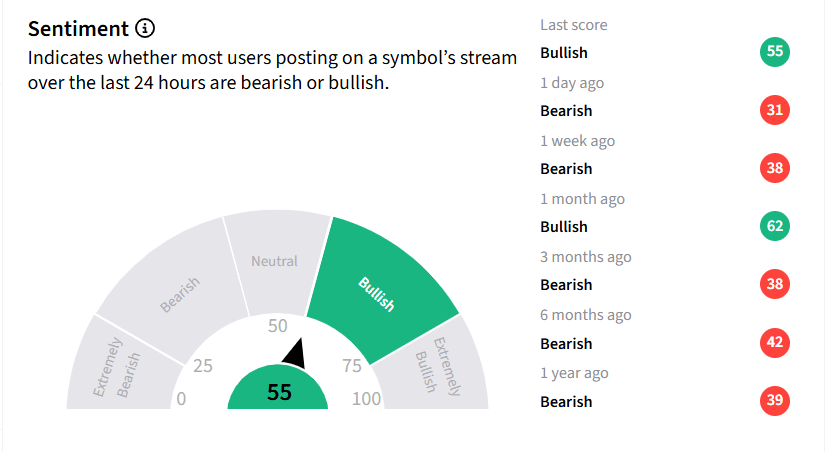
On Stocktwits, retail investor sentiment surrounding SNPS stock flipped to ‘bullish’ territory amid high message volume.
So far this year, Synopsys stock has fallen more than 9%. In comparison, the Invesco QQQ Trust, Series 1 ETF (QQQ), which holds both stocks, has risen over 2% during this period.
See Also: Micron's Blowout Q4 Pushes Memory Peak Further Out – But Investors Still See A Cycle Risk
For updates and corrections, email newsroom[at]stocktwits[dot]com<
