
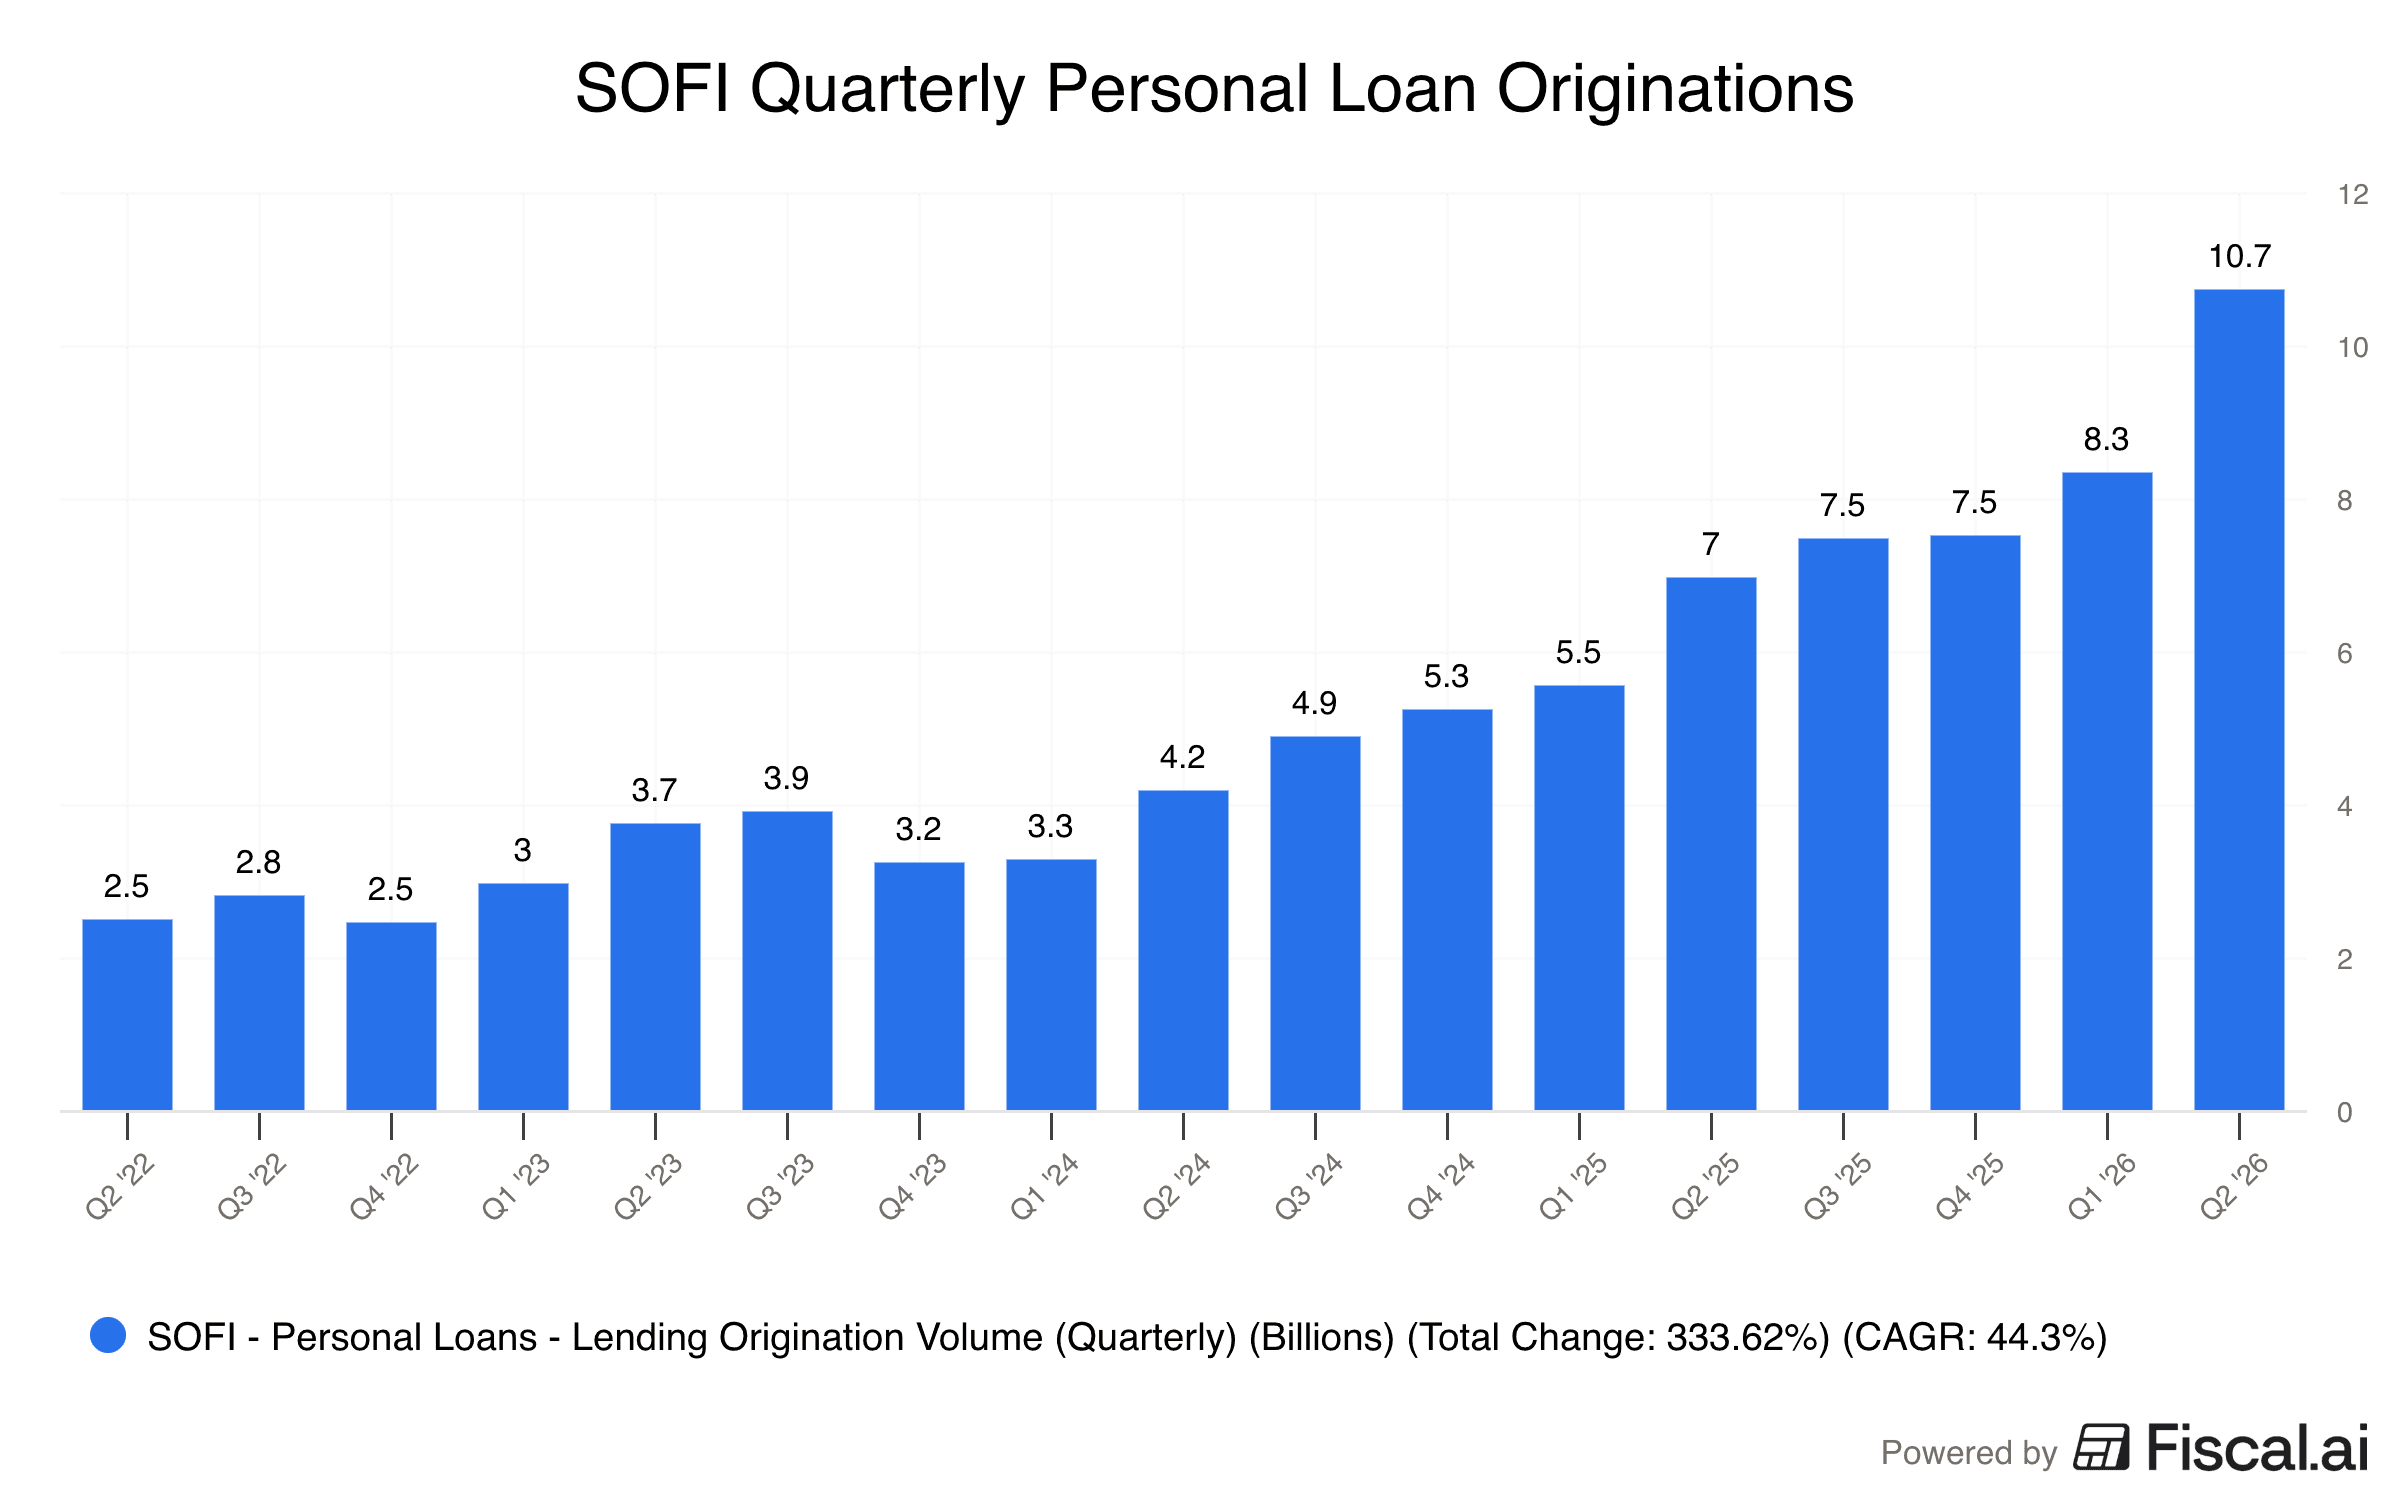
In the second quarter of 2026, SoFi Technologies posted a record personal loan origination of $10.7 billion, a growth of nearly 53% from the prior year’s comparable quarter.
- Northwise Project said in a post on X that it likes the “flexibility” SoFi’s growing loan platform business provides.
- The firm said that the growth opportunity is attractive because SoFi can serve more borrower demand through partners, but added that it is important to watch whether the partners keep buying at attractive terms for the company.
- In a separate X post, Northwise Project highlighted the fintech firm’s customer opportunity, noting that existing members opened 51% of new products in Q2, up 35% from a year earlier.
SoFi Technologies Inc. (SOFI) has had a lackluster 2026, plunging more than 40% amid sticky inflation, Federal Reserve rate hikes, and aggressive reinvestment plans that weighed on its stock.
However, research firm Northwise Project sees an attractive growth opportunity in the fintech firm, especially in its Loan Platform Business.
SOFI’s Personal Loan Originations Have Been Growing
In the second quarter of 2026, SoFi Technologies posted a record personal loan origination of $10.7 billion, a growth of nearly 53% from the prior year’s comparable quarter, taking its total loan originations to an all-time high of $14.8 billion.
Northwise Project said in a post on X that it likes the “flexibility” SoFi’s growing loan platform business provides. “SoFi can retain a loan and earn interest over time, or distribute it and earn fees while using less balance-sheet capacity,” it said.
The research firm added that loan retention also means funding the principal, absorbing credit losses, and supporting the asset with capital, while distribution changes the commitment, even though servicing duties and other contractual obligations can remain.
“This is why comparing an annual lending spread with an upfront distribution fee tells you very little about which route creates more value. You need the life of the loan, expected losses, funding costs and equity required,” it said.
“The growth opportunity is attractive because SoFi can serve more borrower demand through partners. The constraint to watch is whether those partners keep buying at terms that leave enough economics for SoFi,” Northwise Project added.
How SoFi’s ‘Everything App’ Can Turn Into A Business Opportunity
In a separate X post, Northwise Project highlighted the fintech firm’s customer opportunity.
The research firm noted that in Q2, existing members opened 51% of new products, up 35% from a year earlier. That measures the source of new products, not the percentage of members using several products.
Alongside record product additions, the company said that it also saw a clear inflection point in products per member, driven primarily by SoFi Plus.
“The opportunity we see in SoFi $SOFI starts with becoming the account a customer actually uses on payday. That deposit can fund lending. Spending can generate interchange. Savings, investing, and borrowing give SoFi more chances to earn from a relationship it has already acquired,” Northwise Project said.
The firm said the distinction matters because a free account opening is easy to celebrate, but a customer who keeps a balance, spends, and returns for another service is more economically useful.
“We are bullish on SoFi's ability to deepen those relationships. The test is whether the additional earnings exceed the incentives and benefits required to keep the customer. That is where the everything-app ambition becomes a business,” it said.
SOFI Stock: Retail Stance
On Stocktwits, retail sentiment around SOFI stock slipped from ‘neutral’ to ‘bearish’ over 24 hours amid ‘normal’ message volumes.
One user said, “$SOFI It is worth noting that since obtaining its national bank charter, SoFi is much more resilient to rate hikes than it used to be. Higher rates allow its banking arm to widen its net interest margin (the gap between what it charges on loans and what it pays out on deposits). It also helps them attract cash-rich members to their high-yield checking and savings accounts.”
SoFi Technologies obtained its bank charter in 2022.
Another user said, “$SOFI being at 15s just ahead of the quiet period means that Wall Street will most likely push it to the year's lows. The $14 handle will be the place to close cover calls and use proceeds to buy more. But a pop to 19 could happen at any moment too with a headline Iran, end of Russia Ukraine war etc.”
SoFi Technologies will post its third-quarter (Q3) results on Oct. 27.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
