
FMC expects Q3 revenue between $65 million and $125 million, compared with its previous forecast of $840 million to $900 million, excluding India.
- The company also expects an adjusted EBITDA loss of $510 million to $565 million in Q3, compared to its earlier forecast of a $120 million to $140 million profit.
- Citi said FMC’s path to being free cash flow positive is ‘increasingly uncertain.’
- RBC Capital said FMC’s full-year 2026 targets are at risk.
Shares of FMC Corporation (FMC) tumbled more than 33% on Thursday after the agricultural chemicals maker significantly cut its third-quarter earnings outlook amid inventory pressure and competition from cheaper generic products.
The update also raised concerns about peer Corteva (CTVA), with Citi expecting some negative fallout for the stock, although it sees Corteva as less exposed to generic competition.
CTVA shares were down more than 4% at the time of writing.
FMC Slashes Revenue, Swings To Massive Loss
FMC now expects third-quarter (Q3) revenue between $65 million and $125 million, compared with its previous forecast of $840 million to $900 million, excluding India. The company also expects an adjusted earnings before interest, taxes, depreciation and amortization (EBITDA) loss of $510 million to $565 million, compared to its earlier forecast of a $120 million to $140 million profit.
FMC said the forecast includes an estimated impact of $625 million to $675 million from lowering prices on select products in key markets and modifying its selling and pricing model in the United States.
FMC’s Inventory Issues In Focus
FMC is facing slower-than-expected demand in key markets while distributors are holding higher-priced FMC products. The inventory was purchased under different cost structures and competitive conditions, the company said.
Rapid market price declines, driven in part by increased generic competition, have widened the valuation gap between the affected inventory and current market prices, making it difficult to sell the inventory.
FMC is considering two steps to address the bottleneck. The company is taking “comprehensive commercial actions” in Brazil, Argentina, the United States and Canada to lower the price of select products. It will also change its selling and pricing model in the United States.
The company expects to discuss potential changes to its debt agreements with lenders and provide an updated outlook when it reports earnings on October 29.
Citi Says Corteva Not As Exposed To Generic Pressure
Citi said that while FMC’s actions could improve competitiveness, it sees “a challenging picture for the balance sheet into 2027,” with FMC’s path to free cash flow positivity “increasingly uncertain.”
The firm expects a sharp negative reaction in FMC shares but “a modest negative reaction” in Corteva shares, saying Corteva’s exposure to generic pressure is modest by comparison.
RBC Capital added that the change in Q3 outlook puts FMC’s full-year 2026 targets at risk and is likely adding pressure on Corteva’s stock.
Earlier this month, Corteva completed the spin-off of its seed business, Vylor (VYLR), with the company completely focused on crop protection. Corteva is targeting $8.4 billion to $8.7 billion in annual sales by 2029.
Retail's Take
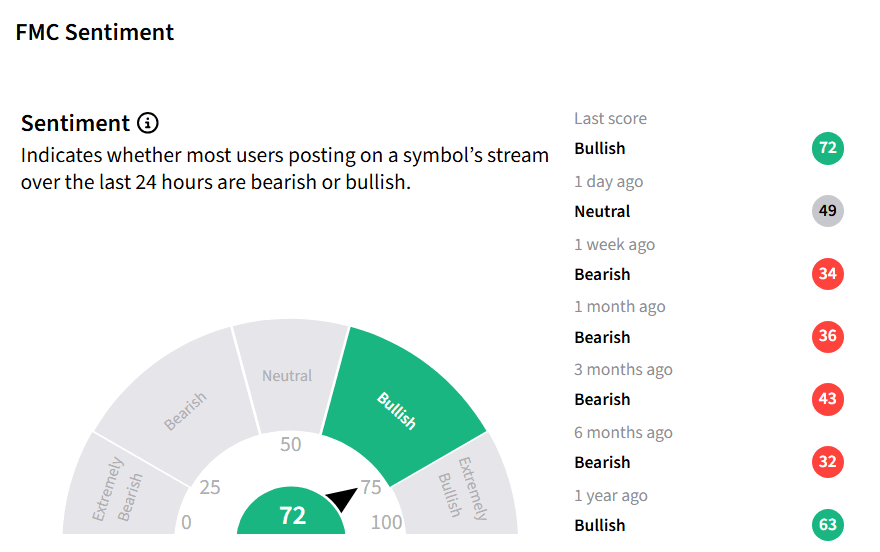
Despite the crash, retail sentiment on Stocktwits surrounding FMC turned ‘bullish’ from ‘neutral’ a day earlier, amid a 300% jump in message volumes.
One user said that while FMC’s actions could help the company survive bankruptcy, it would not become a $20 stock again.
View this Stocktwits post
FMC shares are down 62% so far in 2026.
Also read: SpaceX Expands Footprint With United Airlines Days After AAL Rollout – Starlink’s Now Available On Nearly Half Its Flights
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
