
Carnival raised its 2026 profit outlook after record Q3 results and said about half of its 2027 inventory is already booked at record occupancy and prices.
- Customer deposits rise 7% to a record $7.6 billion, even with little change in capacity.
- A $131 million hit from fuel and currency is partly offset by lower fuel use and cost improvements.
- Morgan Stanley raises its price target to $32.50 from $31.
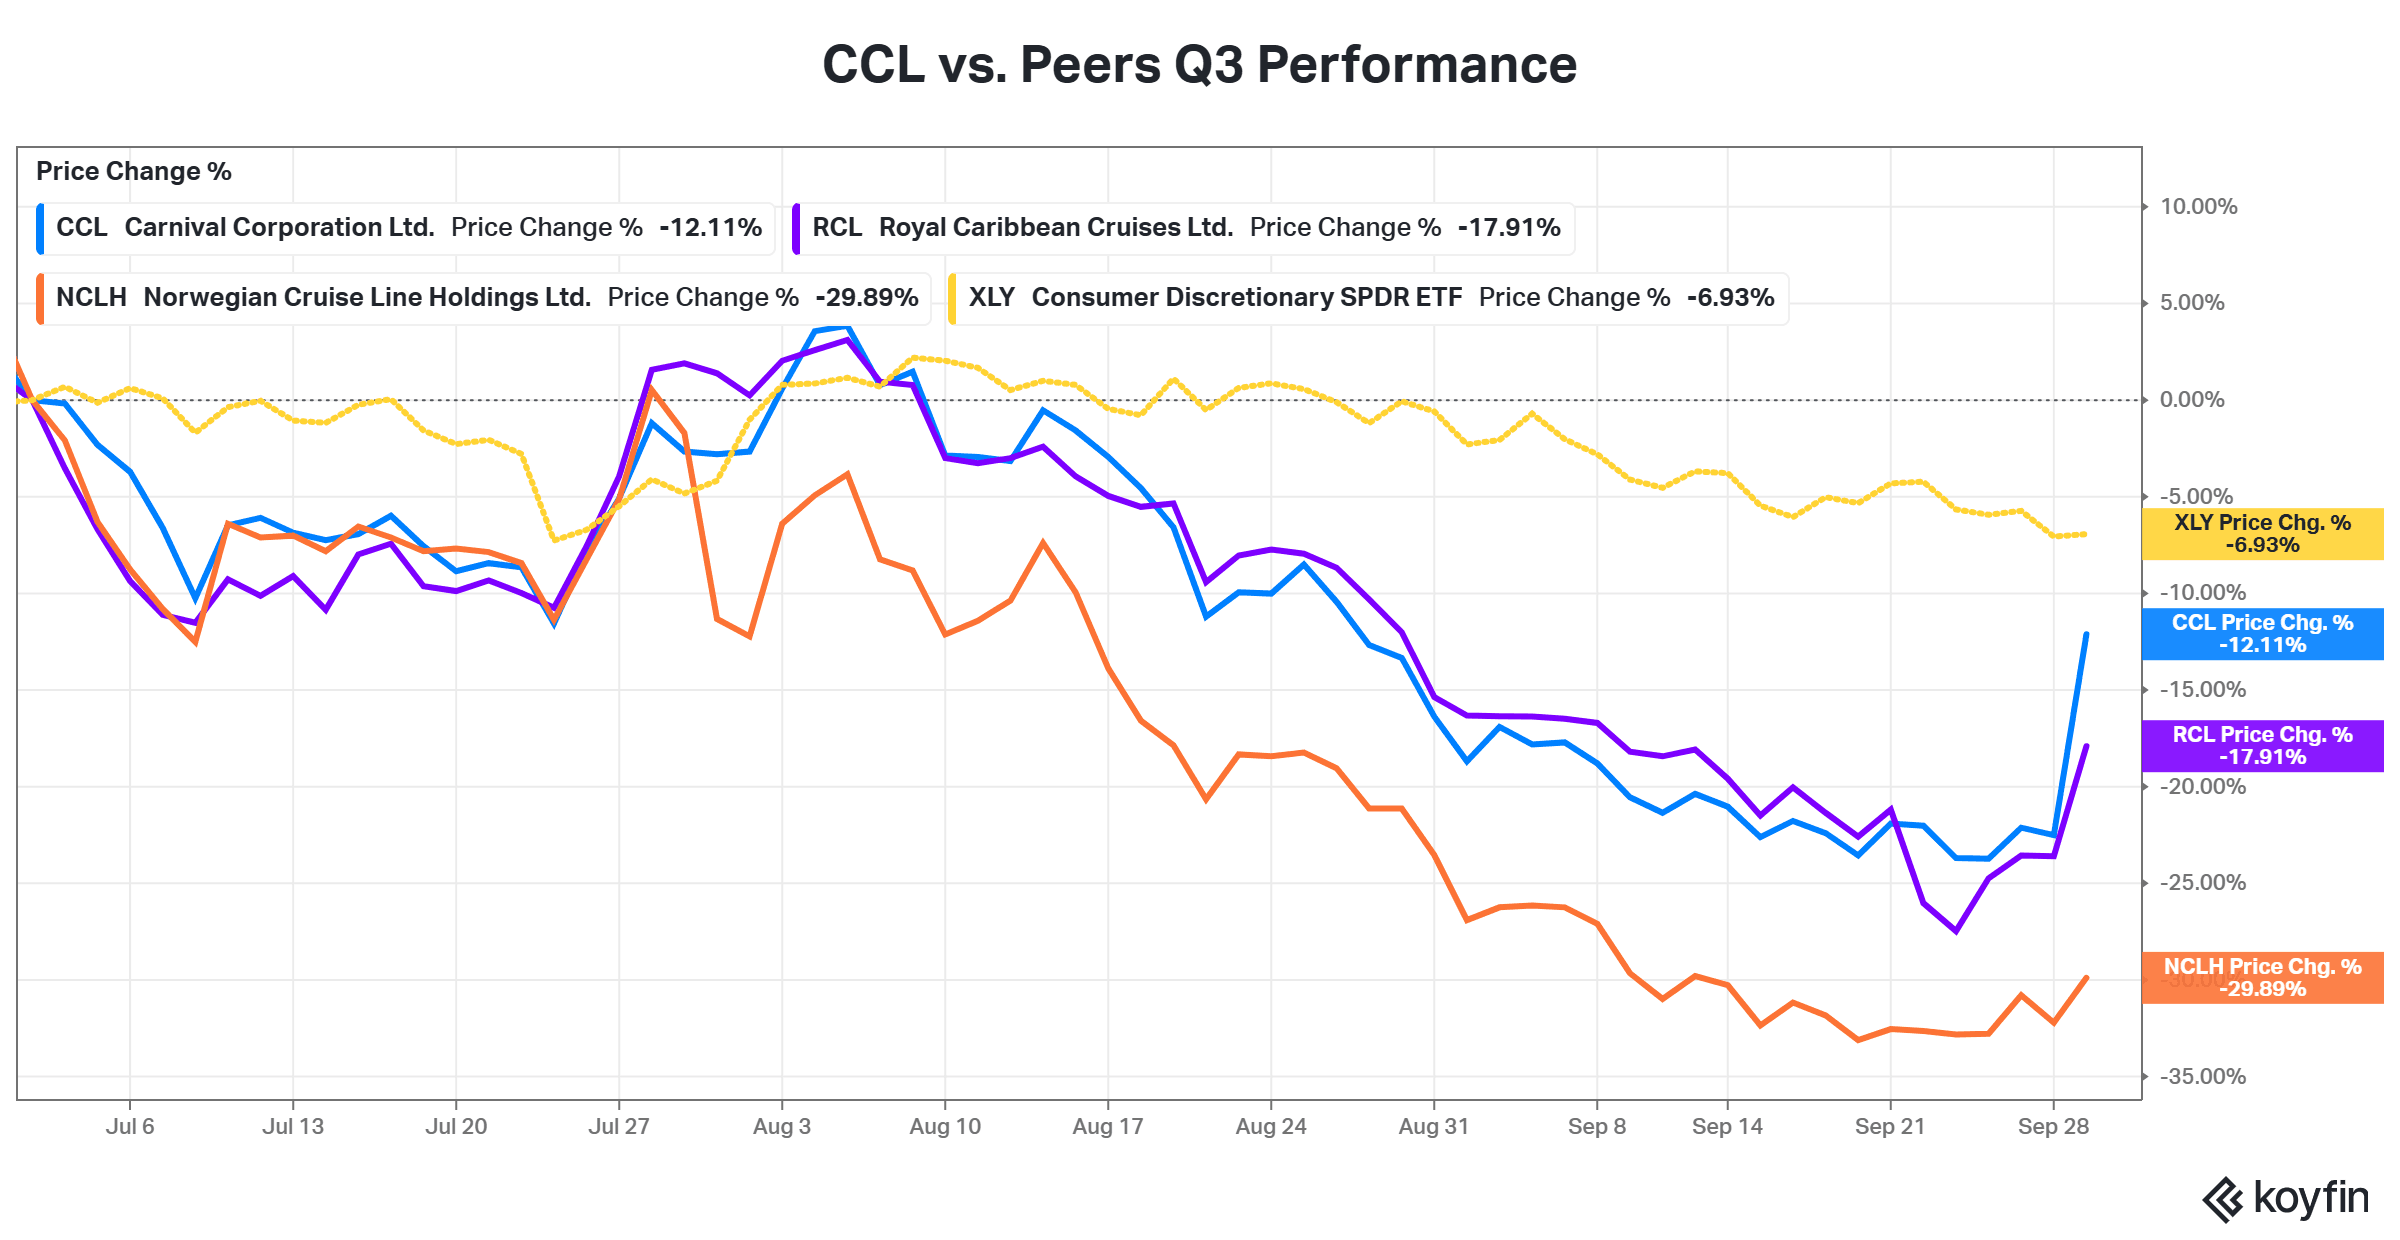
Shares of Carnival Corp. (CCL) are on track for their best month since May after record third-quarter results, and record 2027 bookings eased doubts about the cruise industry. The stock jumped 13% on Tuesday, its biggest one-day gain since April, after the cruise operator raised its 2026 profit outlook despite sharply higher fuel costs.
Carnival’s stock edged up 0.2% in overnight trading and has gained 5% in September.
Carnival’s 2027 Bookings Point To Continued Pricing Power
For much of 2026, cruise stocks faced pressure from higher fuel costs and weaker consumer confidence. Even after Tuesday’s rally, Carnival remains down about 17% this year. Its Q3 results showed that strong demand can support earnings despite higher fuel costs.
Customer deposits rose about 7% while capacity stayed mostly unchanged, meaning customers are spending more per available berth. The key question is whether this strong pricing power can continue.
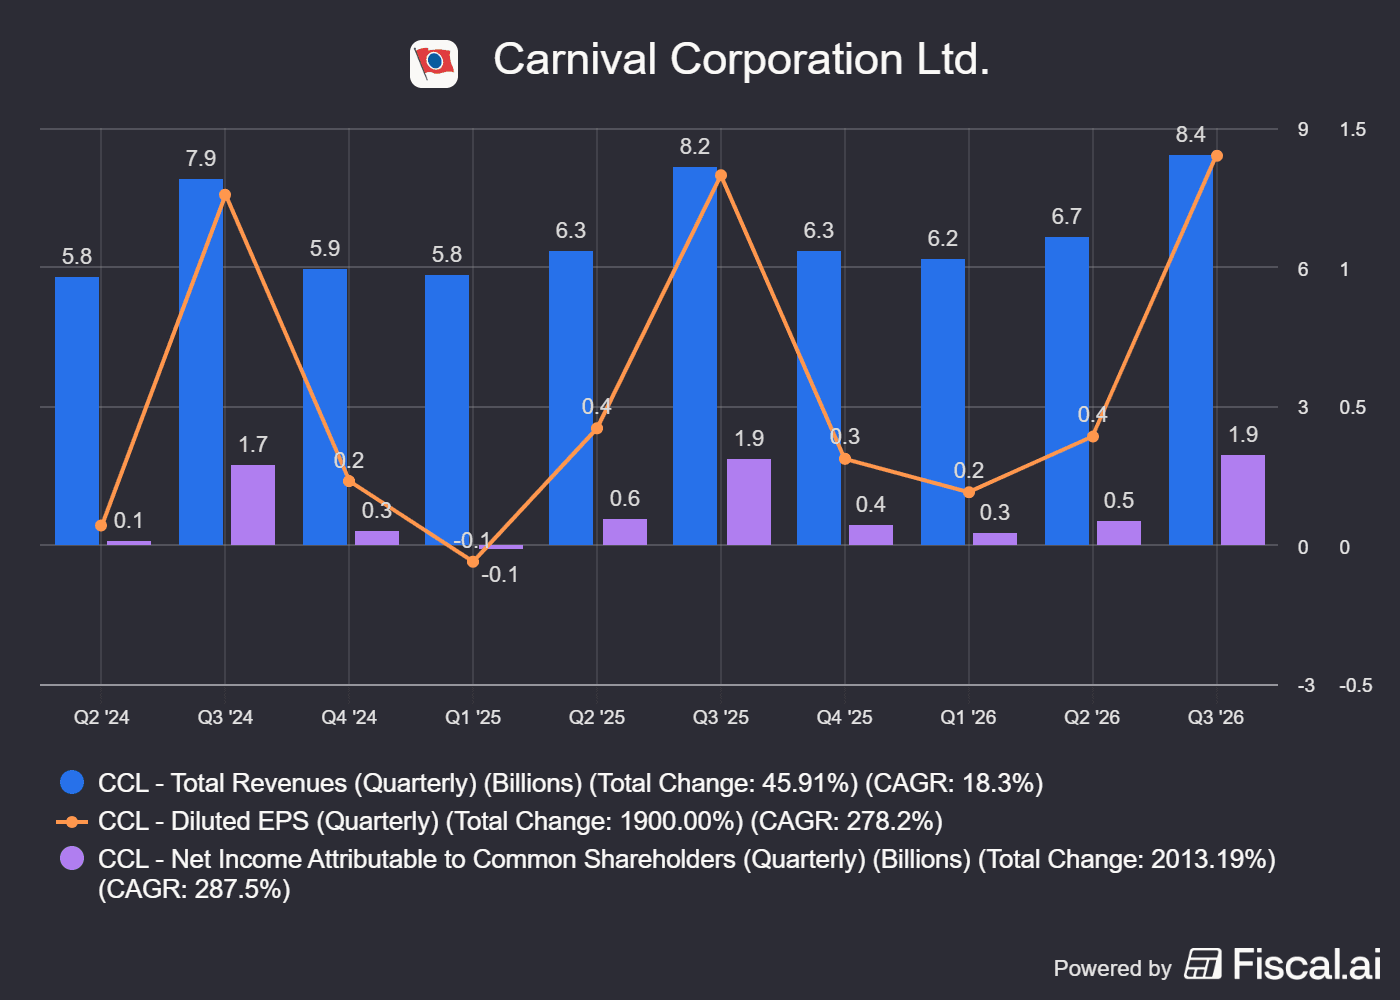
Carnival generated $8.44 billion in revenue in Q3, up 3.5% year over year. Net income increased 3.7% to $1.92 billion. The company reported earnings of $1.43 per share. Both revenue and EPS exceeded the analysts’ consensus estimates of $8.39 billion and $1.35, respectively, according to fiscal.ai data.
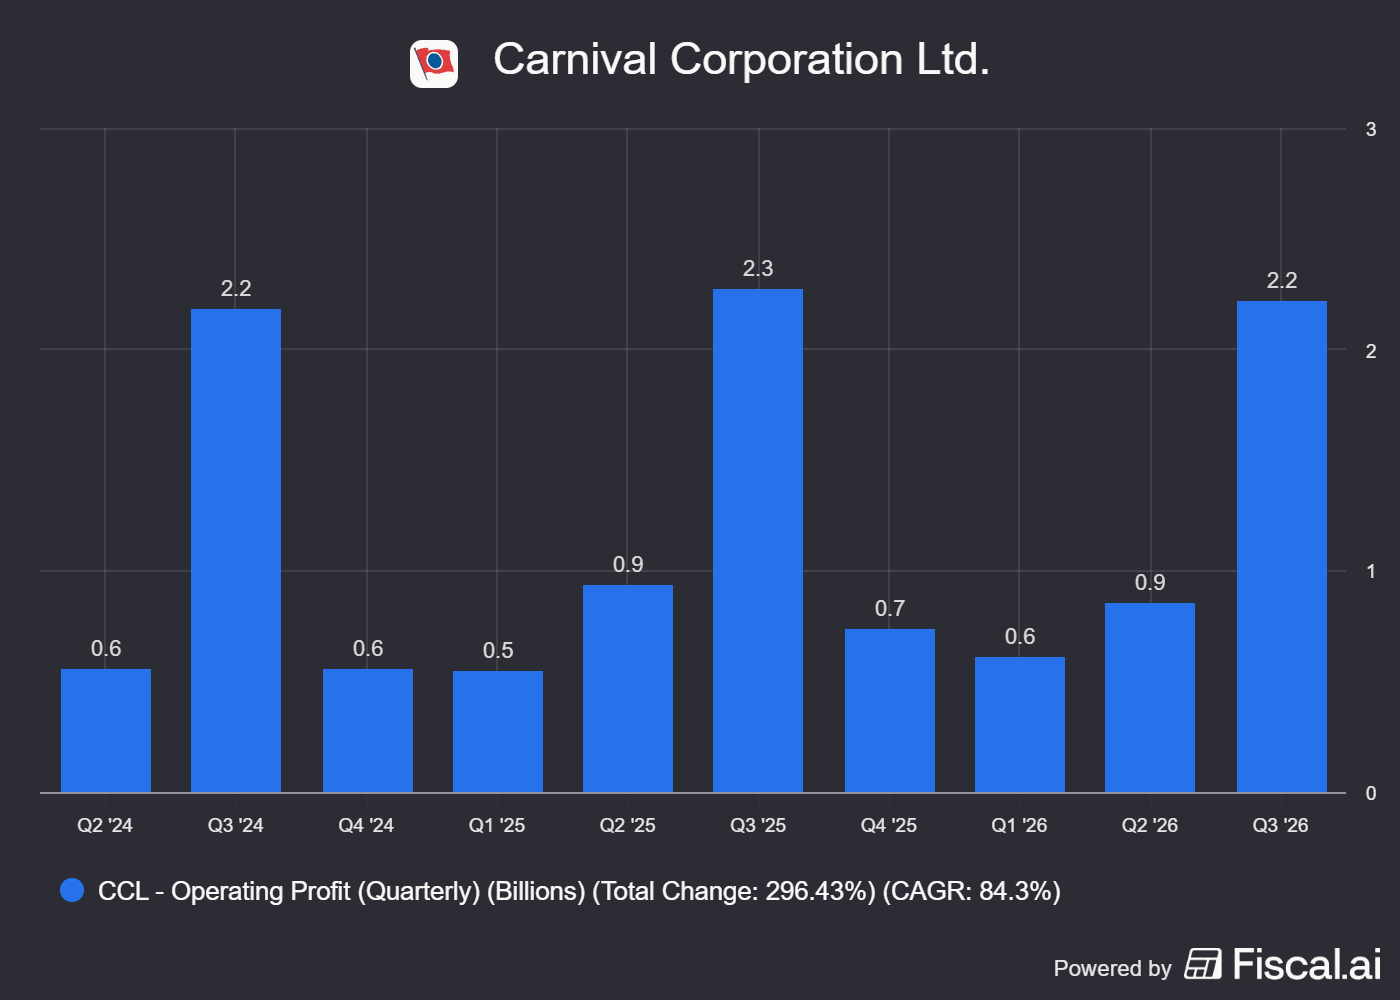
Carnival said constant-currency net yields climbed 2.4%, beating its previous guidance by more than 1 percentage point. Customer deposits also indicated strong demand. The company ended the quarter with $7.6 billion in deposits, $500 million above the prior-year record, despite little change in capacity expected over the following 12 months.
Speaking during the Q3 earnings call, Carnival CEO Josh Weinstein said the company has already filled about half of its available 2027 inventory, with both occupancy and pricing running at record levels. Booking activity during the latest quarter further strengthened that position, while demand for the first quarter of 2027 has recovered significantly during the past three months.
"Demand remains broad-based, including very healthy demand for our peak summer European deployments. 2028 is also off to an excellent start at higher occupancy and even higher prices year-over-year, and our booking curve is further out than it has ever been at this point in the year”.
Costs And Fuel Pressures
Higher fuel prices remained a headwind, contributing to a $131 million combined unfavorable effect from fuel and currency during the quarter. Still, Carnival reduced fuel consumption per available lower berth day by 3.8% from last year. This helped Carnival find more than $150 million of additional operational improvement versus its previous 2026 guidance.
“Fuel can be a volatile input cost with a track record of prices going up and down. But amidst that noise, let's not lose sight of our underlying operational improvement,” said Weinstein.
Carnival now expects full-year adjusted EPS of about $2.24, with constant-currency net yields projected to rise roughly 2.3% from 2025. The company expects adjusted EBITDA of approximately $7.14 billion and adjusted net income near $3.08 billion.
“Despite the significant fuel price headwind this year, we expect to finish 2026 with even more brands generating mid-teens or higher returns on invested capital than last year. That is meaningful progress, and we still see considerable runway ahead with each of our brands on a path toward higher returns.”
Carnival has repurchased nearly $1.2 billion of stock so far this year and paid $618 million in dividends through the first nine months. Chief Financial Officer David Bernstein said strong cash generation allowed the company to continue reducing leverage while returning capital.
Morgan Stanley analyst Jamie Rollo raised Carnival’s price target to $32.50 from $31 while keeping an ‘Overweight’ rating. The change follows the firm’s 6% increase to its fiscal 2028 EPS forecast after Carnival’s Q3 results.
Carnival’s strong Q3 results show that consumers are still willing to spend on cruises. The results also suggest that the cruise industry has become stronger and more mature. Carnival is growing its customer base by investing in private destinations, such as Celebration Key, and improving loyalty programs like Carnival Rewards. Its co-branded credit card issuances have already tripled, showing stronger customer engagement.
What CCL Retail Traders Are Saying
On Stocktwits, retail sentiment around the stock improved to ‘extremely bullish’ from ‘bullish’ territory the previous day.
A user said, “Today was a great day because we had great results. The future looks bright going forward but we haven’t reached our destination yet. Just remember how far [we[ fell. I want us back at 32 - 35. Hopefully enough Bears got burned today to stay away and let this grow to its rightful place.”
CCL stock has declined 13% in the past 12 months.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
