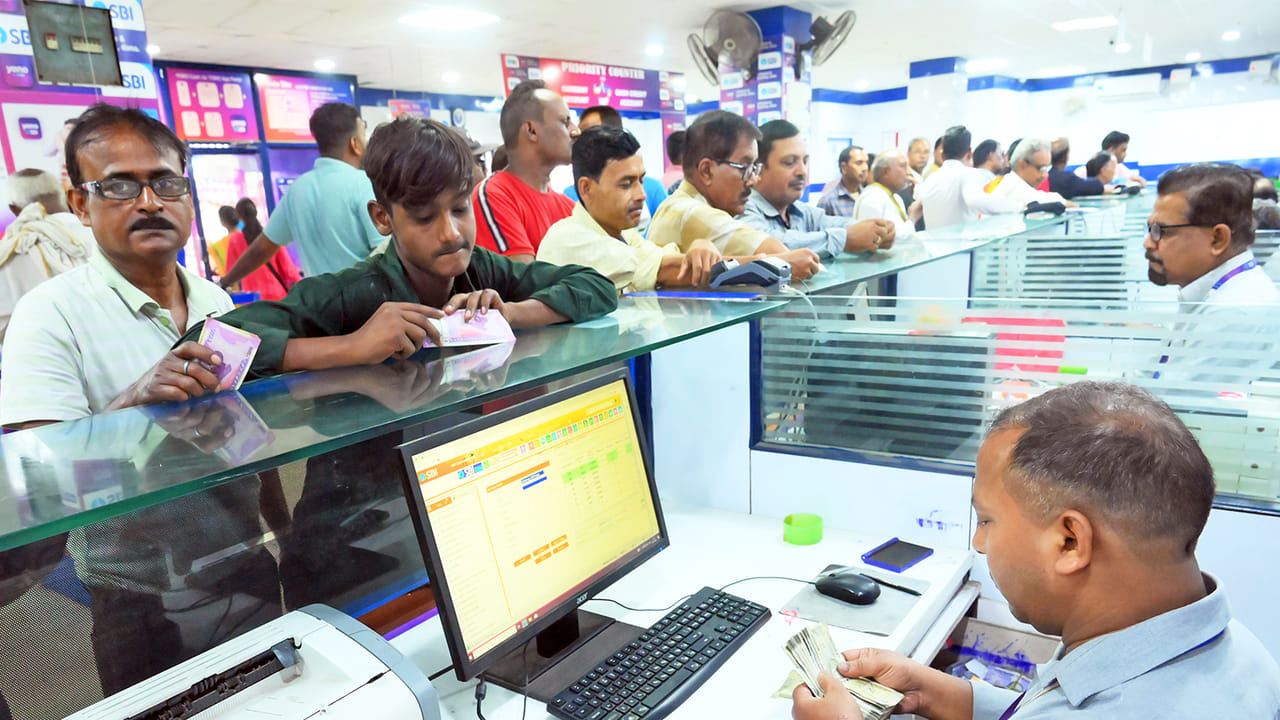
Indian banks saw their CASA ratio decline to 34.4% in Q2 FY27 from 35.6%, driven by strong FCNR(B) inflows. While total deposits grew by 16%, tighter liquidity and rising funding costs remain key concerns for profit margins in the second half.
CASA Ratio of Indian Banks Dips to 34.4 Percent in Second Quarter FY27
The share of low-cost deposits held by Indian banks declined to 34.4 per cent in the July–September quarter of FY27, compared to 35.6 per cent in the preceding quarter, even as overall deposits recorded strong growth, according to a report by 360 ONE Capital. In its banking sector research report titled "Banks – 2QFY27 Results Review," the brokerage attributed the decline in the Current Account Savings Account (CASA) ratio to strong inflows into Foreign Currency Non-Resident (Bank) or FCNR(B) deposits.
The report stated, "Strong FCNR (B) flows also resulted in a decline in CASA ratio to ~34.4% versus 35.6% in 1Q with PVBs/PSBs CASA ratio declining by ~150/90 bps QoQ to 33.9%/34.8% in 2Q." CASA represents deposits held in current and savings accounts, which generally cost banks less than fixed deposits and other forms of borrowing. A decline in the CASA ratio indicates that low-cost deposits are accounting for a smaller share of banks' total deposits.
According to the brokerage's analysis of 36 banks, comprising 24 private sector and small finance banks and 12 public sector banks, total deposits grew 16 per cent year-on-year and 6 per cent sequentially during the quarter. The growth was primarily supported by term deposits, which increased 19.2 per cent year-on-year and 7.8 per cent quarter-on-quarter. Current account deposits also grew 13.2 per cent year-on-year.
However, the report highlighted that despite strong FCNR(B) deposit mobilisation, banks continued to rely on other sources of funding as liquidity conditions tightened. Certificate of deposit issuances remained elevated at around Rs 1 trillion in October 2026, compared to approximately Rs 0.6 trillion in October 2025. Banking system liquidity also narrowed to around Rs 2.4 trillion in October, equivalent to 0.8 per cent of deposits, compared with 2.8 per cent in September 2026, the report noted.
Highlighting the importance of attracting low-cost domestic deposits, the brokerage said, "While FCNR (B) deposits provide breather in the near-term, we believe retail deposits and CASA deposit accretion remains a key monitorable in the coming quarters." The report also cautioned that rising funding costs could influence banks' profit margins during the second half of FY27, as several lenders have increased their term deposit interest rates. It stated, "While full impact of FCNR (B) deposits on cost of funds will be visible in 3Q, few banks have also raised their term deposit rates and thus the extent of NIM improvement in 2HFY27 will depend on the increase in the cost of funds and extent of rate hikes."