TGT Stock Heads For Best Year Since 2019: Does Its Q3 Turnaround Justify The Premium?
Synopsis
Target’s stronger traffic, digital sales, and raised outlook are fueling turnaround momentum.
- Target’s turnaround gained traction in Q3, with comparable traffic rising 5% and net sales increasing 7.1%.
- Excluding the tariff benefit, Target’s adjusted EPS still grew 21%, but there was weakness in home and apparel.
- Morningstar cautioned that Target’s growth mix and apparel weakness could limit margin expansion.
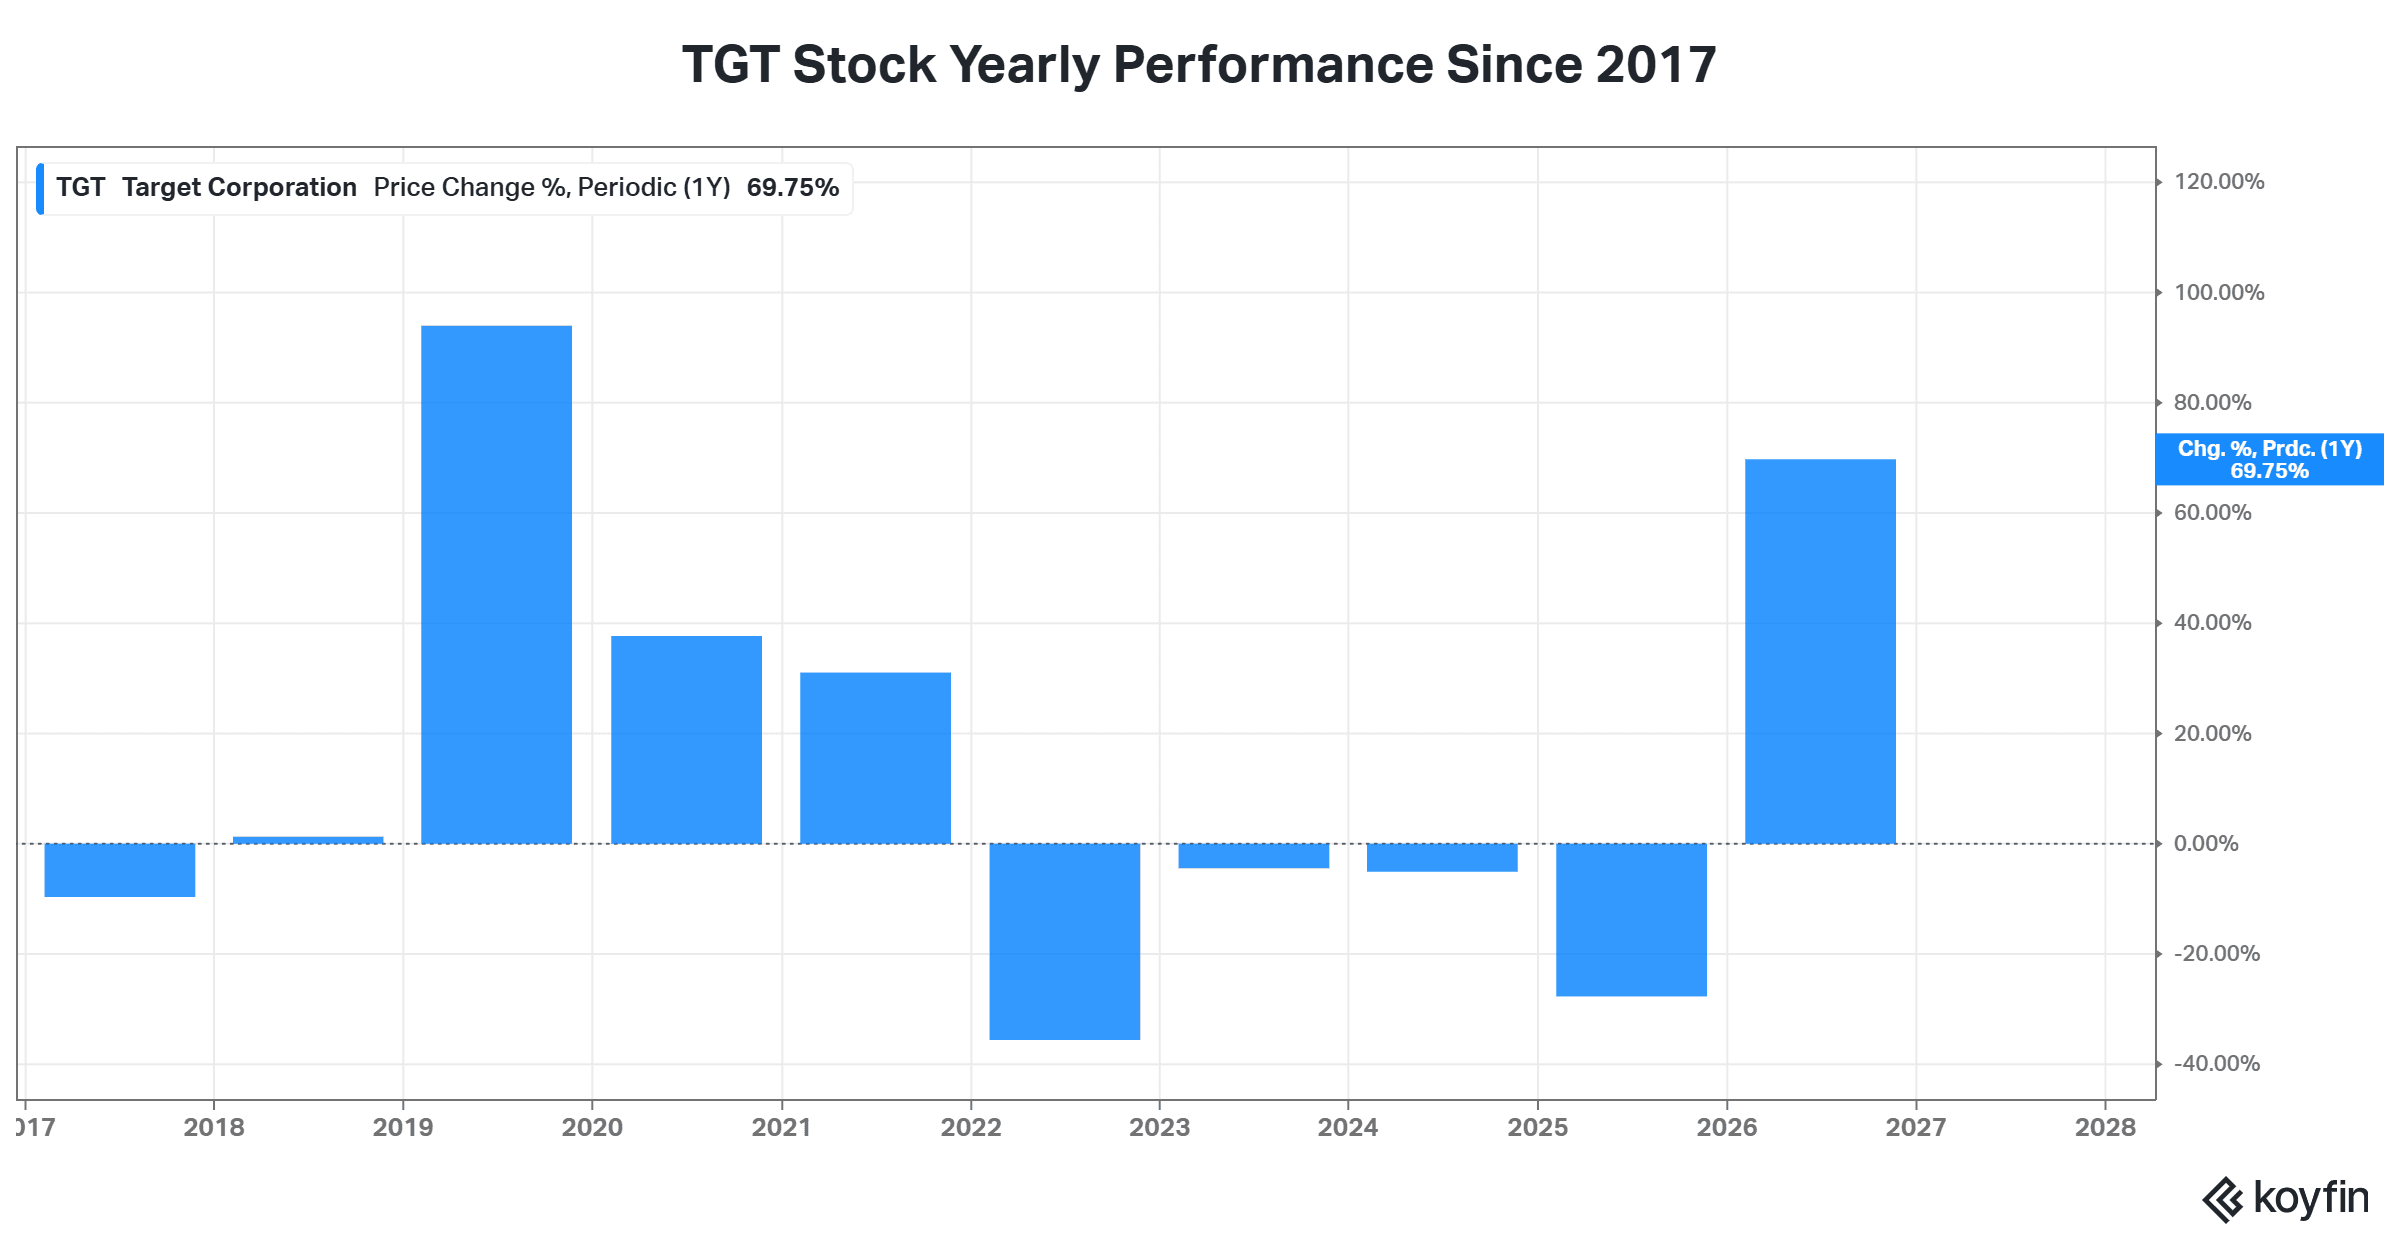
Target Corp. (TGT) is on pace for its strongest annual performance since 2019 after a third quarter (Q3) that brought shoppers back, lifted guidance, and smashed Street estimates. But with shares trading well above one analyst’s fair value, investors are asking whether the rebound deserves a premium.
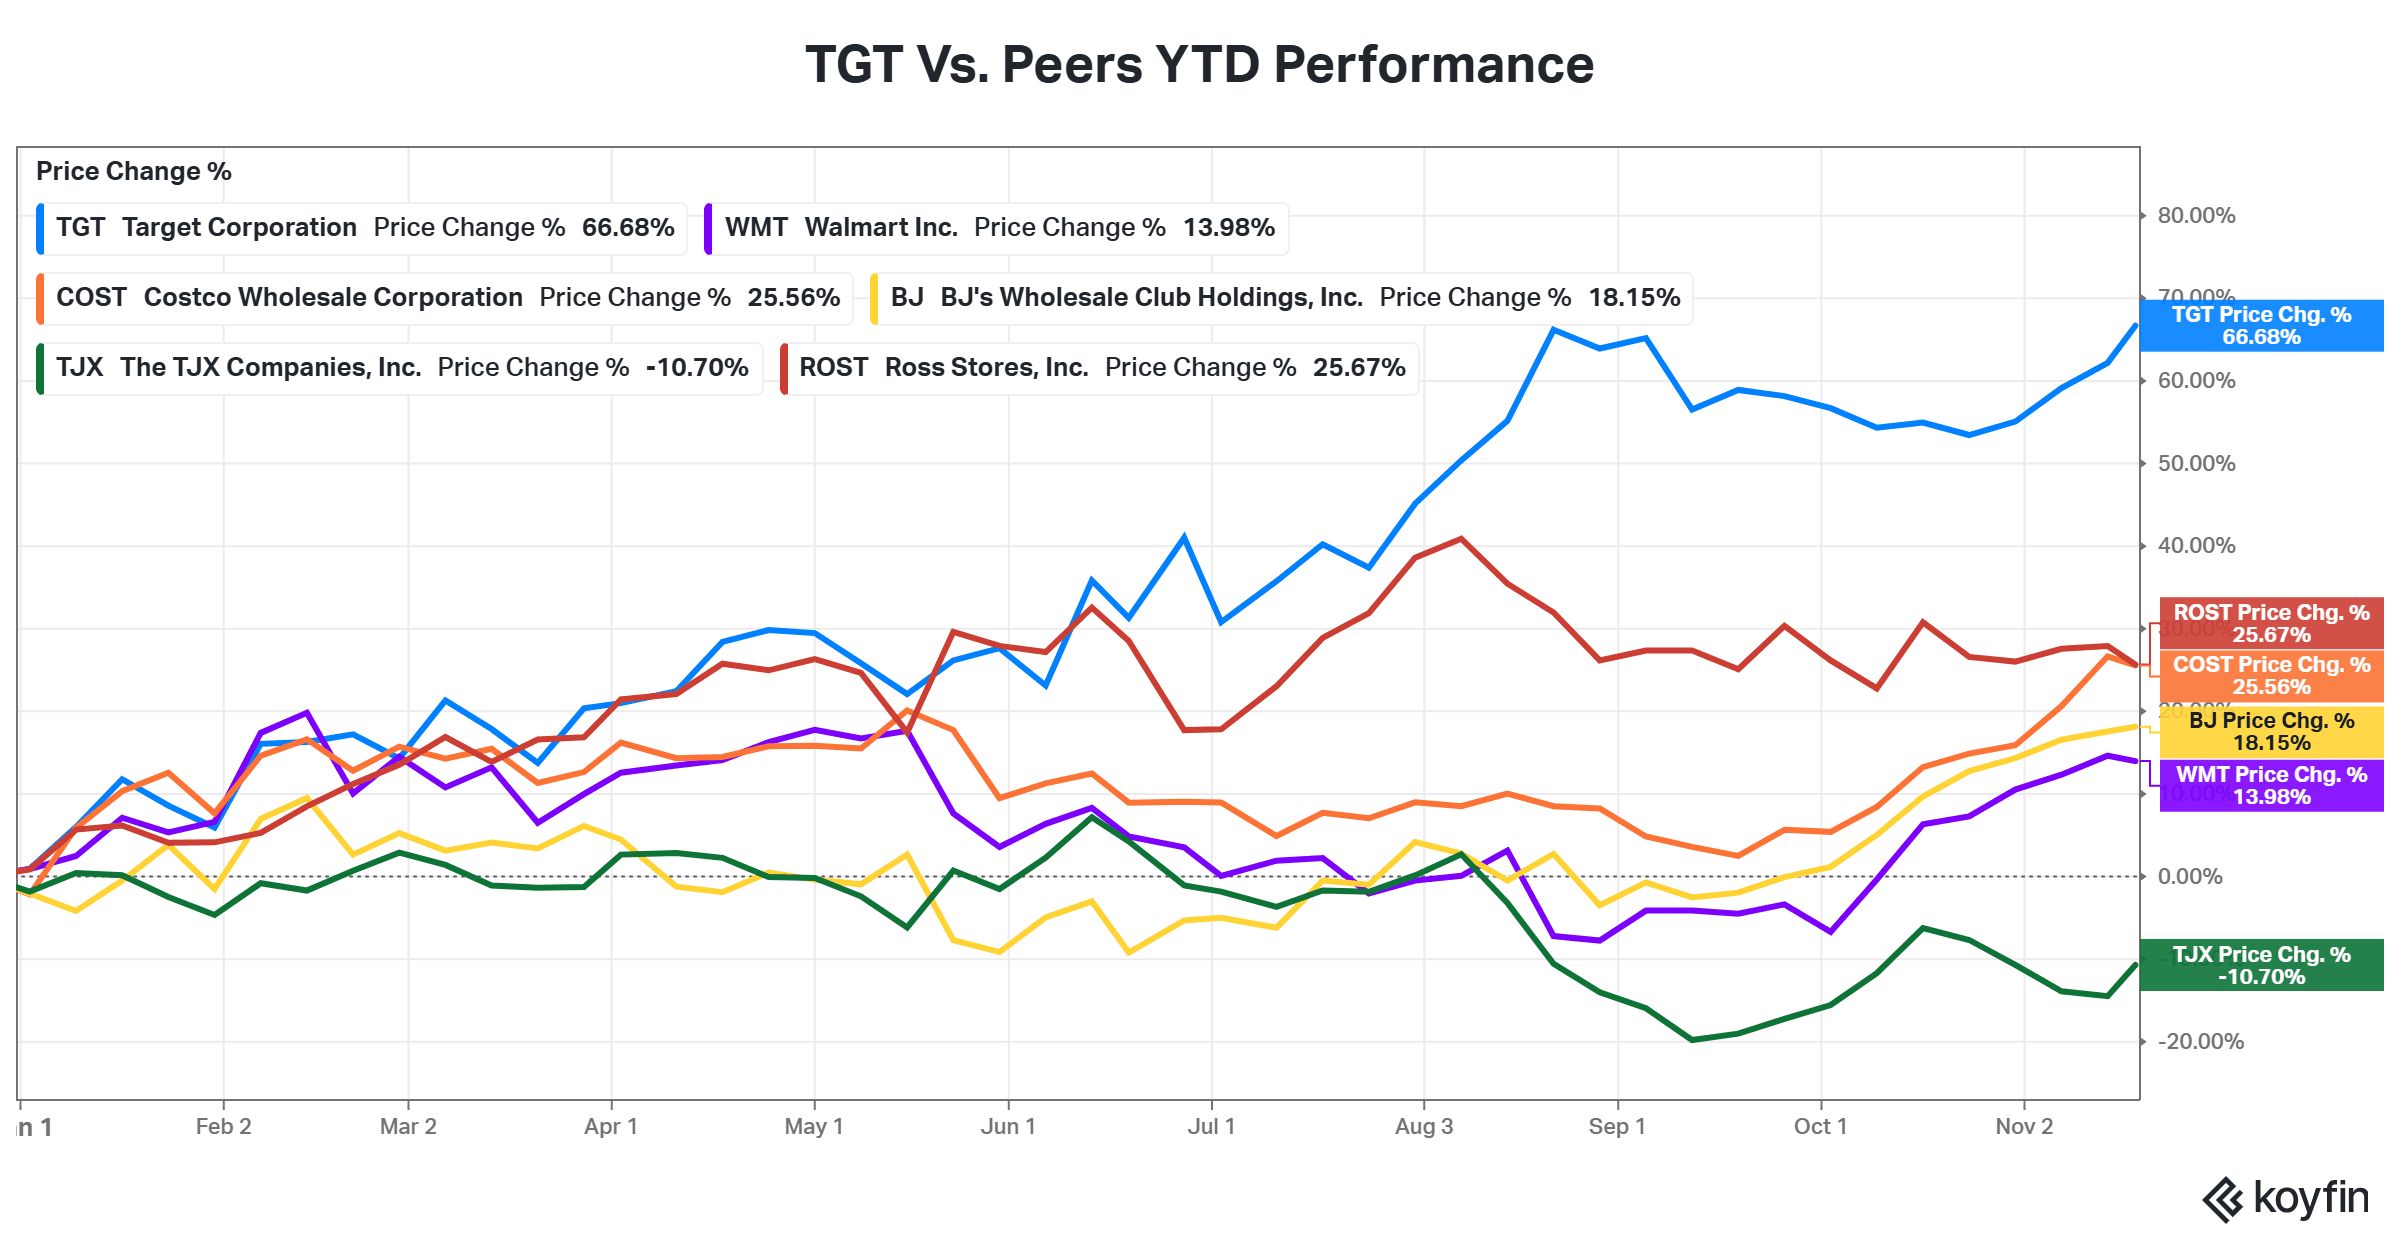
Target stock edged 0.2% higher in Thursday’s premarket. The stock has gained 69% year-to-date.
Target’s Turnaround Gains Momentum As Store Traffic And Digital Sales Climb
Target’s turnaround under CEO Michael Fiddelke is showing up in the number that matters most: people walking through the door. Comparable traffic rose 5.0% in Q3, and the company raised its full-year sales outlook. The debate now is about quality and durability. Part of the earnings beat came from one-time tariff refunds, and the growth is concentrated in lower-margin categories.

Net sales climbed 7.1% year-on-year. Stores did the heavy lifting, with comparable sales up 4.6%, while digital comparable sales jumped 9.8%. Sales grew in every month of the quarter, with the Back-to-School and Back-to-College seasons the strongest stretch.
Fun 101 sales rose nearly 27%, Beauty grew more than 9%, and Food and Beverage gained nearly 7%. Non-merchandise sales, which include Roundel advertising, Target Circle Card profit sharing, Target Circle 360 memberships and the Target+ marketplace, grew nearly 20%. That higher-margin revenue stream gives Target a profit source that doesn’t depend on how many T-shirts it sells.
Target’s Raised Outlook Includes A One-Time Tariff Windfall
Third-quarter adjusted earnings per share came in at $2.65, beating the analysts' consensus estimate of $2.08. This included $301 million in pretax tariff refund benefits, which added $0.50 to EPS.
Strip that out, and the picture is still solid. Excluding the refunds, EPS would have risen 42% and adjusted EPS 21%. Morningstar analyst Brett Husslein put adjusted EPS at $2.15 on that basis.
The tariff windfall also runs through the company’s outlook. Target now expects full-year operating margin of around 6.2%, including about 1.1 percentage points from refunds recognized so far. Its updated EPS range of $10.65 to $11.40 includes roughly $2.14 of those benefits.
Fiddelke framed the results as the product of compounding investments rather than a single lucky break. “We’re giving our guests more reasons to shop us more often,” he said on the earnings call, pointing to traffic gains across stores, digital and multiple categories.
He also acknowledged where the work remains. Home and apparel are categories “where we still have meaningful work to do,” Fiddelke said, adding that the company is not satisfied with their performance. On pricing, he said Target has lowered prices on thousands of items over the past year and plans to keep doing so as affordability stays top of mind for families.
Morningstar Questions The Sustainability Of Target’s Category-Led Recovery
Morningstar’s note offers a counterargument. Husslein said Target’s merchandising overhaul is restoring traffic and relevance, but he questions how long the growth lasts. The categories growing fastest, food, beauty, and trend-driven hardlines, tend to carry lower margins than apparel and home, where recovery is incomplete.
Home returned to slight growth of 2.5%, but women’s fashion weighed on apparel, which fell 3.8%. Husslein argues this reflects Target’s midmarket positioning, which leaves it exposed to cheaper rivals and stronger offerings.
Morningstar plans to nudge its $131 fair value estimate up by a low-single-digit percentage, but it still sees shares trading roughly 20% above that level after a 4% gain on Nov. 18. The firm estimates the market is pricing in an average operating margin of 6.6% over the next decade, versus its own 5.7% estimate, and calls that unlikely.
According to Kotfin data, Target trades at a forward price-to-earnings (P/E) ratio of 17.5, still lower than Costco’s 48.1 and Walmart’s 42.5.
TGT Stock: Retail View
On Stocktwits, retail sentiment around the stock improved to ‘extremely bullish’ from ‘bullish’. The stock registered a 3,450% surge in message volume over the past week with a 0.2% gain in watchers.
A user said, “The average $TGT receipt was only 0.6% bigger than a year ago. Transactions were up 5%. People actually made more Target runs this quarter.
Another user said, “Still well under 20 P/E!!! Still quite undervalued compared to peers.”
TGT stock has gained 92% in the past twelve months.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
Stay updated with all the latest Business NewsShare Market NewsIPOsGold PriceDA Hike8th Pay CommissionAsianet News Official App