CoreWeave ‘Not Circling The Drain,’ Says Analyst — But Warns Of ‘Staggering’ Financial Obligations
Synopsis
MoffettNathanson’s warning follows a brutal week for CoreWeave shares as soaring borrowing costs raise questions about the sustainability of its debt-funded AI expansion.
- MoffettNathanson cut CoreWeave's price target to $89 from $107 but maintained a ‘Neutral’ rating.
- CoreWeave shares plunged last week as investors grew concerned about its mounting financing burden.
- Goldman Sachs upgraded CoreWeave to 'Buy' from 'Neutral' despite cutting its price target.
CoreWeave (CRWV) is not “circling the drain,” according to MoffettNathanson, even as the brokerage lowered its price target on the artificial intelligence (AI) cloud infrastructure provider to $89 from $107 on Monday, maintaining a ‘Neutral’ rating.
The firm said CoreWeave has several financing options available, although some may be unappealing, according to The Fly. However, it warned that the company has incurred “staggering financial obligations” and remains ultimately dependent on capital markets' willingness to finance its business.
CoreWeave Stock Plunges As Debt Concerns Rattle Investors
The latest assessment follows a brutal week for CoreWeave shares, which plunged more than 25% between October 9 and October 16.
The selloff intensified Wednesday last week as hotter-than-expected U.S. inflation data fueled expectations of additional interest-rate hikes, raising concerns about financing costs for heavily indebted AI infrastructure companies.
CoreWeave's borrowing costs became a particular flashpoint. The yield on its dollar-denominated bonds maturing in October 2031 briefly surged above 16% on Thursday, while the cost of insuring its debt against default climbed past 1,000 basis points.
CoreWeave’s $35.6B Debt Burden Despite $104B Backlog
CoreWeave reported $35.6 billion in total indebtedness as of June 30. Its second-quarter net interest expense rose to $640 million from $267 million a year earlier, underscoring the cost of funding its expansion.
CEO Michael Intrator pushed back against the concerns in an internal memo seen by Reuters, saying markets can sometimes “misunderstand and act irrationally.” The company had approximately $104 billion in contracted revenue backlog at the end of June.
What Other Analysts Are Saying About CRWV
Despite the bond-market turmoil, some analysts believe the selloff has overstated CoreWeave's financial risks.
On Monday, Goldman Sachs upgraded CoreWeave to 'Buy' from 'Neutral' despite cutting its price target to $106 from $139, implying 73% upside potential, according to The Fly.
The firm acknowledged financing concerns amid credit-market volatility but expects CoreWeave's annual recurring revenue per megawatt and unlevered returns to improve over the next 24 months, citing tight AI computing supply and the company's competitive differentiation from other cloud providers.
Yorkville Ives analyst Dan Ives called the decline a “false narrative” in a Bloomberg interview on Friday, citing strong AI demand and CoreWeave’s backlog as reasons to view the weakness as a buying opportunity.
JPMorgan analyst Samik Chatterjee similarly called concerns over rising bond yields and AI infrastructure returns “overdone,” arguing that data-center demand has strengthened and CoreWeave's project economics remain sound.
What Retail Investors Think About CoreWeave
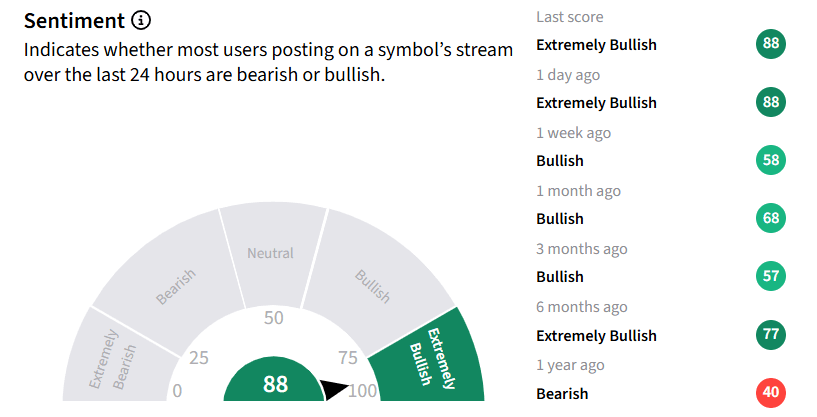
Despite the recent bloodbath, retail investors’ sentiment surrounding CRWV stock remained ‘extremely bullish’ amid extremely high message volume.
So far this year, CRWV stock has fallen over 22%. By comparison, the iShares Future AI & Tech ETF (ARTY) and the Invesco QQQ Trust, Series 1 (QQQ), which hold the stock, have risen nearly 40% and 16%, respectively, during this period.
See Also: Yardeni Says AI Buildout Is Adding To Inflation Pressure — Doubts Fed Will Need To Move Decisively Into Restrictive Territory
For updates and corrections, email newsroom[at]stocktwits[dot]com<
Stay updated with all the latest Business NewsShare Market NewsIPOsGold PriceDA Hike8th Pay CommissionAsianet News Official App