Anthropic IPO Sentiment Is The ‘Core Driver’ Of The AI Trade, Analyst Says – Calls CoreWeave Q3 Results ‘Survive And Advance’ Print
Synopsis
In an interview with CNBC, the analyst said he sees a “quite bullish” setup into December if the offering goes well.
- Evercore ISI’s Kevin Rippey said that CoreWeave’s third-quarter results were a “survive and advance” print.
- According to the tech analyst, sustained demand would give investors greater confidence that CoreWeave can service its debt and eventually return cash to shareholders.
- Rippey identified the midterm elections and Anthropic’s listing as two major catalysts for U.S. equities in the fourth quarter.
Whether or not Anthropic’s (ANT) initial public offering (IPO) goes well will decide the direction of AI stocks into year-end, Evercore ISI technology analyst Kevi Rippey said on Wednesday.
“Sentiment around the frontier is the core driver of the AI trade set,” Rippey told CNBC in an interview. “That is where I think things begin and end over the last two weeks.”
According to him, two “really catalytic events” are set to shape the fourth quarter for U.S. stocks. One was last week’s midterm elections, and the second is Anthropic’s upcoming listing.
“We get through this event. We look out into December, and you can draw quite a bullish construct,” Rippey stated.
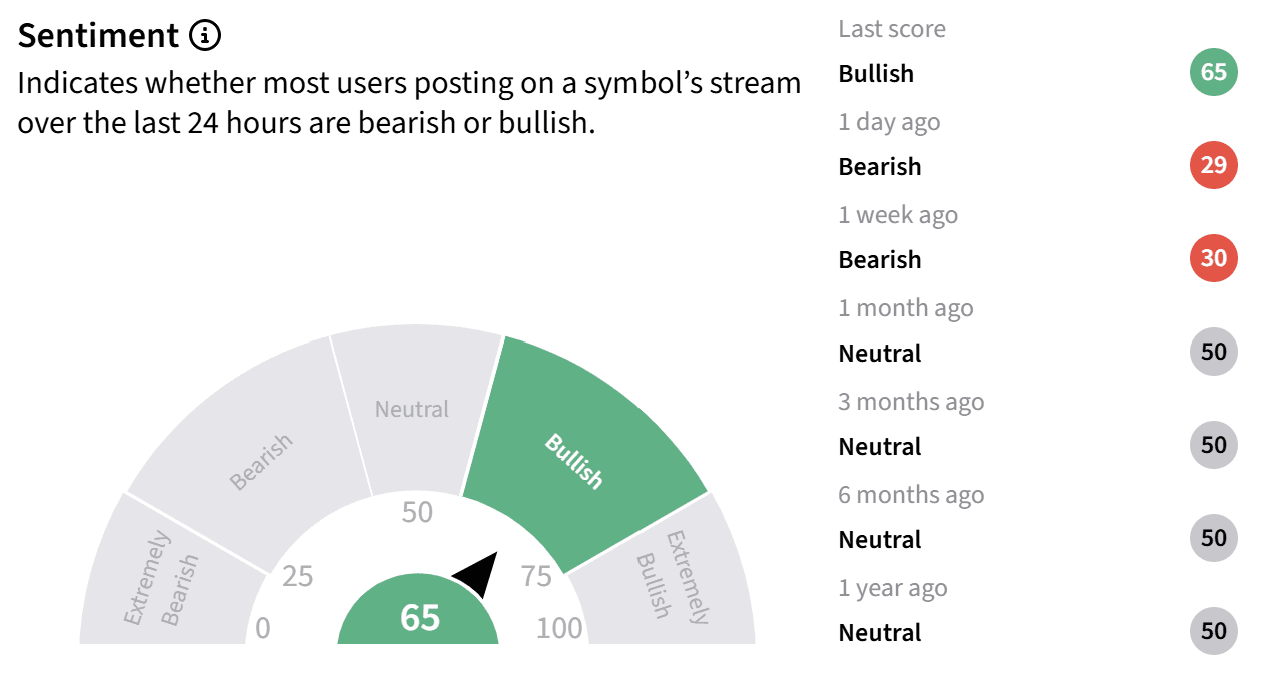
On Stocktwits, retail sentiment around ANT flipped to ‘bullish’ from ‘bearish’ territory over the past day, while chatter jumped to ‘extremely high’ from ‘low’ levels.
Anthropic IPO Could Set The Tone For AI Stocks
On Tuesday, Anthropic released an updated prospectus, setting a price range of $70 to $78 for 825 million Class A shares. At the top of the range, the offering could raise about $64.4 billion before expenses.
Alphabet’s Google (GOOGL), Nvidia (NVDA), Advanced Micro Devices (AMD), Broadcom (AVGO), Micron Technology (MU), Microsoft (MSFT) and Taiwan Semiconductor Manufacturing Co. (TSM) have also agreed to purchase a combined $26 billion in shares through a private placement at the IPO price.
Rippey said that the Financial Times report, which said that Anthropic’s banks are now mulling over potentially increasing the company’s IPO valuation to $1.5 trillion or more, has tempered speculation that the IPO might be “sort of a limp into the finish line type event,” especially after AI stocks swung sharply late last week.
CoreWeave Earnings Ease Some Concerns, But Funding Remains A Risk
Rippey was more measured on CoreWeave (CRWV), which reported third-quarter results on Tuesday after the bell. He said the report removed the risk of a new downside shock but did not resolve the funding worries behind the stock’s sell-off over the past eight weeks.
“We learned nothing that would suggest that there are further delays, that there are further bottlenecks that are impacting the company’s ability to realize strong current demand,” he said. “I think it was largely confirmatory of all of the concerns that we had, but from a relief rally standpoint, a survive and advance type print is how I characterize it.”
Demand remains the company’s strongest point, Rippey added. “Demand is extraordinarily strong. If you have available capacity, you can price at a massive premium relative to longer duration contracts,” he said. According to the tech analyst, sustained demand would give investors greater confidence that CoreWeave can service its debt and eventually return cash to shareholders.
CRWV stock rose as much as 12.5% in pre-market trade, on track to log its biggest single-day gain since September. On Stocktwits, retail sentiment around the neocloud flipped to ‘extremely bullish’ from ‘bearish’ over the past day, and chatter increased to ‘high’ from ‘low’ levels.

CoreWeave Q3 Recap
CoreWeave’s revenue rose 168% year over year to $3.66 billion. Its adjusted loss of $1.27 per share was narrower than the $1.55 loss analysts had expected. The company forecast 2026 revenue of $13 billion to $13.3 billion and capital expenditures of $37 billion to $39 billion.
However, it reported a net loss of $709 million, interest expense of $846 million, and total debt of $46.9 billion.
“We will not use the unsecured debt market to fund our business at current yields, nor do we need to,” CEO Michael Intrator said during the earnings call, addressing the financing concerns directly.
The company expects to receive about $9 billion in customer prepayments and plans to rely on chip-backed loans to fund its expansion.
CRWV stock has fallen nearly 40% this year and more than 50% in the last 12 months.
Read also: CoreWeave May Benefit From Blue Wave’s Potential Data Center Slowdown, Analyst Says Ahead of Q3 Results
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
Stay updated with all the latest Business NewsShare Market NewsIPOsGold PriceDA Hike8th Pay CommissionAsianet News Official App