AMAT Stock Gets Slew Of Price Target Cuts Even After Beat-And-Raise Quarter: Morningstar Calls AI Worries ‘Overblown’
Synopsis
At least 10 firms cut their price targets on Applied Materials on Friday after the fiscal fourth-quarter report, according to TheFly.
- JPMorgan cited “severe” multiple compression in chip equipment stocks, and Needham and BofA also pointed to sector valuations.
- Morningstar raised its fair value to $570 from $520 and called AI market concerns “overblown.”
- Goldman Sachs and UBS expect market share gains as chip equipment spending accelerates through 2027 and 2028.
Applied Materials (AMAT) saw a slew of price target cuts from Wall Street on Friday despite reporting a beat-and-raise third quarter.
According to TheFly, at least 10 analysts have lowered their price targets, including those from JPMorgan, Goldman Sachs, Bank of America, UBS, Wells Fargo, and Jefferies. However, all ten kept ‘Buy’-equivalent ratings on the stock, and the lowered price target still stood above the stock’s close in the previous session.
Morningstar was the only firm to raise its price target, increasing it to $570 from $520. It said that AI market concerns were “overblown at this point.”
AMAT stock was trading flat in pre-market trade on Friday and was among the top trending tickers on Stocktwits.
Wall Street Blames Sector Valuations
Most analysts cited valuations across chip equipment stocks as the reason for their price target cuts on Applied Materials, rather than the company’s results.
JPMorgan cited “severe” multiple compression in semiconductor capital equipment stocks. It said the quarter was a modest beat and that first-quarter guidance was slightly better than Street estimates but largely in line with what buy-side investors expected. Needham and BofA also cited sector-wide multiple compression.
Wells Fargo said elevated expectations required a larger beat-and-raise. BofA analyst Vivek Arya called the quarter “a modest beat/raise.” The firm raised its calendar 2027 and 2028 pro forma earnings estimates by 2% and 9%.
Goldman Sachs said it expects Applied Materials to gain market share as wafer-fabrication equipment spending accelerates in 2027, with upside to Street estimates if industry growth approaches 45%. UBS analyst Timothy Arcuri sees nearly 100 basis points of share gains and a potential $300 billion market for the equipment by 2028.
Every new price target on AMAT stock is above its $380.95 close on Thursday. The lowest, Needham’s $470, implies about 23% upside.

Morningstar Sees It Differently
Morningstar analyst William Kerwin raised his fair value estimate on Applied to $570 from $520, about 50% above Thursday’s close. He rates the stock four stars and gives the company a ‘wide moat’.
“Every signal indicates acceleration for Applied through 2027,” Kerwin wrote. He said he expects “leading-edge logic, DRAM, and advanced packaging to drive huge growth and market share gains.”
He added that there may be “regulatory speed bumps ahead” but expects “massive investment to continue.” He pointed to “massive chip capacity investments through 2030” that he said align with Morningstar’s multiyear AI-led growth thesis.
Kerwin wrote that Morningstar sees the risks from cyclicality of the semiconductor market and geopolitical tensions between the US and China as “baked in.”
AMAT Stock Price Target Cuts Follow A Strong Quarter
Applied Materials said fiscal fourth-quarter sales rose 53% from a year earlier to $10.41 billion, above Wall Street’s expectations of $10.29 billion. Earnings per share came in at $4.16, beating the consensus estimate of $4.05 cited by Koyfin.
It guided January-quarter sales to $11.1 billion. According to Morningstar, that figure was well above its own model.
How Is Retail Feeling About AMAT Stock?
Retail sentiment around Applied Materials on Stocktwits rose to ‘extremely bullish’ from ‘bullish’ territory over the past day, accompanied by chatter at ‘high’ levels.
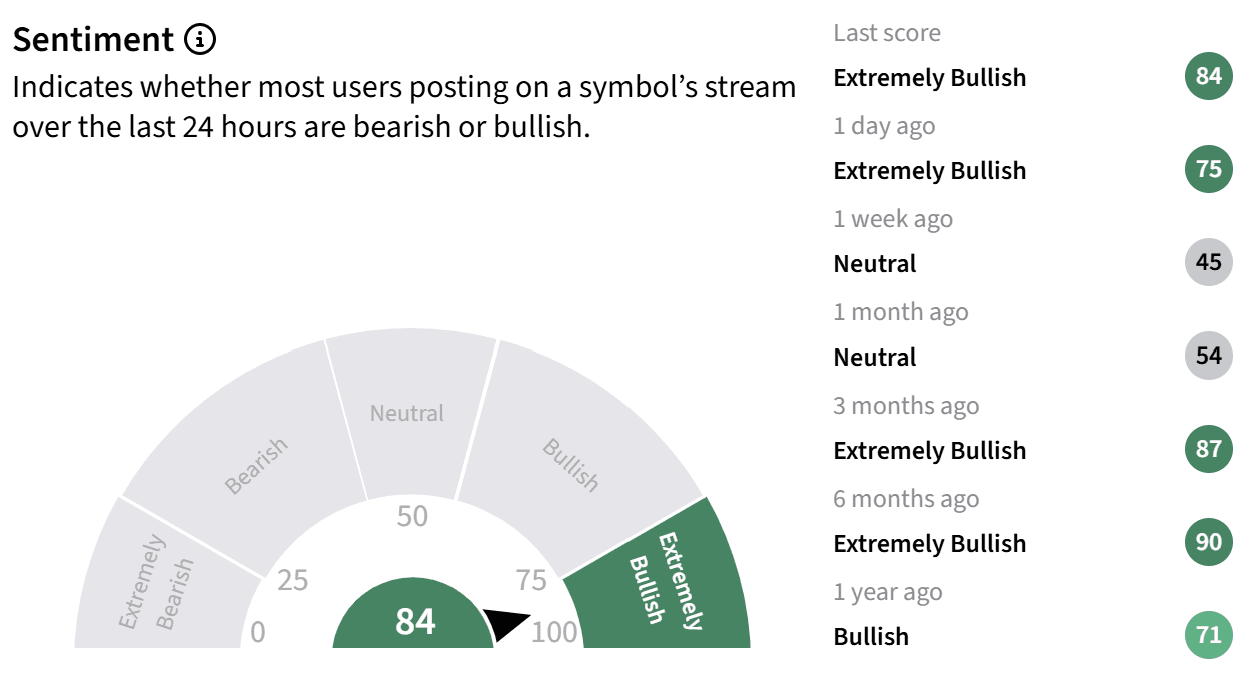
Some retail traders on the platform pointed out that AMAT’s fundamentals remain strong and that the longer-term outlook for semiconductor equipment demand is unlikely to be derailed by short-term market volatility.
View this Stocktwits post
View this Stocktwits post
AMAT stock has gained more than 65% over the last 12 months, excluding pre-market moves.
Read also: Tom Lee Says Jensen Huang Exit Doesn’t Change His Bullish Tech Outlook: AVGO, AMD Stocks Lead Chip Rally
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
Stay updated with all the latest Business NewsShare Market NewsIPOsGold PriceDA Hike8th Pay CommissionAsianet News Official App