Micron Earnings Could Reach $50 A Quarter, Says Susquehanna: Analyst Sees Memory Driving AI Profits
Synopsis
In an interview with CNBC, analyst Mehdi Hosseini said he believed that memory is becoming more important to AI infrastructure while compute becomes increasingly commoditized.
- Hosseini expects Micron to initially reach $30 to $40 in quarterly earnings before potentially moving toward $50.
- He sees diversified AI demand and a broader customer base supporting more sustainable memory pricing and margins.
- The analyst said he expects Micron to emphasize diversified demand, disciplined capital spending, and its ability to sustain operating margins around 70% during the company's earnings call after market close on Wednesday.
Micron Technology’s (MU) earnings could eventually reach $50 per quarter, which comes to $200 on an annualized basis, if memory continues to play a larger role in the artificial intelligence buildout, according to Susquehanna analyst Mehdi Hosseini.
Speaking on CNBC ahead of Micron’s fiscal fourth-quarter earnings report due after the market close Wednesday, Hosseini argued that the AI semiconductor cycle is increasingly shifting toward memory, while compute becomes more commoditized.
“I make the argument that compute is actually becoming more commoditized, and it's memory that makes the difference,” Hosseini said. He expects Micron’s earnings to initially reach $30 to $40 per quarter before eventually climbing to $50 per quarter, translating to roughly $200 in annualized earnings.
MU stock edged 0.7% higher in midday trade, and was among the top trending tickers on Stocktwits at the time of writing. The shares are trading around 14.5% below their record high of over $1,255 seen in June.
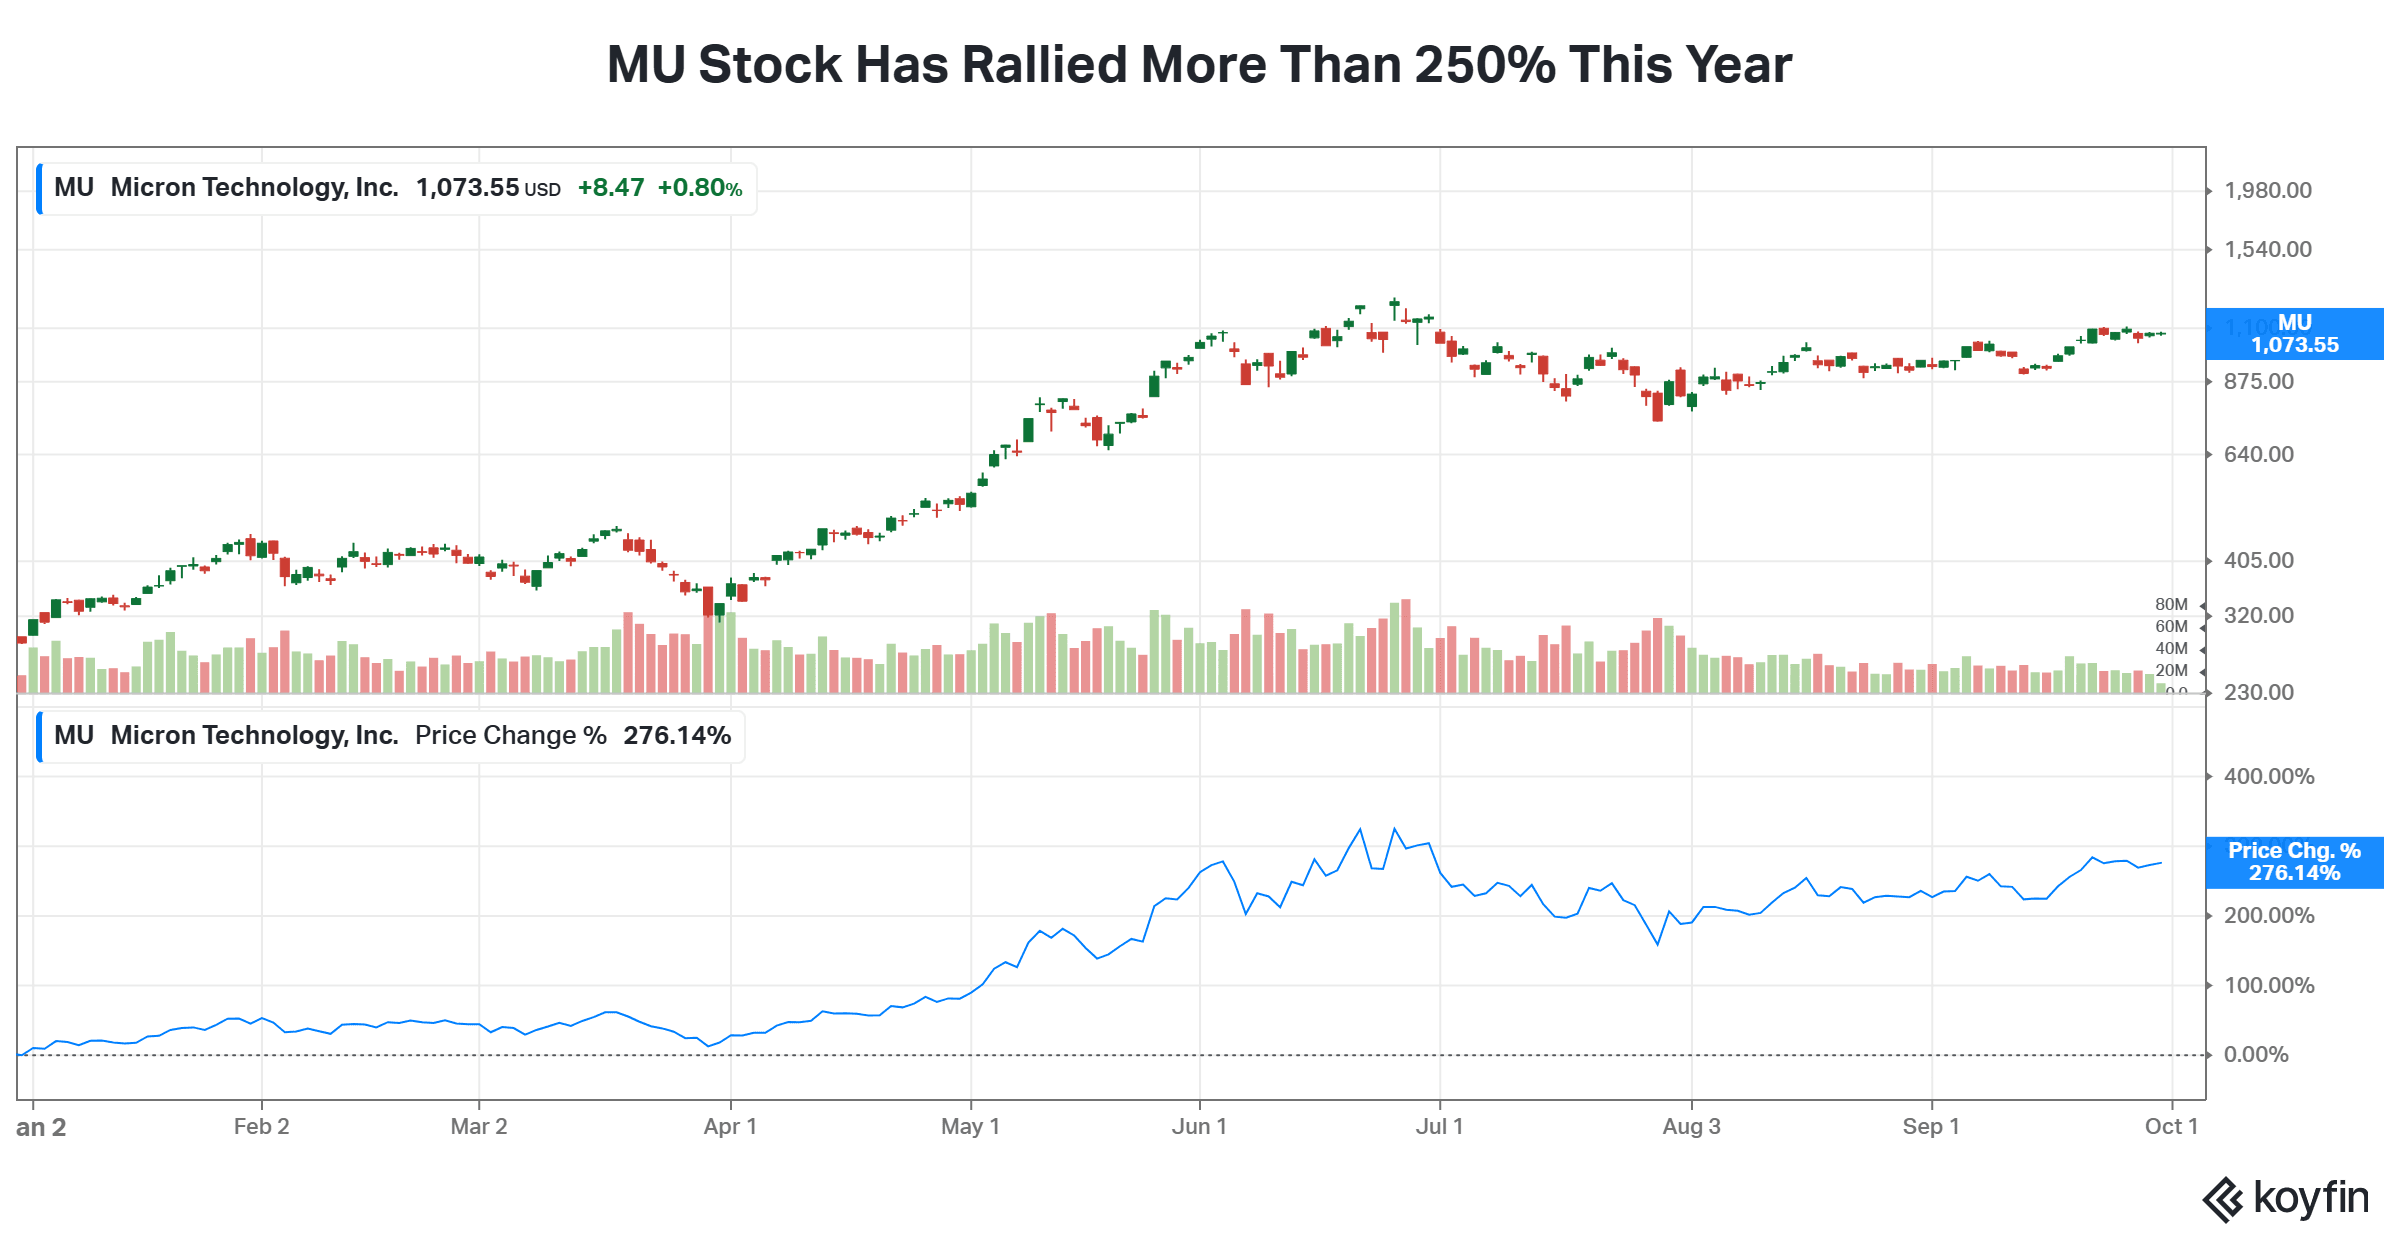
Wall Street expects Micron to report fiscal fourth-quarter earnings of $31.82 per share on revenue of $51.47 billion, as per Koyfin data. Micron has missed quarterly EPS estimates only twice in the past decade.

Can Micron Sustain 70% Margins?
Hosseini’s thesis is based on whether Micron and other memory makers can sustain elevated margins as AI infrastructure spending expands.
Rather than focusing only on the company’s next-quarter results, he said investors should pay attention to how durable Micron’s profitability can become. According to Hosseini, the key question is whether the current memory cycle can support structurally higher margins instead of reverting to the boom-and-bust pattern that has historically defined the industry.
“I think management will highlight the discipline that the memory industry employs and therefore maintain margin,” he said, adding that he expects Micron to emphasize diversified demand, disciplined capital spending and its ability to sustain operating margins around 70%.
“Ultimately, it comes down to who can have a 70% margin profile in AI,” he said, naming memory, foundries and customers such as Nvidia (NVDA) and AMD (AMD).
Current Memory Cycle Different From Past
He also stated that the current memory cycle differs from earlier periods because demand is coming from a broader range of applications and customers rather than being concentrated in smartphones.
“Now we have a diversification in demand drivers. We also have diversification in customer base,” Hosseini said. “So you have a diversification in application and customers, and this is what drives the sustainability of pricing.”
The shift from AI training to inference could further increase memory demand, he said, citing DRAM requirements for CPUs and the storage needed to support growing AI workloads.
Wall Street On MU Stock Ahead Of Q4 Earnings
Other analysts remain focused on the strength and durability of Micron’s current memory cycle. JPMorgan called the setup “constructive” heading into earnings. The firm reiterated an ‘Overweight’ rating and a $1,540 price target, citing “multiple beat-and-raise levers still in play” for Micron.
Wells Fargo also remained bullish on Micron heading into the fourth quarter, although analyst Aaron Rakers lowered the price target on MU shares to $1,400 from $1,525 while maintaining an ‘Overweight’ rating.
Rakers said the next phase of MU’s performance will depend on investors gaining greater confidence in the duration of the current memory shortage, as well as on the expansion of Strategic Customer Agreement engagements and on Micron’s execution.
Morgan Stanley, Baird and Citi have also remained broadly positive on Micron’s outlook, while investors increasingly focus on how long tight memory supply and elevated pricing can persist.
How Is Retail Feeling About MU Stock?
On Stocktwits, retail sentiment around MU stock rose to ‘extremely bullish’ from ‘bullish’ territory over the past day, accompanied by ‘high’ levels of chatter
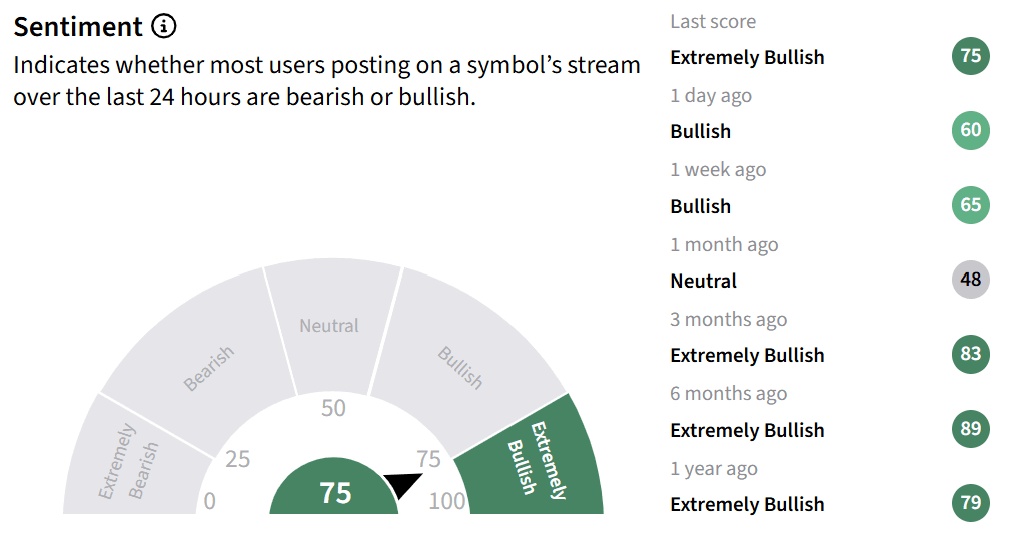
An ongoing Stocktwits poll showed more than 75% of respondents expecting Micron to deliver a double beat after the market close.
The debate among traders, however, is increasingly moving beyond whether Micron can beat quarterly estimates. One trader argued that the bigger issue is the 2027 guidance, while another pointed out that strong earnings may not immediately translate into a stock rally.
View this Stocktwits post
View this Stocktwits post
MU stock has gained over 275% this year and surged more than 540% in the last 12 months.
Read also: CRWV Stock Gets An 'Outperform' Rating – William Blair Says Rapid Scaling Of AI Is Creating Substantial Demand
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
Stay updated with all the latest Business NewsShare Market NewsIPOsGold PriceDA Hike8th Pay CommissionAsianet News Official App