Michael Burry Weighs Peter Schiff’s S&P 500 Crash Warning As UBS Flags Fed Risk — Rare October Hike Odds Hit 70%
Synopsis
Peter Schiff warned that the S&P 500 was near a record even as 430 of its stocks sat an average of 21.7% below their individual highs.
- Burry said on Monday that he replaced several stock shorts with puts, warning the AI bubble could burst “sooner than later.”
- UBS said the Fed’s rate path would likely shape the S&P 500’s next move after a sharp rise in the 10-year Treasury yield.
- CME FedWatch put the odds of an Oct.28 quarter-point hike at 72.5%, up from 17.7% a month earlier.
“The Big Short” investor Michael Burry said that he cannot dismiss economist Peter Schiff’s warning about weakness beneath the S&P 500’s near-record level, as rising Treasury yields and growing bets on an October Federal Reserve rate hike put another potential pressure point in view.
The tech-heavy Invesco QQQ Trust (QQQ) has led the major index funds in September, gaining 2.9%, while the SPDR S&P 500 ETF Trust (SPY) is up just 0.06% and the SPDR Dow Jones Industrial Average ETF Trust (DIA) has fallen 3.1%.
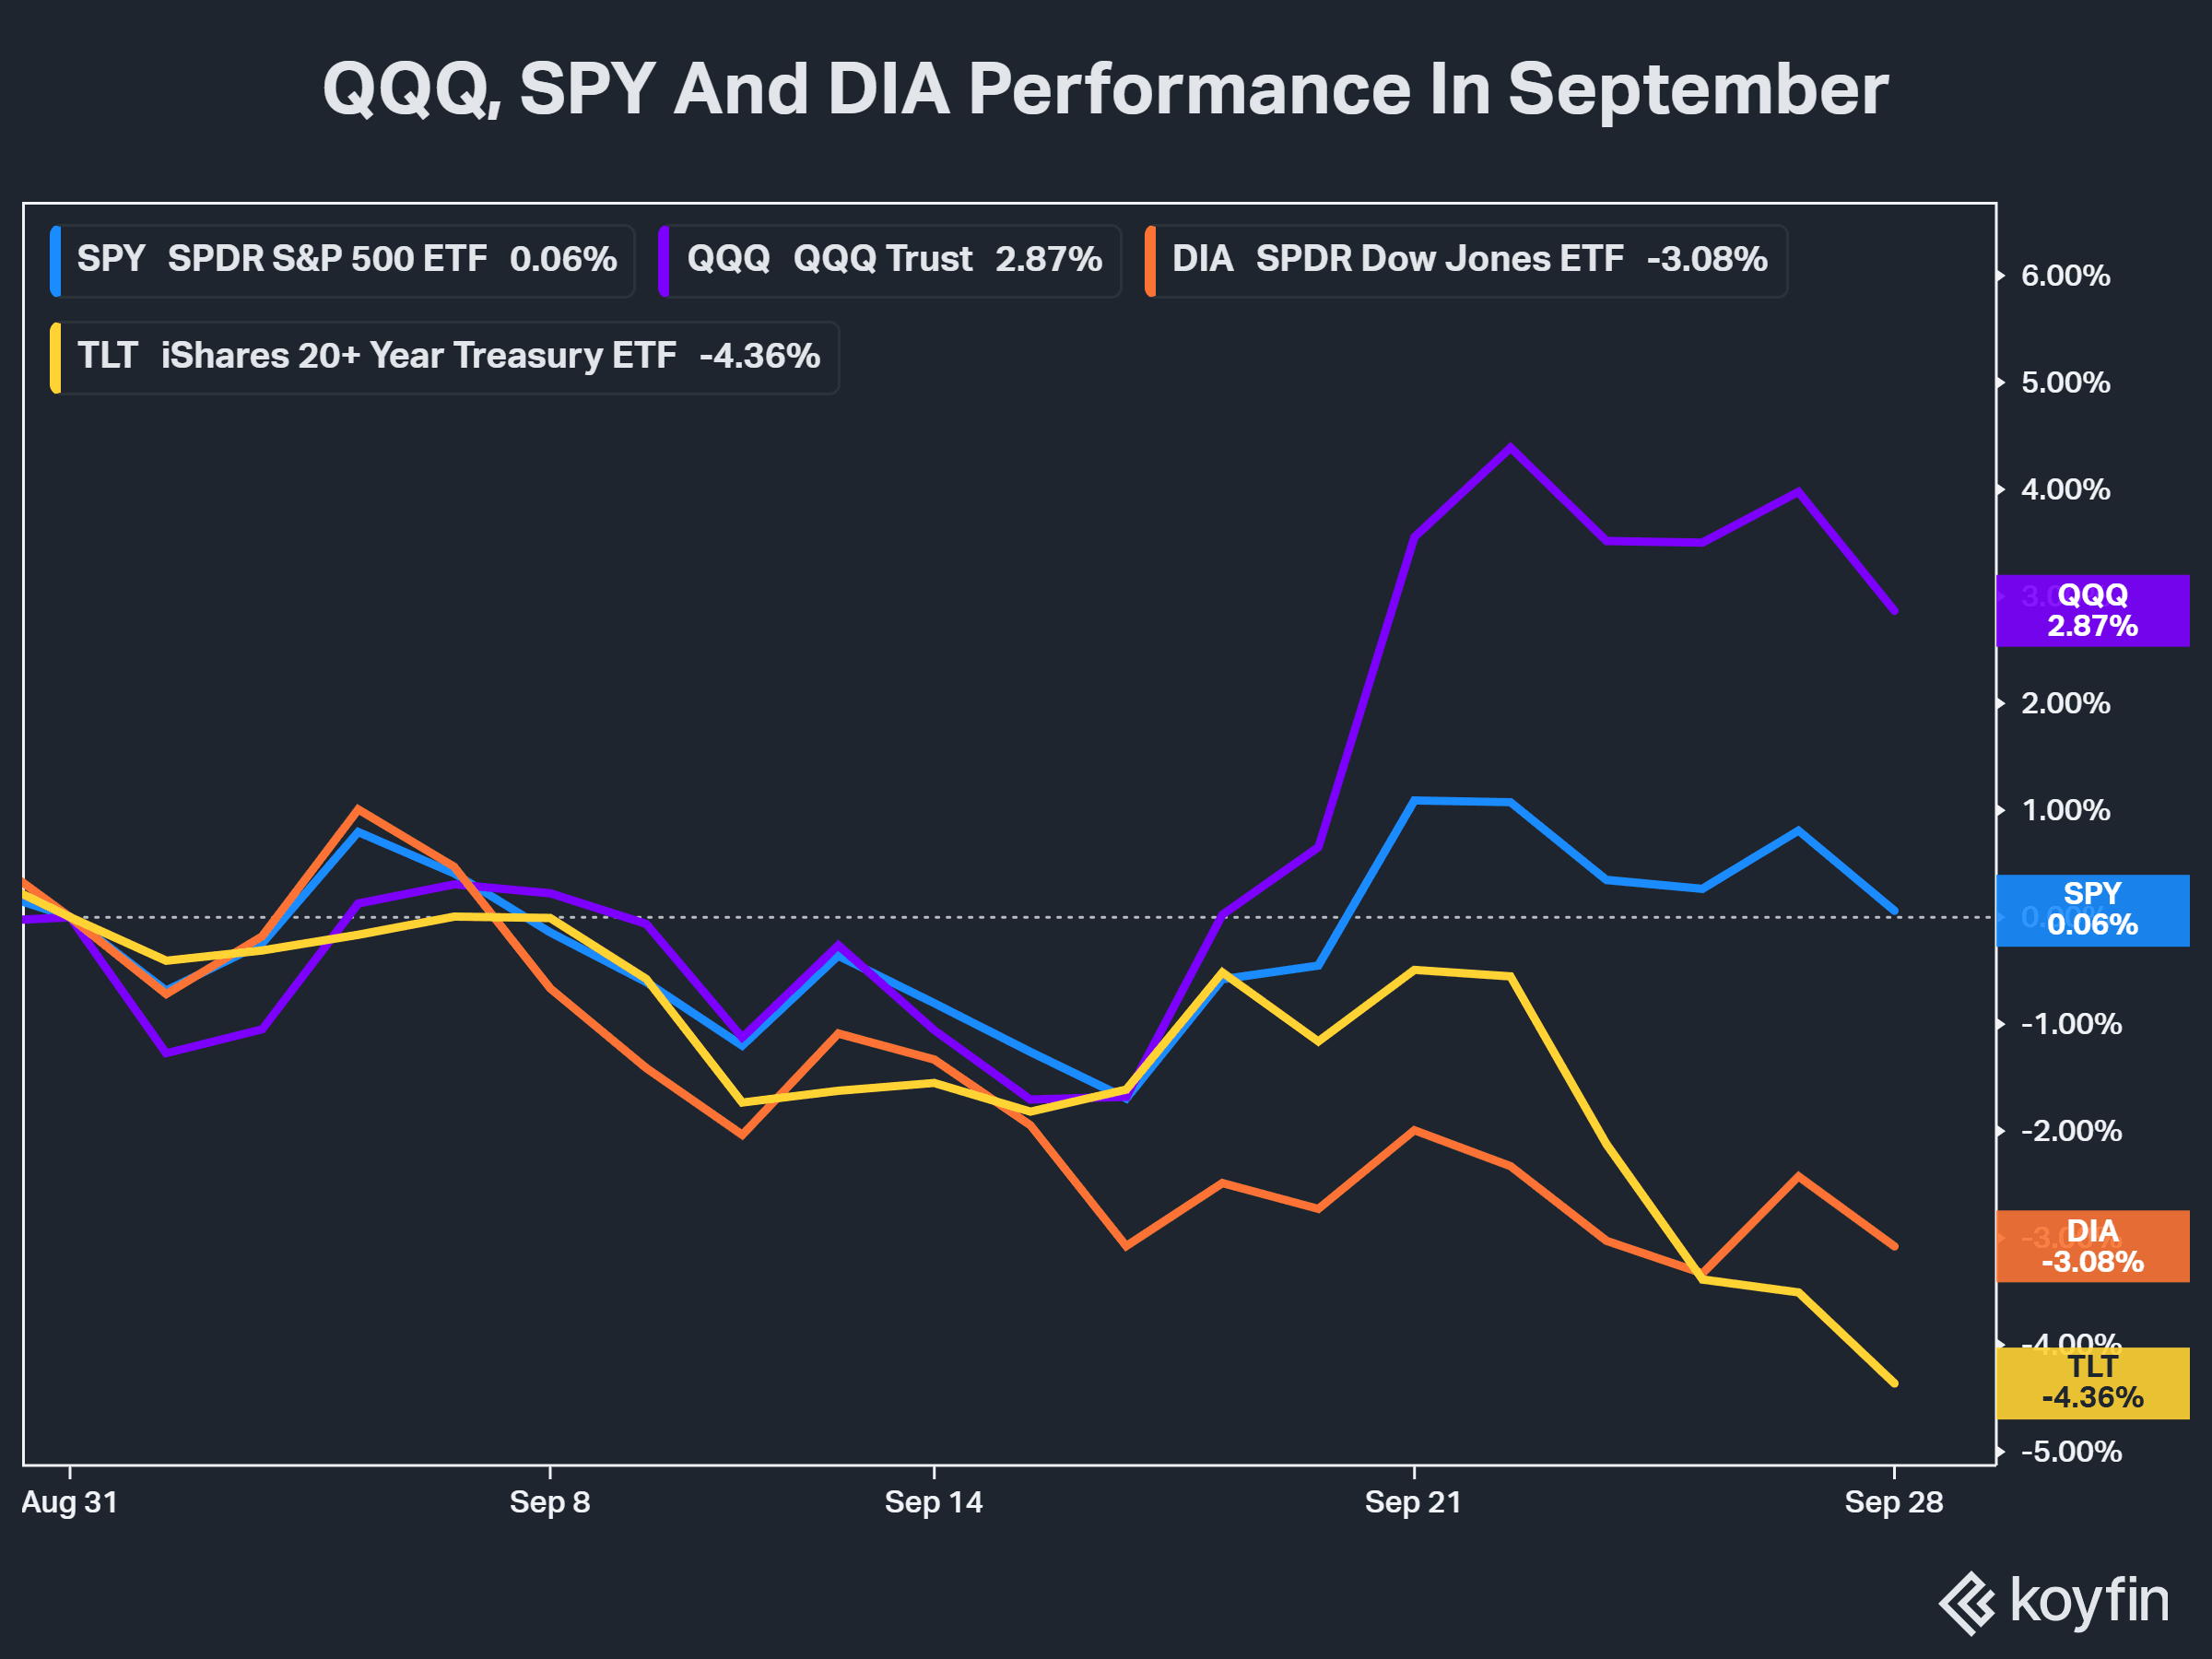
All three have fared better than the iShares 20+ Year Treasury Bond ETF (TLT), down 4% this month. The gap holds for the year: QQQ is up 20.3%, SPY has gained 13.2% and DIA has risen 8.1%, while TLT has lost 7%.
Burry Can’t Dismiss Schiff’s Market Warning
Over the weekend, Schiff said on X that the S&P 500 was just 0.7% below its record, while 430 of its stocks were, on average, 21.7% below their individual highs. He compared the weak market breadth with January 1973 and 1999-2000, saying the index subsequently crashed 50% on both occasions.
“This has been making the rounds and I would like to disagree with the implication. However, I cannot,” Burry said in response to Schiff’s post on his Substack chat.
Burry’s response follows a series of warnings about stretched valuations. In May, he acknowledged that he was “a meme for the number of times I have called a crash,” but pointed to a breadth reading of 52% while the S&P 500 stood more than 7% above its 50-day average. His readings clustered around the late-1990s and early-2000 market peak.
Last week, Burry called the Nasdaq 100 “historically overvalued” and “historically top heavy” as it approached another high. Then, on Monday, he said that he had replaced several short-stock positions with put options because “the bubble in AI may burst sooner than later.”
UBS Sees Fed Rates Steering S&P 500
Rising bond yields gave investors another reason to watch the Fed. In a Monday note, UBS said that the central bank’s rate path would likely shape the S&P 500’s next move, according to MarketWatch.
The brokerage firm said that the 10-year Treasury yield has risen this far above its one-year average only eight times since 1985, including now. In the seven earlier episodes, the S&P 500 was flat on average over the next three months but gained 5% to 10% over the following six to 12 months. The firm expects about two months of elevated, though stabilizing, rates.
Traders Bet On Unusual Pre-Election Rate Hike
The Fed’s next rate decision is due Oct.28, six days before the Nov.3 midterm elections. CME FedWatch put the odds of a quarter-point hike at 72.5% on Tuesday, up from 55.4% a week ago and 17.7% a month ago.
A hike that close to an election would be unusual, but it has happened before. CME’s review of 27 election years found that the Fed left rates unchanged between Oct.1 and Election Day 67% of the time. It recorded October increases in 1978, before the midterms, and 1980, before a presidential election, as the central bank fought inflation.
How Do Retail Traders Feel About The Market?
Retail traders stayed upbeat across stocks and long-term Treasuries on Stocktwits. Sentiment for SPY was ‘extremely bullish’ amid ‘high’ message volume, while QQQ and TLT both drew ‘bullish’ sentiment with ‘high’ activity. DIA was also ‘bullish,’ though its message volume was ‘normal.’
One user said, “$TLT the bounce will look obvious in retrospect, but most have bought into the ridiculous idea that rates can continue higher without breaking something.”
View this Stocktwits post
Another user said, “I think by summer of 2027 the ten year yield will be anywhere from 5.5%-6.3%. Folks have to get use to playing in a higher yield environment. Easy money and cheap credit are over.. you either adapt or get left behind..”
View this Stocktwits post
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
Stay updated with all the latest Business NewsShare Market NewsIPOsGold PriceDA Hike8th Pay CommissionAsianet News Official App