Michael Burry Warns Nvidia, AI Infrastructure Expansion Mirroring 1960s Computer Leasing Bubble
Synopsis
Famed “The Big Short” investor Michael Burry argues that temporary hardware shortages are masking rapid GPU depreciation and creating structural risks across tech and private credit sectors.
- Burry says Nvidia’s recent presentations on residual GPU values rely on long-term discounted cash flow models rather than actual secondary market prices.
- Recent rebounds in older GPU rental rates stem from global memory and energy bottlenecks, not long-term hardware durability.
- The widespread use of GPU-backed debt financing and private credit to build out AI capacity echoes the unsustainable 1960s tech leasing models, Burry says.
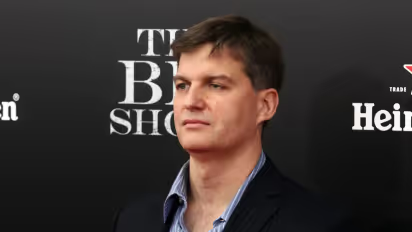
Renowned investor Michael Burry has issued a stark warning to technology investors, alleging that the aggressive capital deployment into artificial intelligence infrastructure mirrors the unsustainable computer-leasing mania of the late 1960s.
Writing in his Substack newsletter, Cassandra Unchained, Burry highlights what he views as structural accounting and financial flaws in the AI market, specifically targeting Nvidia Corp.'s (NVDA) claims regarding graphics processing unit (GPU) residual values and depreciation schedules.
A point to note is that Burry also repositioned his portfolio last week, replacing short common-stock positions with put options.
Burry covered all his short common-stock positions in Micron (MU), Nebius (NBIS), Caterpillar (CAT), iShares Semiconductor ETF (SOXX), CoreWeave (CRWV), Nvidia (NVDA) and Palantir (PLTR). He replaced the Nvidia short with September 2027 puts at strikes in the mid $100s.
Accounting Realities
At the center of Burry’s criticism is a slide from Nvidia's late-September investor presentation that showed AI infrastructure retains high residual value well beyond standard five-year accelerated depreciation schedules. Market bulls celebrated the data as evidence of the hardware's lasting economic value.
However, Burry asserts that the chart—derived from analytics firm Silicon Data—does not reflect actual resale prices for second-hand equipment. Instead, it maps a discounted cash flow (DCF) model based on forward rental-income projections over an assumed eight-year physical chip life.
Burry notes that comparing an eight-year cash flow model against a steep five-year depreciation curve creates an "apples-to-oranges" illusion. He contends that Nvidia’s reliance on accelerated depreciation curves is an implicit admission of how severely each new product generation devalues its predecessors.
The Memory Bottleneck
While older chip architectures like the A100 and H100 have seen stabilized or rising rental rates in recent months, Burry points out that this trend stems from acute supply-chain bottlenecks rather than the silicon's intrinsic durability.
"A chip earning more than it costs is a sign of scarcity due to memory and power shortages, not GPU die shortages and not durability," Burry writes.
Once these underlying component shortages ease and newer, more efficient architectures like Nvidia's Vera Rubin ramp up, Burry notes, rental prices for legacy hardware are expected to drop significantly.
Similarities With 1968 Computer Leasing Crisis
To illustrate the trajectory of the current AI boom, Burry points to 1968, when third-party computer leasing companies undercut IBM by offering extended eight-year depreciation schedules compared to IBM's conservative four-year timeline.
While those 1960s leasing startups were correct that mainframes would physically function for years, they failed to anticipate how drastically rental yields would collapse when IBM launched its next-generation System/370. By 1970, computer leasing equities fell by roughly 80%, wiping out heavily leveraged funds and sparking industry-wide insolvencies.
Burry warns that a similar dynamic is unfolding across modern neoclouds and private equity-backed data centers. With hundreds of billions of dollars in GPU buildouts increasingly financed through structured debt, asset-backed loans, and private credit channels, any sudden compression in rental yields could shift massive liabilities onto institutional lenders and private insurers.
NVDA Stock: Retail View
Retail sentiment on Stocktwits was ‘neutral’ with ‘normal’ message volumes.
NVDA stock has gained 23% year-to-date.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<
Stay updated with all the latest Business NewsShare Market NewsIPOsGold PriceDA Hike8th Pay CommissionAsianet News Official App